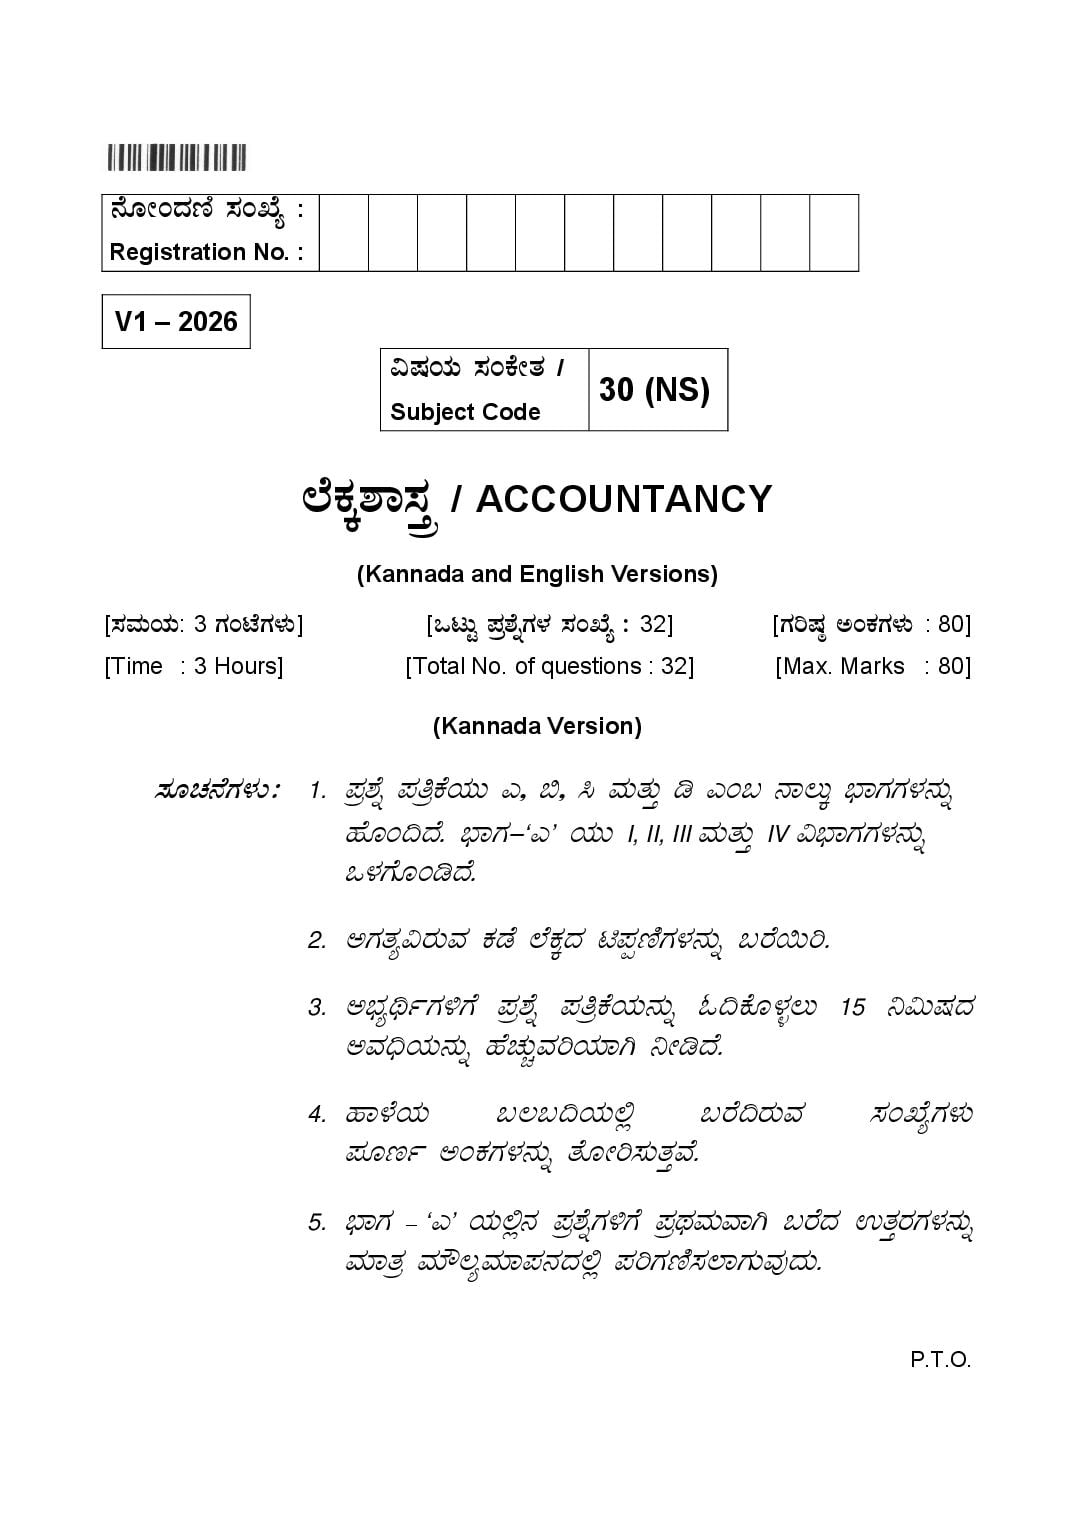
Karnataka 2nd PUC Question Paper 2026 Accountancy
Finished viewing? Save it for later —
Download Karnataka 2nd PUC Question Paper 2026 Accountancy (PDF · 24 pages)About Karnataka 2nd PUC Question Paper 2026 Accountancy
Karnataka 2nd PUC Question Paper 2026 Accountancy is available here for free download. Published by Karnataka Board for Class 12, this question paper can be viewed online or downloaded as a PDF (24 pages). Candidates preparing for Class 12 can use Karnataka 2nd PUC Question Paper 2026 Accountancy to understand the exam pattern, the type of questions asked, and the overall difficulty level.
Frequently Asked Questions
How can I download Karnataka 2nd PUC Question Paper 2026 Accountancy?
Open this page and click the Download button to save Karnataka 2nd PUC Question Paper 2026 Accountancy as a PDF. It is completely free on AglaSem Docs.
Is Karnataka 2nd PUC Question Paper 2026 Accountancy free to download?
Yes. Karnataka 2nd PUC Question Paper 2026 Accountancy can be viewed online and downloaded as a PDF free of cost on AglaSem Docs.
How many pages does Karnataka 2nd PUC Question Paper 2026 Accountancy have?
Karnataka 2nd PUC Question Paper 2026 Accountancy contains 24 pages, which you can read online or download together as a single PDF.
Where can I find more Class 12 study material?
You can find more Class 12 question papers, sample papers, syllabus, and answer keys on AglaSem Docs.
Karnataka 2nd PUC Question Paper 2026 Accountancy – Text
Read the full text of this question paper below — useful to quickly search, copy and reference the content online without downloading the PDF.
📄 View text version (24 pages)
Page 1
Registration No. :
V1 – 2026
«µÀAiÀÄ ¸ÀAPÉÃvÀ /
30 (NS)
Subject Code
¯ÉPÀ̱Á¸ÀÛç / ACCOUNTANCY
(Kannada and English Versions)
[¸ÀªÀÄAiÀÄ: 3 UÀAmÉUÀ¼ÀÄ] [MlÄÖ ¥Àæ±ÉßUÀ¼À ¸ÀASÉå : 32] [UÀjµÀ× CAPÀUÀ¼ÀÄ : 80]
[Time : 3 Hours] [Total No. of questions : 32] [Max. Marks : 80]
(Kannada Version)
ÓÜãaÜ®æWÜÙÜá : 1. ¥Àæ±Éß ¥ÀwæPÉAiÀÄÄ J, ©, ¹ ªÀÄvÀÄÛ r JA§ £Á®ÄÌ ¨sÁUÀU¼ À £
À ÄÀ ß
ºÉÆA¢zÉ. ¨sÁUÀ-‘J’ AiÀÄÄ I, II, III ªÀÄvÀÄÛ IV «¨sÁUÀUÀ¼À£ÀÄß
M¼ÀUÉÆArzÉ.
2. CUÀvÀå«gÀĪÀ PÀqÉ ¯ÉPÀÌzÀ n¥ÀàtÂUÀ¼À£ÀÄß §gɬÄj.
3. C¨sÀåyðUÀ½UÉ ¥Àæ±Éß ¥ÀwæPÉAiÀÄ£ÀÄß N¢PÉƼÀî®Ä 15 ¤«ÄµÀÀzÀ
CªÀ¢üAiÀÄ£ÀÄß ºÉZÀÄѪÀjAiÀiÁV ¤ÃrzÉ.
4. ºÁ¼ÉAiÀÄ §®§¢AiÀÄ°è §gÉ¢gÀĪÀ ¸ÀASÉåUÀ¼ÀÄ
¥ÀÆtð CAPÀUÀ¼À£ÀÄß vÉÆÃj¸ÀÄvÀÛªÉ.
5. ¨sÁUÀ – ‘J’ AiÀÄ°è£À ¥Àæ±ÉßUÀ½UÉ ¥ÀæxÀªÀĪÁV §gÉzÀ GvÀÛgÀUÀ¼À£ÀÄß
ªÀiÁvÀæ ªÀiË®åªÀiÁ¥À£ÀzÀ°è ¥ÀjUÀt¸À¯ÁUÀĪÀÅzÀÄ.
P.T.O.
Page 2
»ÝWÜ & G
I. PÉÆnÖgÀĪÀ DAiÉÄÌUÀ¼À°è ¸ÀjAiÀiÁzÀ GvÀÛgÀªÀ£ÀÄß Dj¹ §gɬÄj : (5 × 1 = 5)
1) ¥Á®ÄzÁjPÉAiÀÄ£ÀÄß gÀa¸À®Ä EgÀ¨ÉÃPÁzÀ PÀ¤µÀÖ ¸ÀASÉå :
a) M§â ªÀåQÛ b) JgÀqÀÄ d£À
c) K¼ÀÄ d£À d) LªÀvÀÄÛ d£À
2) A, B ªÀÄvÀÄÛ C ¥Á®ÄzÁgÀgÁVzÀÄÝ ¯Á¨sÀUÀ¼À£ÀÄß 5 : 3 : 2 C£ÀÄ¥ÁvÀzÀ°è
ºÀAaPÉƼÀÄîvÁÛgÉ. MAzÀÄ ªÉÃ¼É C ¤ªÀÈwÛAiÀiÁzÀgÉ, A ªÀÄvÀÄÛ B EªÀgÀ
£ÀqÀÄ«£À ºÉƸÀ ¯Á¨sÀ ºÀAaPÉAiÀÄ C£ÀÄ¥ÁvÀªÀÅ :
a) 3:2 b) 5:3
c) 5:2 d) 1:1
3) zÁR°¸ÀzÀ ºÉÆuÉUÁjPÉUÀ¼À£ÀÄß ¥ÁªÀw¹zÁUÀ E°è vÉÆÃj¸À¯ÁUÀĪÀÅzÀÄ.
a) «¯ÉêÁj SÁvÉAiÀÄ Rað£À §¢
b) ¨ÁåAPï SÁvÉAiÀÄ Rað£À §¢
c) «¯ÉêÁj SÁvÉAiÀÄ dªÀiÁ §¢
d) £ÀUÀzÀÄ SÁvÉAiÀÄ Rað£À §¢
4) ¤ÃrzÀ §AqÀªÁ¼ÀªÀÅ EzÀgÀ ¨sÁUÀªÁVzÉ.
a) «ÄøÀ®Ä §AqÀªÁ¼À b) ¤ÃqÀzÀ §AqÀªÁ¼À
c) C¢üPÀÈvÀ §AqÀªÁ¼À d) ªÀAwUÉAiÀiÁzÀ §AqÀªÁ¼À
5) F PɼÀV£ÀzÀÄ C¸ÁªÀiÁ£Àå ¨Á§ÄÛ DVzÉ.
a) ¸ÀA§¼À ¥ÁªÀw b) vÉjUÉ ¥ÁªÀw
c) ¨ÁrUÉ ¥ÁªÀw d) PÀ¼ÀîvÀ£À¢AzÁzÀ £ÀµÀÖ
Page 3
II. DªÀgÀtzÀ°è PÉÆnÖgÀĪÀ GvÀÛgÀUÀ¼À°è ¸ÀjAiÀiÁzÀ GvÀÛgÀªÀ£ÀÄß Dj¹,
SÁ° ©lÖ ¸ÀܼÀUÀ¼À£ÀÄß ¨sÀwð ªÀiÁrj. (5 × 1 = 5)
[£ÀUÀzÀÄ/¨ÁåAPÀÄ, ®A¨ÁvÀäPÀ, ºÀ£ÉßgÀqÀÄ, M¥ÀàAzÀ, vÁåUÀzÀ, E¥ÀàvÀÄÛ]
6) ¥Á®ÄzÁjPÉAiÀÄÄ ¥Á®ÄzÁgÀgÀ¯ÁèzÀ ___________ zÀ ªÀÄÆ®PÀ
C¹ÛvÀézÀ°è §gÀÄvÀÛzÉ.
7) ºÀ¼ÉAiÀÄ C£ÀÄ¥ÁvÀ – ºÉƸÀ C£ÀÄ¥ÁvÀ = ___________ C£ÀÄ¥ÁvÀ.
8) ¸ÀA¸ÉÜAiÀÄÄ «¸Àdð£ÉAiÀiÁzÁUÀ, ¥Á®ÄzÁgÀ£À ¸Á®zÀ SÁvÉAiÀÄ£ÀÄß
___________ SÁvÉUÉ ªÀUÁðªÀuÉ ªÀiÁqÀ¯ÁUÀÄvÀÛzÉ.
9) ___________ wAUÀ¼ÀÄUÀ¼À M¼ÀUÉ ¥ÁªÀw¸À¨ÉÃPÁVgÀĪÀ ¸Á®UÀ¼À£ÀÄß
C¯ÁàªÀ¢ü ¸Á®UÀ¼É£ÀÄߪÀgÀÄ.
10) ¸ÁªÀiÁ£Àå UÁvÀæzÀ vÀBSÉÛAiÀÄ£ÀÄß ___________ «±ÉèõÀuÉ JAzÀÆ PÀÆqÀ
PÀgÉAiÀįÁUÀÄvÀÛzÉ.
III. ºÉÆA¢¹ §gɬÄj. (5 × 1 = 5)
11) A B
a) QÃwðªÀiË®åzÀ ªÀiË®åªÀiÁ¥À£À i) ¸Á® ¹éÃPÀÈw ¥ÀvÀæ
b) ¸Á®¥ÀvÀæUÀ¼ÀÄ ii) ¥Àæw ±ÉÃj£À UÀ½PÉ
c) PÁAiÀiÁðZÀgÀuÉUÀ½AzÁzÀ iii) £ÀUÀzÀÄ M¼ÀºÀjªÀÅ ªÀÄvÀÄÛ
PÀAzÁAiÀÄ (DzÁAiÀÄ) ºÉÆgÀºÀjªÀÅUÀ¼ÀÄ
d) ¯Á¨sÀzÁAiÀÄPÀvÉ C£ÀÄ¥ÁvÀ iv) ¸ÀgÁ¸Àj ¯Á¨sÀzÀ «zsÁ£À
e) £ÀUÀzÀÄ ºÀjªÀÅ vÀBSÉÛ v) ªÀiÁgÁl
vi) ºÀtPÁ¹£À ¹Üw
Page 4
IV. PɼÀV£À ¥Àæ±ÉßUÀ½UÉ 1 ¥ÀzÀ CxÀªÁ 1 ªÁPÀåzÀ°è GvÀÛj¹. (5 × 1 = 5)
12) ¥Á®ÄzÁgÀ£À ¤ªÀÈwÛ ¸ÀAzÀ¨sÀðzÀ°è ªÀÄgÀĪÀiË®åªÀiÁ¥À£ÀzÀ ªÉÄð£À ¯Á¨sÀ
CxÀªÁ £ÀµÀÖªÀ£ÀÄß J¯Áè ¥Á®ÄzÁgÀgÀ §AqÀªÁ¼À SÁvÉUÀ½UÉ
ªÀUÁð¬Ä¸À¯ÁUÀĪÀÅzÀÄ. [¸Àj/vÀ¥ÀÄà w½¹]
13) ±ÉÃgÀÄUÀ¼À AiÀiÁªÀÅzÁzÀgÀÆ MAzÀÄ ¥ÀæPÁgÀªÀ£ÀÄß w½¹.
14) ¸Á®¥ÀvÀæUÀ¼À «ªÉÆÃZÀ£É JAzÀgÉãÀÄ?
15) ºÀtPÁ¹£À vÀBSÉÛ «±ÉèõÀuÉAiÀÄ£ÀÄß G¥ÀAiÉÆÃV¸ÀĪÀ M§â §¼ÀPÉzÁgÀgÀ£ÀÄß
ºÉýj.
16) R.O.I C£ÀÄß «¸ÀÛj¹.
»ÝWÜ & ©
V. PɼÀV£À AiÀiÁªÀÅzÁzÀgÀÆ ªÀÄÆgÀÄ ¥Àæ±ÉßUÀ½UÉ GvÀÛj¹. ¥Àæw ¥Àæ±ÉßUÉ 2 CAPÀUÀ¼ÀÄ.
(3 × 2 = 6)
17) ¹ÜgÀ §AqÀªÁ¼À «zsÁ£À ªÀÄvÀÄÛ §zÀ¯ÁUÀĪÀ §AqÀªÁ¼À «zsÁ£À EªÀÅUÀ¼À
£ÀqÀÄ«£À AiÀiÁªÀÅzÁzÀgÀÆ JgÀqÀÄ ªÀåvÁå¸ÀUÀ¼À£ÀÄß w½¹.
18) ¤ªÀÈwÛAiÀiÁUÀĪÀ ¥Á®ÄzÁgÀ¤UÉ PÉÆqÀ¨ÉÃPÁzÀ ªÉÆvÀÛªÀ£ÀÄß ¸ÀAzÁAiÀÄ
ªÀiÁqÀĪÀ AiÀiÁªÀÅzÁzÀgÀÆ JgÀqÀÄ «zsÁ£ÀUÀ¼À£ÀÄß w½¹.
19) C¢üPÀ ªÀAwUÉAiÀÄ CxÀðªÀ£ÀÄß PÉÆr.
20) ºÀtPÁ¹£À vÀBSÉÛUÀ¼À JgÀqÀÄ ¥ÀæPÁgÀUÀ¼À£ÀÄß ºÉ¸Àj¹.
21) ºÀtPÁ¸ÀÄ MzÀV¸ÀĪÀ ZÀlĪÀnPÉUÀ½UÉ AiÀiÁªÀÅzÁzÀgÀÆ JgÀqÀÄ
GzÁºÀgÀuÉUÀ¼À£ÀÄß §gɬÄj.
Page 5
»ÝWÜ & Ô
VI. AiÀiÁªÀÅzÁzÀgÀÆ ªÀÄÆgÀÄ ¥Àæ±ÉßUÀ½UÉ GvÀÛj¹. ¥Àæw ¥Àæ±ÉßUÉ 6 CAPÀUÀ¼ÀÄ.
(3 × 6 = 18)
22) ¢£ÁAPÀ 01-04-2024 gÀAzÀÄ gÀ« ªÀÄvÀÄÛ QgÀuï PÀæªÀĪÁV 1,50,000 ªÀÄvÀÄÛ
1,00,000 §AqÀªÁ¼ÀUÀ¼ÉÆA¢UÉ ¥Á®ÄzÁjPÉ ªÀåªÀºÁgÀ ¥ÁægÀA©ü¹zÀgÀÄ.
CªÀgÀ ¯Á¨sÀ ªÀÄvÀÄÛ £ÀµÀÖzÀ ºÀAaPÉAiÀÄ C£ÀÄ¥ÁvÀ 3 : 2 DVgÀÄvÀÛzÉ.
F PɼÀV£À ºÉÆAzÁtÂPÉUÀ¼À ªÉÆzÀ®Ä, ¥Àæ¸ÀPÀÛ ªÀµÀðzÀ°è CªÀgÀÄ
50,000 ¯Á¨sÀ UÀ½¹zÁÝgÉ :
a) §AqÀªÁ¼ÀzÀ ªÉÄÃ¯É ±ÉÃPÀqÁ 10 gÀAvÉ ªÁ¶ðPÀ §rØ.
b) ¸ÀéAvÀªÉZÀÑzÀ ªÉÄð£À §rØ : gÀ« 4,000 ªÀÄvÀÄÛ QgÀuï 2,000.
c) gÀ«UÉ ªÁ¶ðPÀ zÀ¯Áè½ 3,000.
d) QgÀuï£À ¸ÀA§¼À ªÁ¶ðPÀ 8,000.
¢£ÁAPÀ 31.03.2025 PÉÌ CAvÀåUÉƼÀÄîªÀ ªÀµÀðzÀ ¯Á¨sÀ ªÀÄvÀÄÛ £ÀµÀÖ
«¤AiÉÆÃUÀ SÁvÉAiÀÄ£ÀÄß vÀAiÀiÁj¹.
23) VÃvÁ, ®vÁ ªÀÄvÀÄÛ ¸ÀAVÃvÁ ¥Á®ÄzÁgÀgÁVzÀÄÝ, ¯Á¨sÀ ªÀÄvÀÄÛ £ÀµÀÖªÀ£ÀÄß
C£ÀÄPÀæªÀĪÁV 5:3:2 gÀ C£ÀÄ¥ÁvÀzÀ°è ºÀAaPÉƼÀÄîvÁÛgÉ. ®vÁ
¸ÀA¸ÉܬÄAzÀ ¤ªÀÈwÛ ºÉÆAzÀÄvÁÛ¼É. VÃvÁ ªÀÄvÀÄÛ ¸ÀAVÃvÁ ¨sÀ«µÀåzÀ
¯Á¨sÀªÀ£ÀÄß 3 : 2 gÀ C£ÀÄ¥ÁvÀzÀ°è ºÀAaPÉƼÀî®Ä ¤zsÀðj¸ÀÄvÁÛgÉ.
VÃvÁ ªÀÄvÀÄÛ ¸ÀAVÃvÁ EªÀgÀ UÀ½PÉAiÀÄ C£ÀÄ¥ÁvÀªÀ£ÀÄß PÀAqÀÄ»r¬Äj.
Page 6
24) C¤®, «±Á® ªÀÄvÀÄÛ ¸ÀĤî ¥Á®ÄzÁgÀgÁVzÀÄÝ, ¯Á¨sÀ ªÀÄvÀÄÛ £ÀµÀÖªÀ£ÀÄß
4 : 3 : 3 gÀ C£ÀÄ¥ÁvÀzÀ°è ºÀAaPÉƼÀÄîvÁÛgÉ. ¢£ÁAPÀ 01.04.2025 gÀAzÀÄ
CªÀgÀ §AqÀªÁ¼ÀUÀ¼ÀÄ C£ÀÄPÀæªÀĪÁV 1,00,000, 80,000 ªÀÄvÀÄÛ 50,000
DVªÉ.
¢£ÁAPÀ 31.12.2025 gÀAzÀÄ «±Á® ¤zsÀ£À ºÉÆA¢zÀ£ÀÄ. ¥Á®ÄzÁjPÉ
PÀgÁgÀÄ¥ÀvÀæªÀÅ PɼÀV£ÀªÀÅUÀ¼À£ÀÄß M¼ÀUÉÆArzÉ.
a) §AqÀªÁ¼ÀzÀ ªÉÄð£À §rØ ªÁ¶ðPÀ ±ÉÃPÀqÁ 12 gÀAvÉ.
b) «±Á®¤UÉ ¸ÀA§¼À ¥Àæw wAUÀ½UÉ 2,000.
c) «±Á®£À ¥Á°£À QÃwðªÀiË®å 14,000 [A.S. - 26 gÀ ¥ÀæPÁgÀ].
d) »A¢£À ªÀµÀðzÀ ¯Á¨sÀzÀ DzsÁgÀzÀ ªÉÄïÉ, ¤zsÀ£À ºÉÆA¢zÀ
¢£ÁAPÀzÀªÀgÉUÉ UÀ½¸À®àlÖ ¯Á¨sÀzÀ°è «±Á®£À ¥Á®Ä.
»A¢£À ªÀµÀðzÀ°è ¸ÀA¸ÉÜAiÀÄ ¯Á¨sÀªÀÅ 36,000 DVzÉ.
«±Á®£À ªÁgÀ¸ÀÄzÁgÀgÀ SÁvÉAiÀÄ£ÀÄß vÀAiÀiÁj¹j.
25) F PɼÀV£À «ªÀgÀUÀ½AzÀ, PÀA¥À¤UÀ¼À PÁ¬ÄzÉ, 2013 gÀ ¥ÀjZÉÒÃzÀ-III gÀ
¥ÀæPÁgÀ, ¢£ÁAPÀ 31.03.2025 gÀAzÀÄ PÉÆ£ÉUÉÆAqÀ ªÀµÀðzÀ
¯Á¨sÀ ªÀÄvÀÄÛ £ÀµÀÖ vÀBSÉÛAiÀÄ£ÀÄß vÀAiÀiÁj¹.
«ªÀgÀUÀ¼ÀÄ
PÁAiÀiÁðZÀgÀuÉUÀ½AzÁzÀ PÀAzÁAiÀÄ 8,00,000
RjâUÀ¼ÀÄ 4,00,000
ªÉÃvÀ£ÀUÀ¼ÀÄ 1,00,000
ºÀtPÁ¸ÀÄ ªÉZÀÑUÀ¼ÀÄ 30,000
¸ÀªÀPÀ½ 20,000
¨ÁrUÉ 15,000
DqÀ½vÁvÀäPÀ ªÉZÀÑUÀ¼ÀÄ 35,000
DzÁAiÀÄ vÉjUÉ 60,000
Page 7
26) ¢£ÁAPÀ 31.03.2025 PÉÌ PÉÆ£ÉUÉƼÀÄîªÀ ªÀµÀðzÀ°è LG PÀA¥À¤ ¤AiÀÄ«ÄvÀ
EªÀgÀÄ 7,00,000 ¤ªÀé¼À ¯Á¨sÀ UÀ½¹zÁÝgÉ. ªÀµÀðzÀ ¸ÀªÀPÀ½ ªÉZÀÑ
1,50,000 DVzÉ. D¹ÛUÀ¼À ªÀiÁgÁlzÀ ªÉÄð£À ¯Á¨sÀ 60,000 EzÀÄÝ,
CzÀ£ÀÄß ¯Á¨sÀ ªÀÄvÀÄÛ £ÀµÀÖ vÀBSÉÛUÉ ªÀUÁð¬Ä¸À¯ÁVzÉ.
ªÀµÁðªÀ¢üAiÀÄ°è ªÁå¥Áj §gÀvÀPÀ̪ÀÅUÀ¼ÀÄ 55,000 PÀrªÉÄAiÀiÁVªÉ ªÀÄvÀÄÛ
ªÁå¥Áj PÉÆqÀvÀPÀ̪ÀÅUÀ¼ÀÆ ¸ÀºÀ 45,000 PÀrªÉÄAiÀiÁVªÉ.
¥ÀgÉÆÃPÀë «zsÁ£ÀzÀ°è PÁAiÀiÁðvÀäPÀ ZÀlĪÀnPÉUÀ½AzÁUÀĪÀ £ÀUÀzÀÄ ºÀjªÀ£ÀÄß
¯ÉPÁÌZÁgÀ ªÀiÁr.
»ÝWÜ & w
VII. AiÀiÁªÀÅzÁzÀgÀÆ ªÀÄÆgÀÄ ¥Àæ±ÉßUÀ½UÉ GvÀÛj¹. ¥Àæw ¥Àæ±ÉßUÉ 12 CAPÀUÀ¼ÀÄ.
(3 × 12 = 36)
27) UÉÆëAzÀ ªÀÄvÀÄÛ ¸ÀĢåÀ ¥Á®ÄzÁgÀgÁVzÀÄÝ, ¯Á¨sÀ ªÀÄvÀÄÛ £ÀµÀÖª£ À ÄÀ ß
C£ÀÄPÀæªÀĪÁV 3 : 1 gÀ C£ÀÄ¥ÁvÀzÀ°è ºÀAaPÉƼÀĪ
î ÀgÀÄ. ¢£ÁAPÀ 31.03.2025
gÀAzÀÄ CªÀgÀ CqsÁªÉ ¥ÀwæPÉ F PɼÀV£ÀAwzÉ :
¢£ÁAPÀ 31.03.2025 gÀAzÀÄ EgÀĪÀ CqsÁªÉ ¥ÀwæPÉ
ºÉÆuÉUÁjPÉUÀ¼ÀÄ D¹ÛUÀ¼ÀÄ
¸ÁºÀÄPÁgÀgÀÄ 45,000 £ÀUÀzÀÄ 16,000
PÉÆqÀvÀPÀÌ ºÀÄArUÀ¼ÀÄ 25,000 ¸Á®UÁgÀgÀÄ 40,000
¸ÁªÀiÁ£Àå «ÄøÀ®Ä 20,000 zÁ¸ÁÛ£ÀÄ 34,000
§AqÀªÁ¼ÀUÀ¼ÀÄ : ¦ÃoÉÆÃ¥ÀPÀgÀt 20,000
UÉÆëAzÀ 90,000 AiÀÄAvÉÆæÃ¥ÀPÀgÀt 30,000
¸ÀĢåÀ 40,000 PÀlÖqÀ 80,000
2,20,000 2,20,000
Page 8
¢£ÁAPÀ 01.04.2025 gÀAzÀÄ, F PɼÀV£À PÀgÁgÀÄUÀ¼À ªÉÄÃ¯É CªÀgÀÄ
vÀgÀÄuï£À£ÀÄß ¥Á®ÄzÁjPÉUÉ ¸ÉÃ¥ÀðqÉ ªÀiÁrPÉÆAqÀgÀÄ :
1
a) gÀ ¨sÁUÀzÀ ¯Á¨sÀPÁÌV vÀgÀÄuï 30,000 §AqÀªÁ¼ÀªÉAzÀÄ ªÀÄvÀÄÛ
5
10,000 QÃwðªÀiË®åPÁÌV £ÀUÀzÀÄ vÀgÀ¨ÉÃPÀÄ [A.S. – 26 gÀ ¥ÀæPÁgÀ].
b) QÃwðªÀiË®åzÀ ªÉÆvÀÛªÀ£ÀÄß ºÀ¼ÉAiÀÄ ¥Á®ÄzÁgÀgÀÄ »AzÀPÉÌ
¥ÀqÉAiÀÄÄvÁÛgÉ.
c) ¦ÃoÉÆÃ¥ÀPÀgÀtUÀ¼À ªÉÄÃ¯É ±ÉÃPÀqÁ 5 gÀµÀÄÖ ¸ÀªÀPÀ½ vÉUɬÄj.
d) PÀlÖqÀzÀ ªÀiË®åªÀ£ÀÄß ±ÉÃPÀqÁ 10 gÀµÀÄÖ ºÉaѹ.
e) AiÀÄAvÉÆæÃ¥ÀPÀgÀtªÀ£ÀÄß 27,000 PÉÌ ªÀÄgÀĪÀiË®å ªÀiÁrzÉ.
vÀAiÀiÁj¹ :
i) ¥ÀÄ£ÀgïªÀiË®åªÀiÁ¥À£À SÁvÉ,
ii) ¥Á®ÄzÁgÀgÀ §AqÀªÁ¼À SÁvÉUÀ¼ÀÄ ªÀÄvÀÄÛ,
iii) ¢£ÁAPÀ 01.04.2025 gÀAzÀÄ ¸ÀA¸ÉÜAiÀÄ ºÉƸÀ CqsÁªÉ ¥ÀwæPÉ.
28) C¤vÁ ªÀÄvÀÄÛ ¸ÀĤÃvÁ ¸ÀªÀiÁ£À ¥Á®ÄzÁgÀgÁVzÁÝgÉ. ¢£ÁAPÀ
31.03.2025 gÀAzÀÄ CªÀgÀ CqsÁªÉ ¥ÀwæPÉAiÀÄÄ F PɼÀV£ÀAwzÉ :
¢£ÁAPÀ 31.03.2025 gÀAzÀÄ CqsÁªÉ ¥ÀwæPÉ
ºÉÆuÉUÁjPÉUÀ¼ÀÄ D¹ÛUÀ¼ÀÄ
¸ÁºÀÄPÁgÀgÀÄ 40,000 ¨ÁåAQ£À°è£À £ÀUÀzÀÄ 45,000
PÉÆqÀvÀPÀÌ ºÀÄArUÀ¼ÀÄ 20,000 ¸Á®UÁgÀgÀÄ 35,000
ªÀ¤vÁ½AzÀ ¸Á® 25,000 §gÀvÀPÀÌ ºÀÄArUÀ¼ÀÄ 15,000
¯Á¨sÀ ªÀÄvÀÄÛ £ÀµÀÖ SÁvÉ 30,000 PÀA¥ÀÆålgÀÄUÀ¼ÀÄ 30,000
§AqÀªÁ¼ÀUÀ¼ÀÄ : AiÀÄAvÉÆæÃ¥ÀPÀgÀtUÀ¼ÀÄ 50,000
C¤vÁ 60,000 ¨sÀÆ«Ä 70,000
¸ÀĤÃvÁ 70,000
2,45,000 2,45,000
Page 9
ªÉÄð£À ¢£ÁAPÀzÀAzÀÄ ¸ÀA¸ÉÜAiÀÄ£ÀÄß «¸Àfð¸À¯ÁVzÀÄÝ, PɼÀV£À ªÀiÁ»w
®¨sÀå«zÉ :
a) D¹ÛUÀ¼ÀÄ PɼÀV£ÀAvÉ «¯ÉêÁjAiÀiÁzÀªÀÅ :
¸Á®UÁgÀgÀÄ 30,000 ;
§gÀvÀPÀÌ ºÀÄArUÀ¼ÀÄ 12,000 ;
PÀA¥ÀÆålgÀÄUÀ¼ÀÄ 25,000 ;
AiÀÄAvÉÆæÃ¥ÀPÀgÀtUÀ¼ÀÄ 45,000 ;
¨sÀÆ«Ä 85,000 ; ªÀÄvÀÄÛ
zÁR¯ÁUÀzÀ ºÀÆrPÉ 3,000.
b) ºÉÆuÉUÁjPÉUÀ¼À£ÀÄß ¥ÀÆwðAiÀiÁV ¥ÁªÀw¹zÉ.
c) «¸Àdð£Á ªÉZÀÑ 6,000 DVzÉ.
vÀAiÀiÁj¹ :
i) «¯ÉêÁj SÁvÉ,
ii) ¥Á®ÄzÁgÀgÀ §AqÀªÁ¼À SÁvÉUÀ¼ÀÄ ªÀÄvÀÄÛ
iii) ¨ÁåAPÀÄ SÁvÉ.
29) ¸ÀĦæêÀiï PÀA¥À¤ ¤AiÀÄ«ÄvÀ EªÀgÀÄ 100 ªÀÄÄR¨É¯ÉAiÀÄ
10,000 FQén ±ÉÃgÀÄUÀ¼À£ÀÄß ¥Àæw ±ÉÃjUÉ ¦æëÄAiÀÄA 10 gÀAvÉ ©qÀÄUÀqÉ
ªÀiÁrzÀgÀÄ. ºÀt ¥ÁªÀwAiÀÄÄ F PɼÀV£ÀAwzÉ.
20 Cfð ºÀt
50 ºÀAaPÉ ºÀt (¦æëÄAiÀÄA ¸ÉÃj)
40 ¥ÀæxÀªÀÄ ºÁUÀÆ CAwªÀÄ PÀgÉ ºÀt.
Page 10
J¯Áè ±ÉÃgÀÄUÀ¼ÀÄ ªÀAwUÉAiÀiÁVzÀÄÝ, 500 ±ÉÃgÀÄUÀ¼À ªÉÄð£À ¥ÀæxÀªÀÄ ªÀÄvÀÄÛ
CAwªÀÄ PÀgÉ ºÀt ºÉÆgÀvÀÄ¥Àr¹, G½zɯÁè ºÀt ¹éÃPÀj¸À¯ÁVzÉ.
¤zÉÃð±ÀPÀgÀÄ F ±ÉÃgÀÄUÀ¼À£ÀÄß ªÀÄÄlÄÖUÉÆÃ®Ä ºÁQPÉÆAqÀÄ, ¥Àæw ±ÉÃjUÉ
80 gÀAvÉ ¥ÀÆtð ¥ÁªÀw¹zÀ ±ÉÃgÀÄUÀ¼ÉAzÀÄ ªÀÄgÀÄ ©qÀÄUÀqÉ
ªÀiÁrgÀÄvÁÛgÉ.
±ÉÃgÀÄUÀ¼À ©qÀÄUÀqÉ, ªÀÄÄlÄÖUÉÆÃ®Ä ºÁUÀÆ ªÀÄgÀÄ ©qÀÄUÀqÉUÉ
¸ÀA§A¢ü¹zÀAvÉ CªÀ±ÀåPÀ gÉÆÃdÄ zÁR¯ÉUÀ¼À£ÀÄß §gɬÄj.
30) CwæzÀvÀÛ PÀA¥À¤ ¤AiÀÄ«ÄvÀ EªÀgÀÄ vÀ¯Á 100 ªÀÄÄR¨É¯ÉAiÀÄ 10,000,
10% ¸Á®¥ÀvÀæUÀ¼À£ÀÄß ¢£ÁAPÀ 01.04.2024 gÀAzÀÄ ±ÉÃPÀqÁ 10 gÀ
¸ÉÆÃr¨É¯ÉAiÀÄ°è ¤ÃrzÉ ªÀÄvÀÄÛ ±ÉÃPÀqÁ 10 gÀ ¦æëÄAiÀÄA£À°è «ªÉÆÃZÀ£É
ªÀiÁqÀÄvÀÛzÉ.
§rØAiÀÄ£ÀÄß ¸É¥ÉÖA§gï 30 ªÀÄvÀÄÛ ªÀiÁZïð 31 gÀAzÀÄ CzsÀðªÁ¶ðPÀªÁV
¥ÁªÀw¸À¯ÁUÀÄvÀÛzÉ JAzÀÄ H»¹, ¸Á®¥ÀvÀæUÀ¼À ¤ÃrPÉ ºÁUÀÆ
¸Á®¥ÀvÀæUÀ¼À ªÉÄð£À §rØUÉ ¸ÀA§A¢ü¹zÀAvÉ ¢£ÁAPÀ 31.03.2025 PÉÌ
PÉÆ£ÉUÉƼÀÄîªÀ CªÀ¢üUÉ gÉÆÃdÄ zÁR¯ÉUÀ¼À£ÀÄß §gɬÄj, ªÀÄÆ®zÀ°è
PÀrvÀUÉƽ¹zÀ vÉjUÉ ±ÉÃPÀqÁ 10 gÀ¶ÖzÉ.
31) ¸À£ï¸ÁÖgï PÀA¥À¤ ¤AiÀÄ«ÄvÀgÀªÀgÀ 31.03.2024 ªÀÄvÀÄÛ 31.03.2025 gÀ
CqsÁªÉ ¥ÀwæPÉUÀ½AzÀ, vÀÄ®£ÁvÀäPÀ CqsÁªÉ ¥ÀwæPÉAiÀÄ£ÀÄß vÀAiÀiÁj¹.
¢£ÁAPÀ 31.03.2024 ªÀÄvÀÄÛ 31.03.2025 gÀ CqsÁªÉ ¥ÀwæPÉ
«ªÀgÀUÀ¼ÀÄ 31.03.2024 31.03.2025
I. FQén ªÀÄvÀÄÛ ºÉÆuÉUÁjPÉUÀ¼ÀÄ :
1. ±ÉÃgÀÄzÁgÀgÀ ¤¢üUÀ¼ÀÄ :
a) ±ÉÃgÀÄ §AqÀªÁ¼À 5,00,000 7,50,000
b) «ÄøÀ®Ä ªÀÄvÀÄÛ G½PÉ ¯Á¨sÀ 1,00,000 1,20,000
Page 11
«ªÀgÀUÀ¼ÀÄ 31.03.2024 31.03.2025
2. ZÁ°ÛAiÉÄÃvÀgÀ ºÉÆuÉUÁjPÉUÀ¼ÀÄ :
¢ÃWÁðªÀ¢ü ¸Á®UÀ¼ÀÄ 3,00,000 4,00,000
3. ZÁ°Û ºÉÆuÉUÁjPÉUÀ¼ÀÄ :
ªÁå¥Áj PÉÆqÀvÀPÀ̪ÀÅUÀ¼ÀÄ 1,50,000 1,80,000
MlÄÖ 10,50,000 14,50,000
II. D¹ÛUÀ¼ÀÄ :
1. ZÁ°ÛAiÉÄÃvÀgÀ D¹ÛUÀ¼ÀÄ :
a) ¹ÜgÀ D¹ÛUÀ¼ÀÄ :
i) UÉÆÃZÀgÀ D¹ÛUÀ¼ÀÄ 4,00,000 7,00,000
ii) CUÉÆÃZÀgÀ D¹ÛUÀ¼ÀÄ 2,00,000 2,50,000
b) ¢ÃWÁðªÀ¢ü ºÀÆrPÉUÀ¼ÀÄ 1,50,000 1,20,000
2. ZÁ°Û D¹ÛUÀ¼ÀÄ :
a) zÁ¸ÁÛ£ÀÄUÀ¼ÀÄ 80,000 1,00,000
b) ªÁå¥Áj §gÀvÀPÀ̪ÀÅUÀ¼ÀÄ 1,20,000 2,00,000
c) £ÀUÀzÀÄ ªÀÄvÀÄÛ £ÀUÀzÀÄ ¸ÀªÀiÁ£ÀPÀUÀ¼ÀÄ 1,00,000 80,000
MlÄÖ 10,50,000 14,50,000
Page 12
32) PɼÀV£À «ªÀgÀUÀ½AzÀ, PɼÀPÀAqÀ C£ÀÄ¥ÁvÀUÀ¼À£ÀÄß PÀAqÀÄ»r¬Äj.
a) ZÁ°Û C£ÀÄ¥ÁvÀ,
b) ¸Á®-vÉÆqÀV¹zÀ §AqÀªÁ¼À C£ÀÄ¥ÁvÀ,
c) ªÁå¥Áj §gÀvÀPÀ̪ÀÅUÀ¼À DªÀvÀð£À C£ÀÄ¥ÁvÀ,
d) ªÁå¥Áj PÉÆqÀvÀPÀ̪ÀÅUÀ¼À DªÀvÀð£À C£ÀÄ¥ÁvÀ,
e) PÁAiÀiÁðvÀäPÀ C£ÀÄ¥ÁvÀ ªÀÄvÀÄÛ
f) ¤ªÀé¼À ¯Á¨sÀzÀ C£ÀÄ¥ÁvÀ.
«ªÀgÀUÀ¼ÀÄ
PÁAiÀiÁðZÀgÀuÉUÀ½AzÁzÀ PÀAzÁAiÀÄ/DzÁAiÀÄ 5,00,000
¸ÀÆÜ® ¯Á¨sÀ 1,00,000
zÁ¸ÁÛ£ÀÄ 75,000
PÁAiÀiÁðZÀgÀuÉUÀ½AzÁzÀ ¤ªÀé¼À GzÀÝj PÀAzÁAiÀÄ 3,00,000
ªÁå¥Áj §gÀvÀPÀ̪ÀÅUÀ¼ÀÄ 75,000
¤ªÀé¼À GzÀÝj RjâUÀ¼ÀÄ 2,50,000
ªÁå¥Áj PÉÆqÀvÀPÀ̪ÀÅUÀ¼ÀÄ 1,25,000
PÁAiÀiÁðvÀäPÀ RZÀÄðUÀ¼ÀÄ 50,000
¤ªÀé¼À ¯Á¨sÀ 50,000
¸Á®¥ÀvÀæUÀ¼ÀÄ 1,00,000
±ÉÃgÀÄ §AqÀªÁ¼À 2,00,000
———————
Page 13
(English Version)
Instructions : 1. The question paper contains four parts A, B, C and D.
PART – ‘A’ contains of four sections I, II, III, and IV.
2. Provide working notes wherever necessary.
3. 15 minutes extra has been allotted for candidates to read
the questions.
4. Figures in the right hand margin indicate full marks.
5. For PART – ‘A’ questions, only the first written answers
will be considered for evaluation.
PART – A
I. Choose the correct answer from the choices given : (5 × 1 = 5)
1) In order to form a partnership, there should be atleast :
a) One person b) Two people
c) Seven people d) Fifty people
2) A, B and C are partners sharing profits in the ratio of 5 : 3 : 2. If C retires,
the New Profit Sharing Ratio between A and B will be :
a) 3:2 b) 5:3
c) 5:2 d) 1:1
Page 14
3) Unrecorded liabilities, when paid are shown in
a) Debit side of Realisation A/c
b) Debit side of Bank A/c
c) Credit side of Realisation A/c
d) Debit side of Cash A/c
4) Issued capital is a part of :
a) Reserve capital b) Unissued capital
c) Authorised capital d) Subscribed capital
5) Following is an extraordinary item :
a) Salary paid b) Tax paid
c) Rent paid d) Loss due to theft
II. Fill in the blanks by choosing the appropriate answers from those given in the
bracket : (5 × 1 = 5)
[Cash/Bank, Vertical, Twelve, Agreement, Sacrificing, Twenty]
6) Partnership comes into existence as a result of __________ among the
partners.
7) Old Ratio – New Ratio = __________ Ratio.
8) On dissolution of a firm, Partner’s Loan Account is transferred to
__________ Account.
9) Loans which are repayable within __________ months, are called as
short-term borrowings.
10) Common Size Statement is also known as __________ analysis.
Page 15
III. Match the following : (5 × 1 = 5)
11) A B
a) Valuation of goodwill i) Acknowledgement of debt
b) Debentures ii) Earnings per share
c) Revenue from operations iii) Inflows and Outflows of cash
d) Profitability Ratio iv) Average profit method
e) Cash flow statement v) Sales
vi) Financial position
IV. Answer the following questions in 1 word or 1 sentence each : (5 × 1 = 5)
12) Profit or loss on revaluation is transferred to all partners’ capital accounts
in case of retirement of a partner. [State True/False]
13) State any one type of shares.
14) What do you mean by Redemption of debentures?
15) State any one user of Financial Statement Analysis.
16) Expand R.O.I.
PART – B
V. Answer any three questions. Each question carries 2 marks : (3 × 2 = 6)
17) State any two differences between fixed capital method and fluctuating
capital method.
18) Mention any two modes of disposal of amount due to retiring partner.
Page 16
19) Give the meaning of over subscription.
20) Name the two types of financial statements.
21) Write any two examples for financing activities.
PART – C
VI. Answer any three questions. Each question carries 6 marks : (3 × 6 = 18)
22) Ravi and Kiran commenced partnership business on 01.04.2024 with
capitals of 1,50,000 and 1,00,000 respectively. Their profit sharing
ratio is 3 : 2 respectively.
They earned a profit of 50,000 for the year, before allowing :
a) Interest on capital at 10% per annum.
b) Interest on drawings : Ravi 4,000 and Kiran 2,000.
c) Commission payable to Ravi 3,000 per annum.
d) Salary payable to Kiran 8,000 per annum.
Prepare Profit and Loss Appropriation Account for the year ended
31.03.2025.
Page 17
23) Geetha, Latha and Sangeetha are partners sharing profits and losses in
the ratio of 5 : 3 : 2 respectively. Latha retires from the firm. Geetha and
Sangeetha decided to share future profits in the ratio of 3 : 2.
Calculate Gaining Ratio of Geetha and Sangeetha.
24) Anil, Vishal and Sunil are partners sharing profits and losses in the ratio
of 4 : 3 : 3. Their capitals on 01.04.2025 are 1,00,000, 80,000 and
50,000 respectively.
Vishal died on 31.12.2025. The partnership deed provides the following :
a) Interest on capital at 12% per annum.
b) Salary to Vishal 2,000 per month.
c) Vishal’s share of goodwill 14,000 [as per A.S. – 26].
d) Vishal’s share of accrued profit upto the date of death, based on
previous year profit.
Firm’s previous year profit was 36,000.
Prepare Vishal’s Executors Account.
25) From the following particulars, prepare statement of profit and loss for the
year ended 31.03.2025 as per Schedule III of Companies Act, 2013 :
Particulars
Revenue from operations 8,00,000
Purchases 4,00,000
Salaries 1,00,000
Finance costs 30,000
Depreciation 20,000
Rent 15,000
Administrative expenses 35,000
Income Tax 60,000
Page 18
26) LG Company Limited earned a net profit of 7,00,000 for the year ended
31.03.2025. Depreciation for the year is 1,50,000. There was a profit of
60,000 on assets sold which was transferred to statement of profit and
loss.
Trade receivables decreased during the year by 55,000 and
trade payables also decreased by 45,000.
Compute cash flow from operating activities by indirect method.
PART – D
VII. Answer any three questions. Each question carries 12 marks : (3 × 12 = 36)
27) Govind and Sudeep are partners sharing profits and losses in the ratio of
3 : 1 respectively. Their Balance sheet as on 31.03.2025 is as follows :
Balance Sheet as on 31.03.2025
Liabilities Assets
Creditors 45,000 Cash 16,000
Bills payable 25,000 Debtors 40,000
General Reserve 20,000 Stock 34,000
Capitals : Furniture 20,000
Govind 90,000 Machinery 30,000
Sudeep 40,000 Building 80,000
2,20,000 2,20,000
On 01.04.2025, they admitted Tarun into partnership on following terms :
a) Tarun should bring in 30,000 as capital for 1/5th share and
10,000 towards goodwill [As per A.S. – 26].
b) Goodwill amount is withdrawn by old partners.
c) Depreciate furniture at 5%.
d) Appreciate building value by 10%.
e) Machinery revalued at 27,000.
Prepare :
i) Revaluation Account,
ii) Partners’ Capital Accounts and
iii) New Balance Sheet of firm on 01.04.2025.
Page 19
28) Anitha and Sunitha are equal partners. Their Balance Sheet on
31.03.2025 is as under :
Balance Sheet as on 31.03.2025
Liabilities Assets
Creditors 40,000Cash at Bank 45,000
Bills Payable 20,000Debtors 35,000
Vanitha’s Loan 25,000Bills Receivable 15,000
Profit and Loss A/c 30,000Computers 30,000
Capitals : Machinery 50,000
Anitha 60,000 Land 70,000
Sunitha 70,000
2,45,000 2,45,000
On the above date, the firm is dissolved and following information is
available :
a) Assets realised as follows :
Debtors 30,000 ;
Bills Receivable 12,000 ;
Computers 25,000 ;
Machinery 45,000 ;
Land 85,000 ; and
Unrecorded investment 3,000
b) Liabilities are paid in full.
c) Cost of dissolution amounted to 6,000.
Prepare :
i) Realisation Account,
ii) Partners’ Capital Accounts and
iii) Bank Account.
Page 20
29) Supreme Company Limited issued 10,000 equity shares of 100 each at
a premium of 10 per share. The amount payable is as follows :
On application 20
On allotment 50 (including premium)
On first and final call 40.
All the shares were subscribed and money duly received except the
first and final call on 500 shares.
The directors forfeited these shares and re-issued them as fully paid-up at
80 per share.
Pass the necessary journal entries regarding issue, forfeiture and re-issue
of shares.
30) Atridatta Company Limited issued 10,000, 10% debentures of 100 each
on 01.04.2024 at a discount of 10% and redeemable at a premium of
10%.
Pass journal entries relating to the issue of debentures and debenture
interest for the period ending 31.03.2025 assuming that interest is paid
half yearly on 30th September and 31st March, tax deducted at source is
10%.
31) From the following Balance sheets of Sunstar Company Limited on
31.03.2024 and 31.03.2025, prepare Comparative Balance sheet :
Balance sheets as on 31.03.2024 and 31.03.2025
Particulars 31.03.2024 31.03.2025
I. Equity and Liabilities :
1. Shareholders Funds :
a) Share capital 5,00,000 7,50,000
b) Reserves and Surplus 1,00,000 1,20,000
Page 21
Particulars 31.03.2024 31.03.2025
2. Non-Current Liabilities :
Long-term Borrowings 3,00,000 4,00,000
3. Current Liabilities :
Trade payables 1,50,000 1,80,000
Total 10,50,000 14,50,000
II. Assets :
1. Non-current Assets :
a) Fixed Assets :
i) Tangible Assets 4,00,000 7,00,000
ii) Intangible Assets 2,00,000 2,50,000
b) Long-term Investments 1,50,000 1,20,000
2. Current Assets :
a) Inventories 80,000 1,00,000
b) Trade Receivables 1,20,000 2,00,000
c) Cash and Cash equivalents 1,00,000 80,000
Total 10,50,000 14,50,000
32) From the following particulars, calculate :
a) Current Ratio,
b) Debt to Capital Employed Ratio,
c) Trade Receivables Turnover Ratio,
d) Trade Payables Turnover Ratio,
e) Operating Ratio and
f) Net Profit Ratio.
Page 22
Particulars
Revenue from operations 5,00,000
Gross Profit 1,00,000
Inventory 75,000
Net credit revenue from operations 3,00,000
Trade receivables 75,000
Net credit purchases 2,50,000
Trade payables 1,25,000
Operating expenses 50,000
Net profit 50,000
Debentures 1,00,000
Share capital 2,00,000
–––––––––––––––
Page 23
Page 24
Document Details
| Board / Org | Karnataka Board |
| Exam | Class 12 |
| Type | Question Paper |
| Pages | 24 |
| Language | english |
| Updated | 24 Sep 2026 |