PSEB 12th Class Syllabus 2027 Accountancy
Finished viewing? Save it for later —
Download PSEB 12th Class Syllabus 2027 Accountancy (PDF · 5 pages)About PSEB 12th Class Syllabus 2027 Accountancy
PSEB 12th Class Syllabus 2027 Accountancy is available here for free download. Published by Punjab Board for Class 12, this syllabus can be viewed online or downloaded as a PDF (5 pages). Candidates preparing for Class 12 can use PSEB 12th Class Syllabus 2027 Accountancy to understand the exam pattern, the type of questions asked, and the overall difficulty level.
Frequently Asked Questions
How can I download PSEB 12th Class Syllabus 2027 Accountancy?
Open this page and click the Download button to save PSEB 12th Class Syllabus 2027 Accountancy as a PDF. It is completely free on AglaSem Docs.
Is PSEB 12th Class Syllabus 2027 Accountancy free to download?
Yes. PSEB 12th Class Syllabus 2027 Accountancy can be viewed online and downloaded as a PDF free of cost on AglaSem Docs.
How many pages does PSEB 12th Class Syllabus 2027 Accountancy have?
PSEB 12th Class Syllabus 2027 Accountancy contains 5 pages, which you can read online or download together as a single PDF.
Where can I find more Class 12 study material?
You can find more Class 12 question papers, sample papers, syllabus, and answer keys on AglaSem Docs.
PSEB 12th Class Syllabus 2027 Accountancy – Text
Read the full text of this syllabus below — useful to quickly search, copy and reference the content online without downloading the PDF.
📄 View text version (6 pages)
Page 1
PSEB 12th Class
Syllabus 2027
Accountacy
EXAM YEAR TYPE
Punjab Class 12 2027 Syllabus
Notes · Sample Papers · Previous Year Papers · Mock Tests
Page 2
m .co s e mPSEB 12th Class Syllabus 2027 Accountacy
s e l a
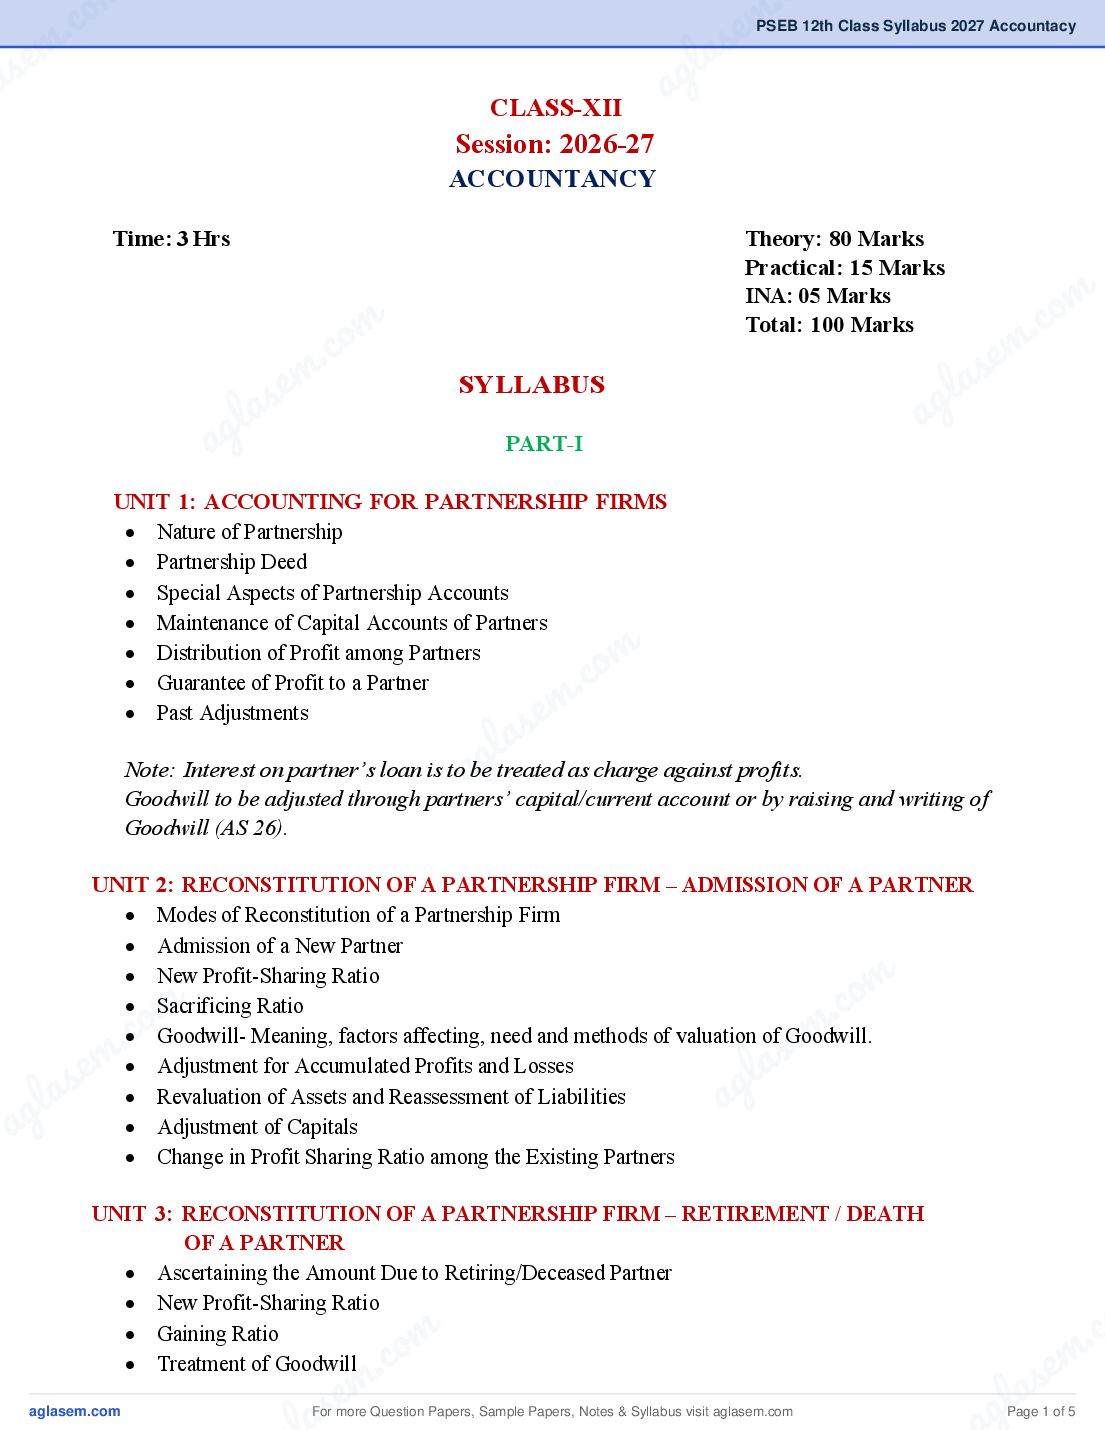
a CLASS-XII
ag
Session: 2026-27
ACCOUNTANCY
Time: 3 Hrs Theory: 80 Marks
Practical: 15 Marks
INA: 05 Marks m
om Total: 100 Marks . co
. c e m
e m SYLLABUS l as
l as ag
ag PART-I
UNIT 1: ACCOUNTING FOR PARTNERSHIP FIRMS
Nature of Partnership
Partnership Deed
Special Aspects of Partnership Accounts
Maintenance of Capital Accounts of Partners
Distribution of Profit among Partners m
Guarantee of Profit to a Partner
m .co
Past Adjustments
s e
l a
gtreated as charge against profits.
Note: Interest on partner’s loan is toabe
Goodwill to be adjusted through partners’ capital/current account or by raising and writing of
Goodwill (AS 26).
UNIT 2: RECONSTITUTION OF A PARTNERSHIP FIRM – ADMISSION OF A PARTNER
Modes of Reconstitution of a Partnership Firm
Admission of a New Partner
New Profit-Sharing Ratio
m
m
Sacrificing Ratio .co
m .co
Goodwill- Meaning, factors affecting, need and methods of valuation of Goodwill.
s e m
s e Adjustment for Accumulated Profits and Losses
g la
g la Revaluation of Assets and Reassessment of Liabilities a
a Adjustment of Capitals
Change in Profit Sharing Ratio among the Existing Partners
UNIT 3: RECONSTITUTION OF A PARTNERSHIP FIRM – RETIREMENT / DEATH
OF A PARTNER
Ascertaining the Amount Due to Retiring/Deceased Partner
New Profit-Sharing Ratio
Gaining Ratio m . c
Treatment of Goodwill c. o s e m
s em
Page 1 of 5
Page 3
Adjustment for Revaluation of Assets and Liabilities
Adjustment of Accumulated Profits and Losses
Disposal of Amount Due to Retiring Partner
Adjustment of Partners’ Capitals
Death of a Partner
UNIT 4: DISSOLUTION OF PARTNERSHIP FIRM
Dissolution of Partnership
Dissolution of a Firm
Settlement of Accounts
Accounting Treatment
Note: (i) If the realised value of tangible assets (i.e. Land & Buildings, Furniture, Stock
etc.) is not given, it should be considered as realised at book value itself.
(ii) If the realised value of intangible assets (i.e. Goodwill, Patents, Trade Marks,
Computer Software etc.) is not given, it should be considered as nil (zero value).
(iii) In case, realisation expenses are borne by a partner, clear indication should be given
regarding the payment thereof.
UNIT-5: ACCOUNTING FOR SHARE CAPITAL
Features of a Company
Kinds of Companies
Share Capital of a Company
Nature and Classes of Shares
Issue of Shares
Accounting Treatment
Forfeiture of Shares
Note: The term “Securities Premium Reserve Account” has been changed and now it is termed
only “Securities Premium”.
UNIT 6: ISSUE OF DEBENTURES
Meaning of Debentures
Distinction between Shares and Debentures
Types of Debentures
Issue of Debentures
Over Subscription
Issue of Debentures for Consideration other than Cash
Issue of Debentures as a Collateral Security
Terms of Issue of Debentures
Interest on Debentures
Writing off Discount/Loss on Issue of Debentures
Note: Discount or loss on issue of debentures to be written off in the year debentures are allotted
from Security Premium (if it exists) and then from Statement of Profit and Loss as Financial Cost
For more Question Papers, Sample Papers, Notes & Syllabus visit Page 2 of 5
Page 4
m .co s e mPSEB 12th Class Syllabus 2027 Accountacy
s e l a
a (AS 16).
ag
Capital Reserve cannot be used for writing off Discount/Loss on Issue of Debentures.
NOTE: Students may choose only one Part from Part II and Part III.
PART -II
m
om
UNIT 7: FINANCIAL STATEMENTS OF A COMPANY
. co
. c
Meaning of Financial Statements
e m
e m
Nature of Financial Statements
l as
l as
Objectives of Financial Statements
ag
ag
Types of Financial Statements
Uses and Importance of Financial Statements
Limitations of Financial Statements
UNIT 8: ANALYSIS OF FINANCIAL STATEMENTS
Meaning of Analysis of Financial Statements
Significance of Analysis of Financial Statements
Objectives of Analysis of Financial Statements
m
Tools of Analysis of Financial Statements
m .co
Comparative Statements
s e
Common Size Statement
l a
Limitations of Financial Analysis ag
UNIT 9: ACCOUNTING RATIOS
Meaning of Accounting Ratios
Objectives of Ratio Analysis
Advantages of Ratio Analysis
Limitations of Ratio Analysis
Types of Ratios
m
m
Liquidity Ratios
.co
.co
Solvency Ratios
s e m
s em Activity (or Turnover) Ratio
g la
g la Profitability Ratios a
a UNIT 10: CASH FLOW STATEMENT
Objectives of Cash Flow Statement
Benefits of Cash Flow Statement
Cash and Cash Equivalents
Cash Flows
Classification of Activities for the Preparation of Cash Flow Statement
m
Ascertaining Cash Flow from Operating Activities . c
c. o
Ascertainment of Cash Flow from Investing and Financing Activities
s e m
s em
Page 3 of 5
Page 5
Preparation of Cash Flow Statement
Note: Previous years’ Proposed dividend to be given effect, as per prescribed in AS-4, Events
occurring after the balance sheet date. Current years’ proposed dividend will be accounted for
in the next year after it is declared by the shareholders.
OR
PART-III
.
UNIT 7: OVERVIEW OF COMPUTERISED ACCOUNTING SYSTEM
Computerised Accounting System
Components of CAS
Salient Features of CAS
Grouping of Accounts
Using Software of CAS
Advantages of CAS
Limitations of CAS
Accounting Information System (AIS)
UNIT 8: SPREADSHEET
Basic Concepts of Spreadsheet
Data Entry, Text Management and Cell Formatting
Data Formatting
Output Reports
Preparation of Reports Using Pivot Table
Common Errors (Messages) in Spreadsheet
UNIT 9: USE OF SPREADSHEET IN BUSINESS APPLICATIONS
Payroll Accounting
Asset Accounting
Loan Repayment Schedule
UNIT 10: GRAPHS AND CHARTS FOR BUSINESS DATA
Graphs and Charts
Basics Steps for Graphs/Charts/Diagrams Using Excel
Advantages in Using Graph/Chart
*****
For more Question Papers, Sample Papers, Notes & Syllabus visit Page 4 of 5
Page 6
m .co s e mPSEB 12th Class Syllabus 2027 Accountacy
s e l a
a ag
Practical work
Practical work for those students who choose Part-II of the syllabus.
Time: 1 ½ Hours Max Marks 15
1. The syllabus of practical work is same as prescribed for the theory paper of Part II.
m
2. Practical Note book will consist of at least one comprehensive project and some
om . co
c
short answer questions based on the prescribed syllabus.
. e m
3.
em
Division of Marks:
l as
a s
l Note Book ag
1
2
g
Project
aTotal five questions of 3 marks each
3 marks
(3×3) = 9 marks
will be set. The students are
required to attempt any three
3 Viva Voce 3 marks
Practical for those students who choose Part-III of the syllabus.
m
m .co
Time: 1 ½ Hours
s e Max Marks: 15
1.
l a
The syllabus of practical work is same as prescribed for the theory paper of part-III.
2.
ag
Practical Note book will consist of the entire practical performed in the
computer laboratory based on the prescribed syllabus.
3. Division of Marks:
1 Practical Note Book 3 marks
2 The students are required to perform any three (3×3) = 9 marks
Practicals out of the given Five of 3 marks each.
3 Viva Voce 3 marks
o m
m c
. Marks: 05
c. o of Marks for internal assessment (INA):
Division
s
m
Max
e
m
e As per instructions issued by Punjab School Education Board. gla
las a
ag
*****
m . c
c. o s e m
s em
Page 5 of 5
Document Details
| Board / Org | Punjab Board |
| Exam | Class 12 |
| Type | Syllabus |
| Pages | 5 |
| Updated | 04 Nov 2026 |