Goa Board Class 12 Syllabus 2027 Cost Accounting & Taxation
Finished viewing? Save it for later —
Download Goa Board Class 12 Syllabus 2027 Cost Accounting & Taxation (PDF · 7 pages)About Goa Board Class 12 Syllabus 2027 Cost Accounting & Taxation
Goa Board Class 12 Syllabus 2027 Cost Accounting & Taxation is available here for free download. Published by Goa Board for Class 12, this syllabus can be viewed online or downloaded as a PDF (7 pages). Candidates preparing for Class 12 can use Goa Board Class 12 Syllabus 2027 Cost Accounting & Taxation to understand the exam pattern, the type of questions asked, and the overall difficulty level.
Frequently Asked Questions
How can I download Goa Board Class 12 Syllabus 2027 Cost Accounting & Taxation?
Open this page and click the Download button to save Goa Board Class 12 Syllabus 2027 Cost Accounting & Taxation as a PDF. It is completely free on AglaSem Docs.
Is Goa Board Class 12 Syllabus 2027 Cost Accounting & Taxation free to download?
Yes. Goa Board Class 12 Syllabus 2027 Cost Accounting & Taxation can be viewed online and downloaded as a PDF free of cost on AglaSem Docs.
How many pages does Goa Board Class 12 Syllabus 2027 Cost Accounting & Taxation have?
Goa Board Class 12 Syllabus 2027 Cost Accounting & Taxation contains 7 pages, which you can read online or download together as a single PDF.
Where can I find more Class 12 study material?
You can find more Class 12 question papers, sample papers, syllabus, and answer keys on AglaSem Docs.
Goa Board Class 12 Syllabus 2027 Cost Accounting & Taxation – Text
Read the full text of this syllabus below — useful to quickly search, copy and reference the content online without downloading the PDF.
📄 View text version (8 pages)
Page 1
Goa Board Class 12
Syllabus 2027 Cost
Accounting & Taxation
EXAM YEAR TYPE
Goa Class 12 2027 Syllabus
Notes · Sample Papers · Previous Year Papers · Mock Tests
Page 2
. s e
em l a
as a g
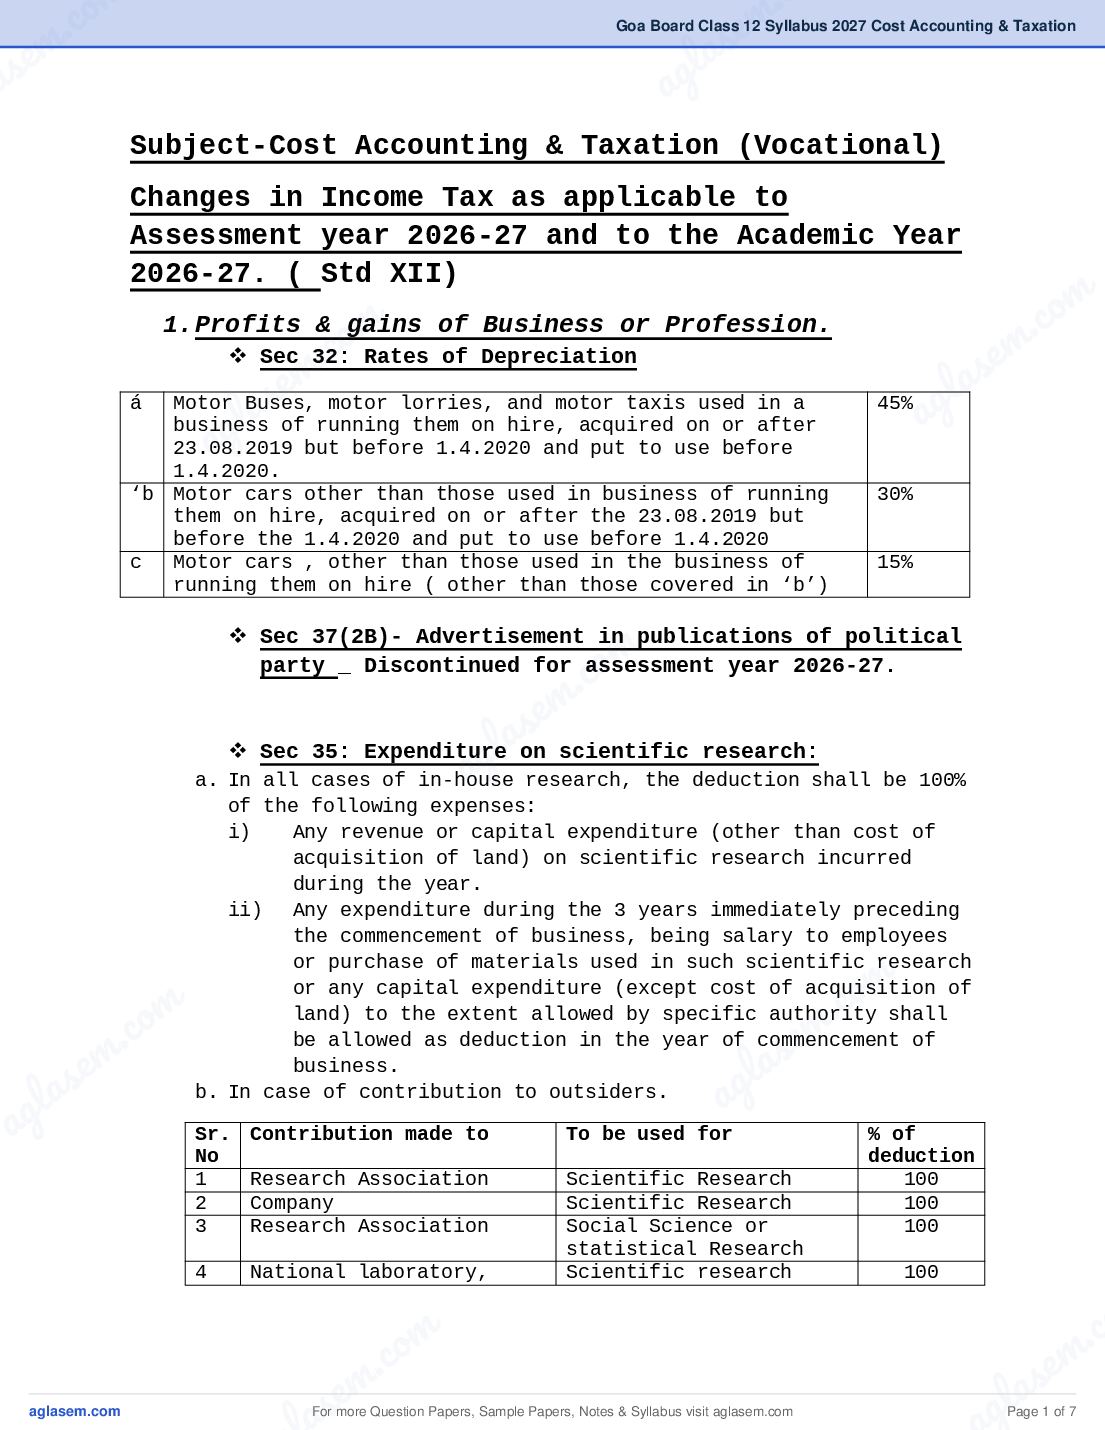
Subject-Cost Accounting & Taxation (Vocational)
Changes in Income Tax as applicable to
Assessment year 2026-27 and to the Academic Year
2026-27. ( Std XII)
m
om . co
c m
1.Profits & gains of Business or Profession.
m . s e
a
Sec 32: Rates of Depreciation
se 45% g l
l a a
ag
á Motor Buses, motor lorries, and motor taxis used in a
business of running them on hire, acquired on or after
23.08.2019 but before 1.4.2020 and put to use before
1.4.2020.
‘b Motor cars other than those used in business of running 30%
them on hire, acquired on or after the 23.08.2019 but
before the 1.4.2020 and put to use before 1.4.2020
c Motor cars , other than those used in the business of 15%
running them on hire ( other than those covered in ‘b’)
m
Sec 37(2B)- Advertisement in publications of political
.
party _ Discontinued for assessment year 2026-27.
co
s em
g l a
a
Sec 35: Expenditure on scientific research:
a. In all cases of in-house research, the deduction shall be 100%
of the following expenses:
i) Any revenue or capital expenditure (other than cost of
acquisition of land) on scientific research incurred
during the year.
ii) Any expenditure during the 3 years immediately preceding
the commencement of business, being salary to employees
m
or purchase of materials used in such scientific research
m
or any capital expenditure (except cost of acquisition of
c. o
c. o e m
land) to the extent allowed by specific authority shall
em
be allowed as deduction in the year of commencement of
la s
las business.
ag
g
b. In case of contribution to outsiders.
a Sr. Contribution made to To be used for % of
No deduction
1 Research Association Scientific Research 100
2 Company Scientific Research 100
3 Research Association Social Science or 100
statistical Research
4 National laboratory, Scientific research 100
m . c
c. o s e m
se
g l
Page 1 of 7
Page 3
Institute of Technology
or Specified person
Section 44AB – Audit of Accounts
The category of taxpayers who are required to get their books of
accounts audited on compulsory basis:
(a) Persons carrying on business
i) In case of person carrying on business where the total
sales, turnover or gross receipts exceeds Rs. 1 crore in
the previous year.
ii) The above limit of Rs. 1 crore will be 10 crores, where:
The aggregate of all amounts received including the
amount received for sales, turnover or gross receipts
during the previous year in cash, does not exceed 5%
of the said amount. And
The aggregate of all payments made including amount
incurred for expenditure in cash during the previous
year does not exceed 5% of the said amount.
(b) Person carrying on profession.
Person carrying on profession where the gross receipts exceed
50 lakhs in the previous year.
Section 44AD: Estimated business Income (small
business)
Eligible assessee:
a) A resident individual or HUF, firm except LLP.
b) The assessee carrying on business whose gross receipts or total
turnover does not exceed as follows:
a) The aggregate amount received during the year in cash, bearer
cheque, crossed cheque, crossed draft does not exceed 5% of
the total turnover or gross receipts – Rs. 3 crores.
b) In any other case – Rs. 2 crore.
Section 44ADA: Estimated Professional Income
Eligible assessee:
c) A resident individual or HUF, firm except LLP.
d) The assessee carrying on business whose gross receipts does not
exceed as follows:
For more Question Papers, Sample Papers, Notes & Syllabus visit Page 2 of 7
Page 4
. s e
em l a
as a g
c) The aggregate amount received during the year in cash, bearer
cheque, crossed cheque, crossed draft does not exceed 5% of
the total turnover or gross receipts – Rs. 75 Lakhs.
d) In any other case – Rs. 50 Lakhs.
m
om . co
2.Deductions under chapter VIA.
.c e m
m e
1. Contribution to pension scheme of the central government Sec
l a s
80CCD
l a s a g
a g
a) Deduction shall be allowed u/s 80CCD (1) in respect of amount
contributed by employee during the previous year subject to
following limits:
i) Incase of individual employee – not exceeding10% of
salary
ii) Incase of individual not being an employee – not
exceeding 20% of total income.
b) Deduction shall be allowed u/s 80CCD (2) in respect of amount
m
contributed by employer during the previous year subject to
. co
following limits:
em
iii) In case of central and state Govt employer – not
exceeding14% of salary
l a s
g
iv) In case of any other employer – not exceeding 10% of
salary.
(14% in case of NTR)
a
2. Deduction in respect of contribution to Agnipath Scheme -
Sec 80CCH
The deduction is allowed on the following conditions:
a) The assessee is an individual enrolled in the Agnipath
m
Scheme.
m c. o
b) The assessee subscribes to the Agniveer Corpus Fund.
c. o e m
c) The contribution made by an assessee to this fund is
em
deductible in the year the amount is paid or deposited –
la s
las Sec. 80CCH (1).
ag
g
d) The contribution made by the central Govt shall be
a included in the income of the assessee as salaries and the
whole amount is allowed as deduction – Sec 80CCH (2).
e) The deduction is applicable under Old and New Tax Regime.
f) The benefit is available to those Individuals who have
subscribed to this scheme on or after 1st November, 2022.
m . c
c. o s e m
se
g lPage 3 of 7
Page 5
Sec 80EEA
a. The deduction is available to an Individual
b. The assessee should not claim deduction u/s 80 EE.
c. The assessee should have taken the loan for the purpose of
acquiring the residential house property from bank, banking
institution or housing finance company.
d. The loan has been sanctioned during 1.4.2019 to 31.03.2022.
e. The stamp duty value of such property shall not exceed Rs. 45
Lakhs.
f. The assessee does not own any residential house property on
the date of sanction.
g. Sec 80EEA is in addition to the deduction u/s 24(b).
h. No deduction can be availed under any other provisions of
Income Tax Act.
i. The deduction is allowed as Rs. 150000/- or interest payable
whichever is lower.
4. Deduction in respect of purchase of electric vehicle - Sec
80EEB
a. The deduction is available to an Individual
b. The assessee has taken the loan for the purchase of electric
vehicle during 01.04.2019 to 31.03.2023.
c. The loan is sanctioned by the bank or banking institution.
d. No deduction can be availed under any other provisions of
Income Tax Act.
e. The deduction is allowed as Rs. 150000/- or interest payable
whichever is lower.
5. Deduction in respect to donations made to Political Party or
Electoral Trust. - Sec 80GGC
1. The deduction is allowed to all taxpayers.
2. The deduction is allowed for donations made to political
parties or electoral Trusts.
3. The donation can be in the form of money, cheque, draft or any
other mode of payment.
4. The limit of donation has been fixed at 10% of the gross income
in a year.
5. A receipt or acknowledgment from the political party or
electoral trust is necessary to avail this deduction.
For more Question Papers, Sample Papers, Notes & Syllabus visit Page 4 of 7
Page 6
. s e
em l a
as a g
3.Rates of Income tax, surcharge, cess, rebate etc.
Old Tax Regime:
m
om
1. The Rates of Income Tax is unchanged for;
. co
.c e m
m s
a. Individuals below the age of 60 years
se
b. Individuals above 60 years but below 80 years of age
g l a
l a a
ag
(Senior Citizen)
c. Individuals above 80 years of age ( Super senior
citizen)
2. The Rebate u/s 87A is unchanged.
3. Health and Education cess is unchanged.
4. Change in Surcharge as below:
Total Income Surcharge on Other
Dividend income, income
m
Capital gains etc
co
Upto 50 Lakhs 10% NIL
.
em
Above 50 Lakhs and upto 1 15% 10%
s
crore
Above 1 crore and upto 2
l
15%
g a 15%
a
crore
Above 2 crore and upto 15% 25%
Rs. 5 crores
Above 5 crores 15% 37%
New Tax Regime/ Alternate Tax Regime:
1. The Rates of Income Tax is as follows.
m
m
Sr Total Income Rates of Tax
c. o
c. o Upto Rs. 400000 e m
No.
em
1. NIL
la s
s ag
2
From Rs. 400001 to Rs. 800000 5%
l a
ag
3
From Rs. 800001 to Rs. 1200000 10%
4
From Rs. 1200001 to Rs. Rs. 1600000 15%
5
From Rs. 1600001 to Rs. 2000000 20%
6 From Rs. 2000001 to Rs. 2400000 25%
6 Above Rs. 2400000 30%
2. The Rebate u/s 87A:
m . c
c. o s e m
se
g l Page 5 of 7
Page 7
case the total income does not exceed Rs. 12,00,000/- .
The amount of rebate shall be 100% of income tax
payable or Rs. 60,000/- whichever is less.
Marginal Relief:
Marginal relief can be claimed when the taxable income
exceeds Rs. 12 lakhs if it is beneficial.
Method (steps)
Step Method Rs.
1 Compute the tax payable xxx
on Total income before
rebate u/s 87A
2 Compute the difference xxx
between total income and
Rs. 12 lakhs
3 Compute the difference xxx
between step I and step
II
4 If the amount of step 3 xxx
is positive the same
shall be allowed as
rebate otherwise NIL
rebate
3. Health and Education cess is unchanged.it shall be 4%
on tax payable, which is same as old tax regime.
4. Change in Surcharge as below:
Total Income Surcharge on Other
Dividend income, income
Capital gains etc
Upto 50 Lakhs NIL NIL
Above 50 Lakhs and upto 1 10% 10%
crore
For more Question Papers, Sample Papers, Notes & Syllabus visit Page 6 of 7
Page 8
. s e
em l a
as a g
Above 1 crore and upto 2 15% 15%
crore
Above 2 crore 15% 25%
The Restricted Exemptions/deductions under ATR -Sec 115
m
co
BAC (2)
1. Salaries:
.c om e m .
me l a s
s
Section 10(5) – Leave travel concession
l a
Section 10(13A) – House Rent Allowance.
a g
g
a allowance for the performance of duties of office, allowances
However, under special allowances u/s 10(14), Conveyance
to meet the cost of travel on tour or transfer is allowed as
deduction.
Section 16 (ii) – Entertainment allowance.
Section 16 (iii) – Professional tax
However Standard deduction u/s 16 (i) is allowed as deduction
m
co
to the maximum of Rs. 75,000/-. (While in old tax regime it is
.
em
Rs. 50,000/-)
2. House property:
l a s
a g
Section 24(b) – Interest on borrowed capital for housing.
3. General deductions (Chapter VIA):
No deductions are allowed except the following.
Sec 80CCD (2) – Employer’s contribution to NPS is allowed.
Sec 80CCH (2)- Central Govt Contribution to Agniveer
Corpus fund.
m
m c. o
c. o s e m
s em la
gla ag
a
m . c
c. o s e m
se
g l Page 7 of 7
Document Details
| Board / Org | Goa Board |
| Exam | Class 12 |
| Type | Syllabus |
| Pages | 7 |
| Updated | 04 Nov 2026 |