NIOS Class 10 April 2024 Question Paper Accountancy
Finished viewing? Save it for later —
Download NIOS Class 10 April 2024 Question Paper Accountancy (PDF · 20 pages)About NIOS Class 10 April 2024 Question Paper Accountancy
NIOS Class 10 April 2024 Question Paper Accountancy is available here for free download. Published by NIOS for National Institute of Open Schooling Class 10, this question paper can be viewed online or downloaded as a PDF (20 pages). Candidates preparing for National Institute of Open Schooling Class 10 can use NIOS Class 10 April 2024 Question Paper Accountancy to understand the exam pattern, the type of questions asked, and the overall difficulty level.
Frequently Asked Questions
How can I download NIOS Class 10 April 2024 Question Paper Accountancy?
Open this page and click the Download button to save NIOS Class 10 April 2024 Question Paper Accountancy as a PDF. It is completely free on AglaSem Docs.
Is NIOS Class 10 April 2024 Question Paper Accountancy free to download?
Yes. NIOS Class 10 April 2024 Question Paper Accountancy can be viewed online and downloaded as a PDF free of cost on AglaSem Docs.
How many pages does NIOS Class 10 April 2024 Question Paper Accountancy have?
NIOS Class 10 April 2024 Question Paper Accountancy contains 20 pages, which you can read online or download together as a single PDF.
Where can I find more National Institute of Open Schooling Class 10 study material?
You can find more National Institute of Open Schooling Class 10 question papers, sample papers, syllabus, and answer keys on AglaSem Docs.
NIOS Class 10 April 2024 Question Paper Accountancy – Text
Read the full text of this question paper below — useful to quickly search, copy and reference the content online without downloading the PDF.
📄 View text version (20 pages)
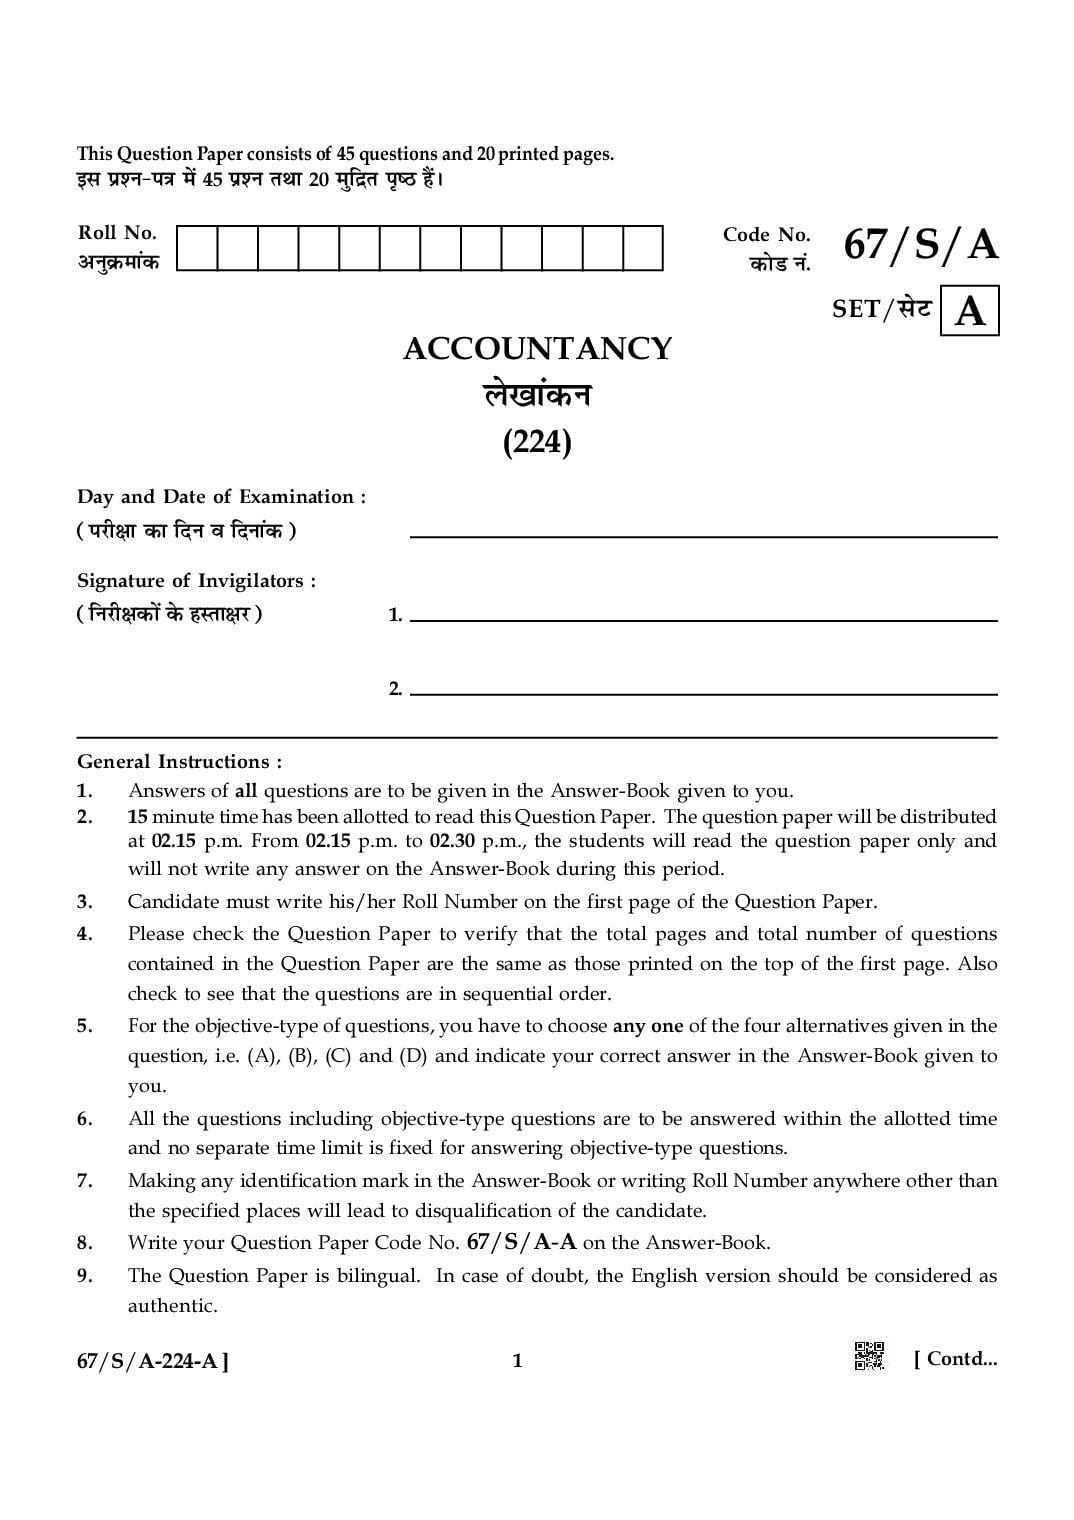
Page 1
ß‚ ¬˝‡Ÿ-¬òÊ ◊¥ 45 ¬˝‡Ÿ ÃÕÊ 20 ◊ÈÁŒ˝Ã ¬Îc∆U „Ò¥–
Roll No. Code No.
•ŸÈ∑˝§◊Ê¥∑§ ∑§Ê«U Ÿ¥.
67/S/A
SET/‚ ≈ A
ACCOUNTANCY
‹πÊ¥∑§Ÿ
(224)
Day and Date of Examination :
(¬⁄UˡÊÊ ∑§Ê ÁŒŸ fl ÁŒŸÊ¥∑§)
Signature of Invigilators :
(ÁŸ⁄UˡÊ∑§Ê¥ ∑§ „SÃÊˇÊ⁄U) 1.
2.
General Instructions :
1. Answers of all questions are to be given in the Answer-Book given to you.
2. 15 minute time has been allotted to read this Question Paper. The question paper will be distributed
at 02.15 p.m. From 02.15 p.m. to 02.30 p.m., the students will read the question paper only and
will not write any answer on the Answer-Book during this period.
3. Candidate must write his/her Roll Number on the first page of the Question Paper.
4. Please check the Question Paper to verify that the total pages and total number of questions
contained in the Question Paper are the same as those printed on the top of the first page. Also
check to see that the questions are in sequential order.
5. For the objective-type of questions, you have to choose any one of the four alternatives given in the
question, i.e. (A), (B), (C) and (D) and indicate your correct answer in the Answer-Book given to
you.
6. All the questions including objective-type questions are to be answered within the allotted time
and no separate time limit is fixed for answering objective-type questions.
7. Making any identification mark in the Answer-Book or writing Roll Number anywhere other than
the specified places will lead to disqualification of the candidate.
8. Write your Question Paper Code No. 67/S/A-A on the Answer-Book.
9. The Question Paper is bilingual. In case of doubt, the English version should be considered as
authentic.
67/S/A-224-A ] 1 [ Contd...
Page 2
1. ‚÷Ë ¬˝‡ŸÊ¥ ∑§ ©ûÊ⁄U •Ê¬∑§Ê ŒË ªÿË ©ûÊ⁄U-¬ÈÁSÃ∑§Ê ◊¥ „Ë Á‹π¥–
2. ß‚ ¬˝‡Ÿ-¬òÊ ∑§Ê ¬…∏Ÿ ∑§ Á‹∞ 15 Á◊Ÿ≈U ∑§Ê ‚◊ÿ ÁŒÿÊ ªÿÊ „Ò– ¬˝‡Ÿ-¬òÊ ∑§Ê ÁflÃ⁄UáÊ ŒÊ¬„⁄U ◊¥ 02.15 ’¡ Á∑§ÿÊ ¡Ê∞ªÊ–
02.15 ’¡ ‚ 02.30 ’¡ Ã∑§ ¿UÊòÊ ∑§fl‹ ¬˝‡Ÿ-¬òÊ ∑§Ê ¬…∏¥ª •ÊÒ⁄U ß‚ •flÁœ ∑§ ŒÊÒ⁄UÊŸ fl ©ûÊ⁄U-¬ÈÁSÃ∑§Ê ¬⁄U ∑§Ê߸ ©ûÊ⁄U Ÿ„Ë¥
Á‹π¥ª–
3. ¬⁄UˡÊÊÕ˸ ¬˝‡Ÿ-¬òÊ ∑§ §¬„‹ ¬Îc∆U ¬⁄U •¬ŸÊ •ŸÈ∑˝§◊Ê¥∑§ •fl‡ÿU Á‹π¥–
4. ∑Χ¬ÿÊ ¬˝‡Ÿ-¬òÊ ∑§Ê ¡ÊÚ°ø ‹¥ Á∑§ ¬˝‡Ÿ-¬òÊ ∑§ ∑ȧ‹ ¬Îc∆UÊ¥ ÃÕÊ ¬˝‡ŸÊ¥ ∑§Ë ©ÃŸË „Ë ‚¥ÅUÿÊ „Ò Á¡ÃŸË ¬˝Õ◊ ¬Îc∆ ∑ §‚’‚ ™§¬⁄U
¿U¬Ë „Ò– ß‚ ’Êà ∑§Ë ¡ÊÚ°ø ÷Ë ∑§⁄U ‹¥ Á∑§ ¬˝‡Ÿ ∑˝ Á◊∑§ UM§¬ ◊¥ „Ò¥–
5. flSÃÈÁŸc∆U ¬˝‡ŸÊ¥ ◊¥ •Ê¬∑§Ê øÊ⁄U Áfl∑§À¬Ê¥ (A), (B), (C) ÃÕÊ (D) ◊¥ ‚ ∑§Ê߸ ∞∑§ ©ûÊ⁄U øÈŸŸÊ „Ò ÃÕÊ ŒË ªß¸ ©ûÊ⁄U-¬ÈÁSÃ∑§Ê ◊¥
•Ê¬ ‚„Ë ©ûÊ⁄U Á‹Áπ∞–
6. flSÃÈÁŸc∆U ¬˝‡ŸÊ¥ ∑§ ‚ÊÕ-‚ÊÕ ‚÷Ë ¬˝‡ŸÊ¥ ∑§ ©ûÊ⁄U ÁŸœÊ¸Á⁄Uà •flÁœ ∑§ ÷ËÃ⁄U „Ë ŒŸ „Ò¥– flSÃÈÁŸc∆U ¬˝‡ŸÊ¥ ∑§ Á‹∞ •‹ª ‚
‚◊ÿ Ÿ„Ë¥ ÁŒÿÊ ¡Ê∞ªÊ–
7. § ©ûÊ⁄U-¬ÈÁSUÃ∑§Ê ◊¥ ¬„øÊŸ-Áøq ’ŸÊŸ •ÕflÊ ÁŸÁŒ¸c≈U SÕÊŸÊ¥ ∑§§•ÁÃÁ⁄UÄà ∑§„Ë¥ ÷Ë •ŸÈ∑˝§◊Ê¥∑§ Á‹πŸ ¬⁄U ¬⁄UˡÊÊÕ˸ ∑§Ê •ÿÊÇÿ
∆U„⁄UÊÿÊ ¡ÊÿªÊ–
8. •¬ŸË ©ûÊ⁄U-¬ÈÁSUÃ∑§Ê ¬⁄U ¬˝‡Ÿ-¬òÊ ∑§Ê ∑§Ê«U Ÿ¥. 67/S/A-A Á‹π¥–
9. ¬˝‡Ÿ-¬òÊ Ám÷Ê·Ë „Ò– ‚¥Œ„ ∑§Ë ÁSÕÁà ◊¥, •¥ª˝¡Ë ‚¥S∑§⁄UáÊ ∑§Ê ¬˝Ê◊ÊÁáÊ∑§ ◊ÊŸÊ ¡ÊŸÊ øÊÁ„∞–
67/S/A-224-A ] 2 [ Contd...
Page 3
‹πÊ¥∑§Ÿ
(224)
Time : 3 Hours ] [ Maximum Marks : 100
‚◊ÿ — 3 ÉÊá≈U ] [ ¬ÍáÊÊZ∑§ — 100
Note :
(i) This question paper consists of 45 questions in all.
(ii) All the questions are compulsory. Internal choices are given in some questions.
(iii) Marks are given against each question.
(iv) Section - A consists of
Q.No. 1 to 20 that are Multiple Choice Questions (MCQs) carrying one mark each. Select and
write the most appropriate option out of the four options given in each question. An internal
choice has been given in some of questions.
(v) Section - B consists of
Objective type questions. Q.No. 21 to 23 carry 2 marks each and Q.No. 24 to 29 carrying 4 marks
each. Attempt these questions as per the instructions given for each question.
(vi) Section - C consists of
(a) Q.No. 30 to 35 - Very Short Answer type questions carrying 2 marks each to be answered in
the range of 30 to 50 words.
(b) Q.No. 36 to 41 - Short Answer type questions carrying 3 marks each to be answered in the
range of 50 to 80 words.
(c) Q.No. 42 to 45 - Long Answer type questions carrying 5 marks each to be answered in the
range of 80 to 120 words.
ÁŸŒ¸‡Ê —
(i) ß‚ ¬˝‡Ÿ-¬òÊ ◊¥ ∑ȧ‹ 45 ¬˝‡Ÿ „Ò¥–
(ii) ‚÷Ë ¬˝‡Ÿ •ÁŸflÊÿ¸ „Ò¥– ∑ȧ¿U ¬˝‡ŸÊ¥ ◊¥ •Ê¥ÃÁ⁄U∑§ Áfl∑§À¬ ÁŒÿ ªÿ „Ò¥–
(iii) ¬˝àÿ∑§ ¬˝‡Ÿ ∑§ ‚ê◊Èπ •¥∑§ Œ‡Êʸÿ ªÿ „Ò¥–
(iv) πá«U - ∑§ ◊¥
¬˝‡Ÿ ‚¥ÅÿÊ 1 ‚ 20 Ã∑§, ¬˝àÿ∑§ ∞∑§ •¥∑§ flÊ‹, ’„ÈÁfl∑§À¬Ë ¬˝‡Ÿ „Ò¥– ¬˝àÿ∑§ ¬˝‡Ÿ ◊¥ ÁŒÿ ªÿ øÊ⁄U Áfl∑§À¬Ê¥ ◊¥ ‚ ‚flʸÁœ∑§
©¬ÿÈÄà Áfl∑§À¬ ∑§Ê øÿŸ ∑§⁄U∑§ Á‹Áπ∞– ∑ȧ¿U ¬˝‡ŸÊ¥ ◊¥ •Ê¥ÃÁ⁄U∑§ Áfl∑§À¬ ÁŒÿ ªÿ „Ò¥–
(v) πá«U - π§ ◊¥
2 •¥∑§Ê¥ flÊ‹ ¬˝‡Ÿ ‚¥ÅÿÊ 21 ‚ 23 Ã∑§ „Ò¥ ÃÕÊ 4 •¥∑§Ê¥ flÊ‹ ¬˝‡Ÿ ‚¥ÅÿÊ 24 ‚ 29 Ã∑§ „Ò¥– ¬˝àÿ∑§ ¬˝‡Ÿ „ÃÈ ÁŒÿ ªÿ ÁŸŒ¸‡ÊÊ¥
∑§ •ŸÈ‚Ê⁄U ©ã„¥ „‹ ∑§⁄¥U–
(vi) πá«U - ª§ ◊¥ —
(a) 2 •¥∑§Ê¥ flÊ‹ ¬˝‡Ÿ ‚¥ÅÿÊ 30 ‚ 35 Ã∑§ •Áà ‹ÉÊÈ-©ûÊ⁄U flÊ‹ ¬˝‡Ÿ „Ò¥– Á¡Ÿ∑§Ê ©ûÊ⁄U 30 ‚ 50 ‡ÊéŒÊ¥ ∑§Ë ‚Ë◊Ê ◊¥
ÁŒÿÊ ¡ÊŸÊ „Ò–
(b) 3 •¥∑§Ê¥ flÊ‹ ¬˝‡Ÿ ‚¥ÅÿÊ 36 ‚ 41 Ã∑§ ‹ÉÊÈ-©ûÊ⁄U flÊ‹ ¬˝‡Ÿ „Ò¥– Á¡Ÿ∑§Ê ©ûÊ⁄U 50 ‚ 80 ‡ÊéŒÊ¥ ∑§Ë ‚Ë◊Ê ◊¥ ÁŒÿÊ
¡ÊŸÊ „Ò–
(c) 5 •¥∑§Ê¥ flÊ‹ ¬˝‡Ÿ ‚¥ÅÿÊ 42 ‚ 45 ‹ê’ ©ûÊ⁄U flÊ‹ ¬˝‡Ÿ „Ò¥– Á¡Ÿ∑§Ê ©ûÊ⁄U 80 ‚ 120 ‡ÊéŒÊ¥ ∑§Ë ‚Ë◊Ê ◊¥ ÁŒÿÊ ¡ÊŸÊ
„Ò–
67/S/A-224-A ] 3 [ Contd...
Page 4
1. The convention is based on the principle “Anticipate no profit, but provide for all possible 1
losses”.
(A) Materiality (B) Conservatism
(C) Business entity (D) None of these
“‹Ê÷ ∑§Ê •ŸÈ◊ÊŸ Ÿ ‹ªÊ∑§⁄U, ‚÷Ë ‚¥÷ÊÁflà „ÊÁŸÿÊ¥ „ÃÈ ¬˝ÊflœÊŸ ∑§⁄¥U”– ß‚ Á‚hʥà ¬⁄U •ÊœÊÁ⁄Uà ¬Á⁄U¬Ê≈UË „Ò —
(A) ‚Ê⁄UÃÊ (B) M§Á…∏flÊÁŒÃÊ
(C) √ÿfl‚Êÿ ß∑§Ê߸ (D) ߟ◊¥ ‚ ∑§Ê߸ Ÿ„Ë¥
Going concern concept states that a business firm will continue to carry on its activities for
a/an :
(A) limited life (B) a very long life
(C) indefinite life (D) long life
øÊ‹Í √ÿfl‚Êÿ •flœÊ⁄UáÊÊ ∑§ •ŸÈ‚Ê⁄U √ÿfl‚Êÿ ∑§Ë Á∑˝§ÿÊ∞° ¡Ê⁄UË ⁄U„¥ªË —
(A) ‚ËÁ◊à ‚◊ÿ Ã∑§ (B) ’„Èà ‹¥’ ‚◊ÿ Ã∑§
(C) •Ÿ¥Ã ∑§Ê‹ Ã∑§ (D) ‹¥’ ‚◊ÿ Ã∑§
2. Which of the following includes in external liabilities ? 1
(A) Capital (B) Interest on capital
(C) Reserves (D) Sundry Creditors
’Ês ŒÿÃÊ•Ê¥ ∑§ •¥Ãª¸Ã ÁŸêŸ ◊¥ ‚ ÄÿÊ ‚Áê◊Á‹Ã „ÊÃÊ „Ò?
(A) ¬Í°¡Ë (B) ¬Í°¡Ë ¬⁄U éÿÊ¡
(C) ‚¥øÿ (D) ÁflÁflœ ‹ŸŒÊ⁄U
3. Accounting does not record non-financial transactions because of : 1
(A) Entity concept (B) Accrual concept
(C) Money measurement concept (D) None of the above
‹πÊ¥∑§Ÿ ◊¥ ªÒ⁄U-ÁflÁûÊÿ ‹ŸŒŸÊ¥ ∑§Ê ‹πÊ Ÿ ∑§⁄UŸ ∑§Ê ∑§Ê⁄UáÊ „Ò —
(A) ß∑§Ê߸ •flœÊ⁄UáÊÊ (B) ©¬Ê¡¸Ÿ •flœÊ⁄UáÊÊ
(C) ◊ÈŒ˝Ê ◊ʬ •flœÊ⁄UáÊÊ (D) ߟ◊¥ ‚ ∑§Ê߸ Ÿ„Ë¥
Revenue is considered as being earned when :
(A) Commission Received (B) Sale of goods
(C) Interest received (D) Cash received from Debtors
•Êª◊ ∑§Ê ©¬Ê¡¸Ÿ ◊ÊŸÊ ¡ÊÃÊ „Ò ¡’ —
(A) ∑§◊ˇʟ ¬˝Êåà „Ê (B) ◊Ê‹ ∑§Ê Áfl∑˝§ÿ „Ê
(C) éÿÊ¡ ¬˝Êåà „Ê (D) ŒŸŒÊ⁄UÊ¥ ‚ ⁄UÊ∑§«∏ ¬˝Êåà „Ê
67/S/A-224-A ] 4 [ Contd...
Page 5
(A) Capital (B) Reserves
(C) Profit of business (D) Bills payable
•Ê¥ÃÁ⁄U∑§ ŒÿÃÊ•Ê¥ ∑§ •¥Ãª¸Ã ÁŸêŸ ◊¥ ‚ ÄÿÊ ‚Áê◊Á‹Ã Ÿ„Ë¥ „Ò?
(A) ¬Í°¡Ë (B) ‚¥øÿ
(C) √ÿfl‚Êÿ ∑§Ê ‹Ê÷ (D) Œÿ Áfl¬òÊ
Out of the following, which can be recorded in the books of accounts ?
(A) Purchase of Machinery for ` 1,00,000
(B) Delay in supply of raw Materials of ` 50,000
(C) Conflict between two managers causes a loss of ` 1,00,000.
(D) All of the above
ÁŸêŸ ◊¥ ‚ Á∑§‚ ‹πÊ ¬ÈSÃ∑§Ê¥ ◊¥ •Á÷‹Áπà Á∑§ÿÊ ¡Ê ‚∑§ÃÊ „Ò?
(A) ` 1,00,000 ∑§Ë ◊‡ÊËŸ⁄UË π⁄UËŒË
(B) ` 50,000 ∑§ ∑§ìÊ ◊Ê‹ ∑§Ë •Ê¬ÍÁø ◊¥ Áfl‹¥’
(C) ŒÊ ¬˝’¥œ∑§Ê¥ ∑§ ’Ëø ◊Ã÷Œ ∑§ ∑§Ê⁄UáÊ ` 1,00,000 ∑§Ë „ÊÁŸ
(D) ©¬⁄UÊÄà ‚÷Ë
5. Following the straight line method of depreciation on particular asset year after year is because 1
of which convention ?
(A) Conservatism (B) Materiality (C) Consistency (D) None of these
Á∑§‚ ¬Á⁄U¬Ê≈UË ∑§ ∑§Ê⁄UáÊ Á∑§‚Ë ‚¥¬ÁûÊ ¬⁄U fl·¸ ¬˝Áà fl·¸ OÊ‚ ∑§Ë ‚⁄U‹ ⁄UπÊ ÁflÁœ •¬ŸÊ߸ ¡ÊÃË „Ò?
(A) M§Á…∏flÊÁŒÃÊ (B) ‚Ê⁄UÃÊ (C) ‚¥ªÃÃÊ (D) ߟ◊¥ ‚ ∑§Ê߸ Ÿ„Ë¥
6. Dual aspect concept expressed in terms of fundamental accounting equation : 1
(A) Assets+Capital=Liabilities (B) Assets−Capital=Liabilities
(C) Assets+Liabilities=Capital (D) All of the above
Ám¬ˇÊËÿ •flœÊ⁄UáÊÊ ◊Í‹÷Íà ‹πÊ¥∑§Ÿ ‚◊Ë∑§⁄UáÊ ∑§ M§¬ ◊¥ ŒÎÁc≈UªÊø⁄U „ÊÃË „Ò —
(A) ‚¥¬ÁûÊÿÊ°+¬Í°¡Ë=ŒÿÃÊ∞° (B) ‚¥¬ÁûÊÿÊ°−¬Í°¡Ë=ŒÿÃÊ∞°
(C) ‚¥¬ÁûÊÿÊ°+ŒÿÃÊ∞°=¬Í°¡Ë (D) ©¬⁄UÊÄà ‚÷Ë
67/S/A-224-A ] 5 [ Contd...
Page 6
(A) Goodwill (B) Machinery (C) Mines (D) Furniture
ÁŸêŸÁ‹Áπà ◊¥ ‚ ˇÊÿË ‚¥¬ÁûÊ ∑§ÊÒŸ-‚Ë „Ò?
(A) ÅÿÊÁà (B) ◊‡ÊËŸ⁄UË (C) πŒÊŸ¥ (D) $»§ŸË¸ø⁄U
Which of the following is not an intangible asset ?
(A) Goodwill (B) Trademarks (C) Patents (D) Cash
ÁŸêŸÁ‹Áπà ◊¥ ‚ •◊Íø ‚¥¬ÁûÊ ∑§ÊÒŸ-‚Ë Ÿ„Ë¥ „Ò?
(A) ÅÿÊÁà (B) √ÿʬÊ⁄U Áøq (C) ∞∑§Sfl (D) ⁄UÊ∑§«∏
8. Valuation of closing stock is considered at lower cost or market value because of : 1
(A) Convention of Disclosure (B) Convention of Conservatism
(C) Convention of Consistency (D) Convention of Materiality
‹ÊªÃ •ÕflÊ ’Ê$¡Ê⁄U ◊ÍÀÿ ◊¥ ‚ ∑§◊ ¬⁄U •¥ÁÃ◊ S∑¥§œ ∑§Ê ◊ÍÀÿÊ¥∑§Ÿ ∑§⁄UŸ ∑§Ê ∑§Ê⁄UáÊ „Ò —
(A) ¬˝∑§≈UË∑§⁄UáÊ ¬Á⁄U¬Ê≈UË (B) M§Á…∏flÊÁŒÃÊ ¬Á⁄U¬Ê≈UË
(C) ‚¥ªÃÃÊ ¬Á⁄U¬Ê≈UË (D) ‚Ê⁄UÃÊ ¬Á⁄U¬Ê≈UË
9. On the basis of Traditional Classification, accounts are classified into : 1
(A) 2 categories (B) 3 categories (C) 4 categories (D) 5 categories
¬⁄¥U¬⁄Uʪà flªË¸∑§⁄UáÊ ∑§ •ÊœÊ⁄U ¬⁄U πÊÃÊ¥ ∑§Ê flªË¸∑§⁄UáÊ Á∑§ÿÊ ¡ÊÃÊ „Ò —
(A) 2 üÊÁáÊÿÊ¥ ◊¥ (B) 3 üÊÁáÊÿÊ¥ ◊¥ (C) 4 üÊÁáÊÿÊ¥ ◊¥ (D) 5 üÊÁáÊÿÊ¥ ◊¥
Harish purchased furniture for ` 45,000. Furniture account is :
(A) Debited (B) Credited
(C) Both Debited and Credited (D) Neither Debited nor Credited
„⁄UË‡Ê Ÿ ` 45,000 ∑§Ê $»§ŸË¸ø⁄U ∑˝§ÿ Á∑§ÿÊ– $»§ŸË¸ø⁄U πÊà ∑§Ê —
(A) ŸÊ◊ ∑§⁄¥Uª (B) ¡◊Ê ∑§⁄¥Uª
(C) ŸÊ◊ fl ¡◊Ê, ŒÊŸÊ¥ ∑§⁄¥Uª (D) Ÿ ÃÊ ŸÊ◊ ∑§⁄¥Uª •ÊÒ⁄U Ÿ „Ë ¡◊Ê ∑§⁄¥Uª
67/S/A-224-A ] 6 [ Contd...
Page 7
(A) Cash Account
(B) Rent Account
(C) Both Rent Account and Cash Account
(D) None of these
` 5,000 Á∑§⁄UÊÿÊ ÷ȪÃÊŸ ∑§⁄UŸ ¬⁄U ∑§ÊÒŸ ‚Ê πÊÃÊ/πÊà ¬˝÷ÊÁflà „Ê¥ª?
(A) ⁄UÊ∑§«∏ πÊÃÊ
(B) Á∑§⁄UÊÿÊ πÊÃÊ
(C) Á∑§⁄UÊÿÊ πÊÃÊ fl ⁄UÊ∑§«∏ πÊÃÊ, ŒÊŸÊ¥
(D) ߟ◊¥ ‚ ∑§Ê߸ Ÿ„Ë¥
11. Non cash voucher refers to : 1
(A) Debit voucher (B) Credit voucher
(C) Transfer voucher (D) None of these
ªÒ⁄U-⁄UÊ∑§«∏ ¬˝◊ÊáÊ∑§ ‚ •Á÷¬˝Êÿ „Ò —
(A) ŸÊ◊ ¬˝◊ÊáÊ∑§ (B) ¡◊Ê ¬˝◊ÊáÊ∑§
(C) •¥Ã⁄UáÊ ¬˝◊ÊáÊ∑§ (D) ߟ◊¥ ‚ ∑§Ê߸ Ÿ„Ë¥
Credit vouchers are prepared for recording :
(A) Cash receipts
(B) Cash payments
(C) Both Cash Receipts and Cash Payments
(D) None of these
Á¡‚∑§ •Á÷‹πŸ „ÃÈ ¡◊Ê ¬˝◊ÊáÊ∑§ ’ŸÊ∞ ¡Êà „Ò¥, fl„ „Ò —
(A) ⁄UÊ∑§«∏ ¬˝ÊÁåÃÿÊ°
(B) ⁄UÊ∑§«∏ ÷ȪÃÊŸ
(C) ⁄UÊ∑§«∏ ¬˝ÊÁåÃÿÊ° ÃÕÊ ⁄UÊ∑§«∏ ÷ȪÃÊŸ, ŒÊŸÊ¥
(D) ߟ◊¥ ‚ ∑§Ê߸ Ÿ„Ë¥
67/S/A-224-A ] 7 [ Contd...
Page 8
(A) Balancing (B) Posting (C) Journalising (D) None of these
‹ŸŒŸÊ¥ ∑§Ê ⁄UÊ¡ŸÊ◊ø ◊¥ •Á÷‹Áπà ∑§⁄UŸ ∑§Ë ¬˝Á∑˝§ÿÊ ∑§„‹ÊÃË „Ò —
(A) ‡Ê· ÁŸ∑§Ê‹ŸÊ (B) πÃÊÒŸË (C) ⁄UÊ¡ŸÊ◊Áøà ∑§⁄UŸÊ (D) ߟ◊¥ ‚ ∑§Ê߸ Ÿ„Ë¥
General Journal is also known as :
(A) Purchase book (B) Sales book
(C) Return outward book (D) Journal proper
‚Ê◊Êãÿ ⁄UÊ¡ŸÊ◊ø ∑§Ê ß‚ ŸÊ◊ ‚ ÷Ë ¡ÊŸÊ ¡ÊÃÊ „Ò —
(A) ∑˝§ÿ ’„Ë (B) Áfl∑˝§ÿ ’„Ë
(C) flʬ‚Ë ¡Êfl∑§ ’„Ë (D) ⁄UÊ¡ŸÊ◊øÊ Áfl‡Ê·
13. “Goods returned by customer”. Which two accounts are affected ? 1
(A) Cash Account and Return inward account
(B) Customer account and Return inward account
(C) Customer account and Return outward account
(D) None of these
“ª˝Ê„∑§ mÊ⁄UÊ ◊Ê‹ flʬ‚Ë”– ∑§ÊÒŸ ‚ ŒÊ πÊà ¬˝÷ÊÁflà „È∞?
(A) ⁄UÊ∑§«∏ πÊÃÊ ÃÕÊ flʬ‚Ë •Êfl∑§ πÊÃÊ
(B) ª˝Ê„∑§ πÊÃÊ ÃÕÊ flʬ‚Ë •Êfl∑§ πÊÃÊ
(C) ª˝Ê„∑§ πÊÃÊ ÃÕÊ flʬ‚Ë ¡Êfl∑§ πÊÃÊ
(D) ߟ◊¥ ‚ ∑§Ê߸ Ÿ„Ë¥
14. Narration of Journal entry is recorded in the column of : 1
(A) Date (B) Particulars (C) Dr. Amount (D) Cr. Amount
⁄UÊ¡ŸÊ◊øÊ ¬˝ÁflÁc≈U ∑§Ê S¬c≈UË∑§⁄UáÊ Á¡‚ SÃ¥÷ ◊¥ •Á÷‹Áπà Á∑§ÿÊ ¡ÊÃÊ „Ò, fl„ „Ò —
(A) ÁÃÁÕ (B) Áflfl⁄UáÊ (C) ŸÊ◊ ⁄UÊÁ‡Ê (D) ¡◊Ê ⁄UÊÁ‡Ê
67/S/A-224-A ] 8 [ Contd...
Page 9
(A) All cash receipts
(B) All cash payments
(C) All cash receipts and cash payments
(D) None of these
⁄UÊ∑§«∏ ’„Ë •Á÷‹Áπà ∑§⁄UÃË „Ò —
(A) ‚÷Ë ⁄UÊ∑§«∏ ¬˝ÊÁåÃÿÊ°
(B) ‚÷Ë ⁄UÊ∑§«∏ ÷ȪÃÊŸ
(C) ‚÷Ë ⁄UÊ∑§«∏ ¬˝ÊÁåÃÿÊ° ÃÕÊ ⁄UÊ∑§«∏ ÷ȪÃÊŸ
(D) ߟ◊¥ ‚ ∑§Ê߸ Ÿ„Ë¥
16. Which two accounts are involved in “Contra entry” ? 1
(A) Cash account and Capital Account
(B) Cash account and Bank Account
(C) Bank Account and Capital Account
(D) None of these
¬˝Áì˝ÁflÁc≈U ∑§ •¥Ãª¸Ã ∑§ÊÒŸ ‚ ŒÊ πÊà ‚¥Á‹åà „Êà „Ò¥?
(A) ⁄UÊ∑§«∏ πÊÃÊ ÃÕÊ ¬Í°¡Ë πÊÃÊ
(B) ⁄UÊ∑§«∏ πÊÃÊ ÃÕÊ ’Ò¥∑§ πÊÃÊ
(C) ’Ò¥∑§ πÊÃÊ ÃÕÊ ¬Í°¡Ë πÊÃÊ
(D) ߟ◊¥ ‚ ∑§Ê߸ Ÿ„Ë¥
A separate cash book maintained to record small transactions is called :
(A) Simple Cash book (B) Bank Cash book
(C) Petty Cash book (D) None of these
¿UÊ≈U ‹ŸŒŸÊ¥ ∑§ •Á÷‹πŸ „ÃÈ ⁄UπË ¡ÊŸ flÊ‹Ë ¬ÎÕ∑§ ⁄UÊ∑§«∏ ’„Ë, ∑§„‹ÊÃË „Ò —
(A) ‚ÊœÊ⁄UáÊ ⁄UÊ∑§«∏ ’„Ë (B) ’Ò¥∑§ ⁄UÊ∑§«∏ ’„Ë
(C) πÈŒ⁄UÊ ⁄UÊ∑§«∏ ’„Ë (D) ߟ◊¥ ‚ ∑§Ê߸ Ÿ„Ë¥
67/S/A-224-A ] 9 [ Contd...
Page 10
(A) Date Column (B) Voucher No. Column
(C) Ledger Folio (D) Amount Column
πÊÃÊ ’„Ë ∑§Ê ¬Îc∆U ‚¥ÅÿÊ Œ‡ÊʸÿÊ ¡ÊÃÊ „Ò —
(A) ÁÃÁÕ SÃ¥÷ ◊¥ (B) ¬˝◊ÊáÊ∑§ ‚¥ÅÿÊ SÃ¥÷ ◊¥
(C) πÊÃÊ ’„Ë ¬Îc∆U SÃ¥÷ ◊¥ (D) ⁄UÊÁ‡Ê SÃ¥÷ ◊¥
18. Central Processing Unit (CPU) does not include : 1
(A) Control unit (B) Memory unit
(C) Arithmetic Logic Unit (D) Output unit
∑§ãŒ˝Ëÿ ¬˝‚¥S∑§⁄UáÊ ß∑§Ê߸ ◊¥ ‚Áê◊Á‹Ã Ÿ„Ë¥ „Ò —
(A) ÁŸÿ¥òÊáÊ ß∑§Ê߸ (B) S◊ÎÁà ß∑§Ê߸
(C) •¥∑§ªÁáÊÃËÿ ÃÊÁ∑¸§∑§ ß∑§Ê߸ (D) ÁŸª¸Ã ß∑§Ê߸
19. The commonly used output devices include : 1
(A) Monitor (B) Plotter (C) Printer (D) All of the above
¬˝Êÿ— ¬˝ÿÈÄà „ÊŸ flÊ‹Ê ÁŸª¸Ã ©¬∑§⁄UáÊ „Ò —
(A) ◊ÊÚŸË≈U⁄U (B) å‹ÊÚ≈U⁄U (C) ◊ÈŒ˝∑§ (D) ©¬⁄UÊÄà ‚÷Ë
What is the full form of TPS ?
(A) Transaction Processing System
(B) Transit Process System
(C) Transaction Processing Storage
(D) None of these
≈UË.¬Ë.∞‚. ∑§Ê ¬Íáʸ M§¬ ÄÿÊ „Ò?
(A) ≈˛UÊ¥¡Òćʟ ¬˝Ê‚Á‚¥ª Á‚S≈U◊
(B) ≈˛UÊ¥Á¡≈U ¬˝Ê‚‚ Á‚S≈U◊
(C) ≈˛UÊ¥¡Òćʟ ¬˝Ê‚Á‚¥ª S≈UÊ⁄U¡
(D) ߟ◊¥ ‚ ∑§Ê߸ Ÿ„Ë¥
67/S/A-224-A ] 10 [ Contd...
Page 11
(A) Diligence (B) Storage
(C) Both (A) and (B) (D) None of the above
ÁŸêŸ ◊¥ ‚ ∑§ÊÒŸ ‚Ë Áfl‡Ê·ÃÊ ∑§êåÿÍ≈U⁄U ∑§Ë „Ò?
(A) ¬Á⁄Uo˝◊ (B) ‚¥ª˝„áÊ
(C) ŒÊŸÊ¥, (A) ÃÕÊ (B) (D) ߟ◊¥ ‚ ∑§Ê߸ Ÿ„Ë¥
Commonly used accounting software is :
(A) Tally (B) Window (C) Easy books (D) Credit Manager
‚Ê◊Êãÿ× ¬˝ÿÈÄà „ÊŸ flÊ‹Ê ‹πÊ¥∑§Ÿ ‚ÊÚç≈Uflÿ⁄U „Ò —
(A) ≈ÒU‹Ë (B) Áfl¥«UÊ (C) ߸$¡Ë ’ÈÄ‚ (D) ∑˝§Á«U≈U ◊ÒŸ¡⁄U
SECTION - B / πá«U - π
21. Complete the following statements. (any two) 2x1
(i) Unsold goods are valued at cost price or market price, whichever is __________.
(ii) Convention of consistency states that the same accounting methods should be adopted
every year for preparing __________ statements.
(iii) Sundry Creditors included in creditors for __________.
ÁŸêŸ ◊¥ ‚ Á∑§ã„Ë¥ ŒÊ ∑§ÕŸÊ¥ ∑§Ê ¬Íáʸ ∑§ËÁ¡∞ —
(i) •ŸÁ’∑§ ◊Ê‹ ∑§Ê ‹ÊªÃ ◊ÍÀÿ •ÕflÊ ’Ê$¡Ê⁄U ◊ÍÀÿ, ŒÊŸÊ¥ ◊¥ ¡Ê ÷Ë __________ „Ê, ¬⁄U ◊ÍÀÿÊ¥Á∑§Ã Á∑§ÿÊ ¡ÊÃÊ
„Ò–
(ii) ‚¥ªÃÃÊ ¬Á⁄U¬Ê≈UË ∑§„ÃË „Ò Á∑§ __________ Áflfl⁄UáÊÊ¥ ∑§Ê ’ŸÊŸ „ÃÈ ¬˝ÁÃfl·¸ ‚◊ÊŸ ‹πÊ¥∑§Ÿ ÁflÁœÿÊ° •¬ŸÊ߸
¡ÊŸË øÊÁ„∞°–
(iii) ÁflÁflœ ‹ŸŒÊ⁄UÊ¥ ◊¥ __________ „ÃÈ ‹ŸŒÊ⁄U ‚Áê◊Á‹Ã „Êà „Ò¥–
22. Match the following. (any two) 2x1
(i) Debtor (a) To whom money is owing
(ii) Creditor (b) Cash or goods withdrawn for personal use
(iii) Drawings (c) Who owes money
Á∑§ã„Ë¥ ŒÊ ∑§Ê Á◊‹ÊŸ ∑§ËÁ¡∞–
(i) ŒŸŒÊ⁄U (a) Á¡‚ ´§áÊ øÈ∑§ÊÿÊ ¡ÊŸÊ „Ò
(ii) ‹ŸŒÊ⁄U (b) ÁŸ¡Ë ©¬ÿʪ „ÃÈ ⁄UÊ∑§«∏ •ÕflÊ ◊Ê‹ ‹ŸÊ
(iii) •Ê„⁄UáÊ (c) ¡Ê ´§áÊË „Ò
67/S/A-224-A ] 11 [ Contd...
Page 12
(i) The computerised accounting system is capable of offering __________ and __________
reporting.
(ii) __________ and __________ are the basic requirements of the computerised accounting
system.
Á⁄UÄà SÕÊŸ ÷Á⁄U∞– (∑§Ê߸ ∞∑§)
(i) __________ ÃÕÊ __________ Á⁄U¬ÊÁ≈ZUª ¬˝ŒÊŸ ∑§⁄UŸ ◊¥ ∑§êåÿÍ≈˛UË∑Χà ‹πÊ¥∑§Ÿ ¬˝áÊÊ‹Ë ‚ˇÊ◊ „Ò–
(ii) ∑§êåÿÍ≈˛UË∑Χà ‹πÊ¥∑§Ÿ ¬˝áÊÊ‹Ë „ÃÈ __________ ÃÕÊ __________ ◊Í‹ •Êfl‡ÿ∑§ÃÊ∞° „Ò¥–
24. Give one word answer for the following statements. (any four) 4x1
(i) Under which concept, the business and its owners are two separate entities.
(ii) Give an example of tangible asset.
(iii) Excess of business expenses incurred over the business revenue.
(iv) The concept assumes that, business enterprise should not be closed down in the near
future.
(v) Inflow of money from sale of goods.
(vi) Convention which helps in minimising errors in calculation.
ÁŸêŸ ◊¥ ‚ Á∑§ã„Ë¥ øÊ⁄U ∑§ÕŸÊ¥ „ÃÈ ∞∑§-∞∑§ ‡ÊéŒ ◊¥ ©ûÊ⁄U ŒËÁ¡∞–
(i) Á∑§‚ ‚¥∑§À¬ŸÊ ∑§ •¥Ãª¸Ã √ÿfl‚Êÿ ÃÕÊ ©‚∑§ SflÊ◊Ë, ŒÊ ¬ÎÕ∑§ ß∑§Ê߸ÿÊ° „Ò¥–
(ii) ◊Íø ‚¥¬ÁûÊ ∑§Ê ∞∑§ ©ŒÊ„⁄UáÊ ŒËÁ¡∞–
(iii) √ÿfl‚Êÿ ∑§ •Êª◊ ¬⁄U √ÿfl‚Êÿ ∑§ √ÿÿÊ¥ ∑§Ê •ÊÁœÄÿ–
(iv) ÿ„ ‚¥∑§À¬ŸÊ ◊ÊŸÃË „Ò Á∑§ √ÿfl‚Êÿ ÁŸ∑§≈U ÷Áflcÿ ◊¥ ’¥Œ „ÊŸ flÊ‹Ê Ÿ„Ë¥ „Ò–
(v) ◊Ê‹ ∑§ Á’∑˝§ÿ ‚ ◊ÈŒ˝Ê ∑§Ê •ãÃflʸ„–
(vi) ÿ„ ¬Á⁄U¬Ê≈UË ªáÊŸÊ ◊¥ „ÊŸ flÊ‹Ë òÊÈÁ≈UÿÊ¥ ∑§Ê ãÿÍŸÃ◊ ∑§⁄UŸ ◊¥ ‚„ÊÿÃÊ ∑§⁄UÃË „Ò–
67/S/A-224-A ] 12 [ Contd...
Page 13
(i) Goods purchased for cash
(ii) Purchased furniture for cash
(iii) Rent paid
(iv) Sold goods to Haresh on Credit
(v) Withdrew cash for personal use
(vi) Interest received
ÁŸêŸ ◊¥ ‚ Á∑§ã„Ë¥ øÊ⁄U ‹ŸŒŸÊ¥ ∑§ ŒÊ ¬ˇÊ (¬˝÷Êfl) Á‹Áπ∞–
(i) Ÿ∑§Œ ◊Ê‹ π⁄UËŒÊ
(ii) Ÿ∑§Œ $»§ŸË¸ø⁄U π⁄UËŒÊ
(iii) Á∑§⁄UÊÿÊ ÷ȪÃÊŸ Á∑§ÿÊ
(iv) „⁄UË‡Ê ∑§Ê ©œÊ⁄U ◊Ê‹ ’øÊ
(v) ÁŸ¡Ë ©¬ÿʪ „ÃÈ ⁄UÊ∑§«∏ ÁŸ∑§Ê‹Ê
(vi) éÿÊ¡ ¬˝Êåà Á∑§ÿÊ
26. Match the following. (any four) 4x1
(a) Assets (i) Increase is credited and decrease is debited
(b) Cash voucher (ii) Record of small expenses
(c) Liabilities (iii) Book of Original entry
(d) Petty cash book (iv) Cash receipts and payments
(e) Combined entry (v) Increase is debited and decrease is credited
(f) Journal (vi) Contains more than one debit or Credit or both
ÁŸêŸ ◊¥ ‚ Á∑§ã„Ë øÊ⁄U ∑§Ê Á◊‹ÊŸ ∑§ËÁ¡∞–
(a) ‚¥¬ÁûÊÿÊ° (i) flÎÁh ¡◊Ê „ÊÃË „Ò ÃÕÊ ∑§◊Ë ŸÊ◊ „ÊÃË „Ò–
(b) ⁄UÊ∑§«∏ ¬˝◊ÊáÊ∑§ (ii) ‹ÉÊÈ √ÿÿÊ¥ ∑§Ê •Á÷‹π
(c) ŒÿÃÊ∞° (iii) ◊Í‹ ¬˝ÁflÁc≈U ∑§Ë ’„Ë
(d) ‹ÉÊÈ ⁄UÊ∑§«∏ ’„Ë (iv) ⁄UÊ∑§«∏ ¬˝ÊÁåÃÿÊ° ∞fl¥ ÷ȪÃÊŸ
(e) ‚¥ÿÈÄà ¬˝ÁflÁc≈U (v) flÎÁh ŸÊ◊ „ÊÃË „Ò ÃÕÊ ∑§◊Ë ¡◊Ê „ÊÃË „Ò
(f) ⁄UÊ¡ŸÊ◊øÊ (vi) ß‚◊¥ ∞∑§ ‚ •Áœ∑§ ŸÊ◊ •ÕflÊ ¡◊Ê •ÕflÊ ŒÊŸÊ¥ „Êà „Ò¥–
67/S/A-224-A ] 13 [ Contd...
Page 14
(any four)
(i) Commission Received
(ii) M/s M.K. Agencies
(iii) Wages paid
(iv) Aditya Account
(v) Building A/c
(vi) Drawings Account
ÁŸêŸ ◊¥ ‚ √ÿÁÄêà πÊÃÊ¥, flÊSÃÁfl∑§ πÊÃÊ¥ ÃÕÊ ŸÊ◊ ◊ÊòÊ ∑§ πÊÃÊ¥ ∑§Ë ¬„øÊŸ ∑§ËÁ¡∞– (Á∑§ã„Ë¥ øÊ⁄U)
(i) ∑§◊ˇʟ ¬˝ÊåÃ
(ii) ◊Ò‚‚¸ ∞◊.∑§. ∞¡¥‚Ë$¡
(iii) ◊$¡ŒÍ⁄UË ÷ȪÃÊŸ ∑§Ë
(iv) •ÊÁŒàÿ ∑§Ê πÊÃÊ
(v) ÷flŸ πÊÃÊ
(vi) •Ê„⁄UáÊ πÊÃÊ
28. Match the following. (any four) 4x1
(a) Capital (i) Raw-materials to be used
(b) Interest on Capital (ii) Owner’s Claim
(c) Bills payable (iii) Creditors for loans
(d) Bank loans (iv) Amount invested by owners
(e) Wasting assets (v) Oil wells
(f) Stock (vi) Liability
ÁŸêŸ ◊¥ ‚ Á∑§ã„Ë¥ øÊ⁄U ∑§Ê Á◊‹ÊŸ ∑§ËÁ¡∞–
(a) ¬Í°¡Ë (i) ¬˝ÿÈÄà Á∑§ÿÊ ¡ÊŸ flÊ‹Ê ∑§ìÊÊ ◊Ê‹
(b) ¬Í°¡Ë ¬⁄U éÿÊ¡ (ii) SflÊ◊Ë ∑§Ê ŒÊflÊ
(c) Œÿ Áfl¬òÊ (iii) ´§áÊ „ÃÈ ‹ŸŒÊ⁄U
(d) ’Ò¥∑§ ´§áÊ (iv) SflÊÁ◊ÿÊ¥ mÊ⁄UÊ ÁŸflÁ‡Êà œŸ⁄UÊÁ‡Ê
(e) ˇÊÿË ‚¥¬ÁûÊÿÊ° (v) Ë ∑§ ∑ȧ∞°
(f) S∑¥§œ (vi) ŒÿÃÊ
67/S/A-224-A ] 14 [ Contd...
Page 15
(i) Computer is a device that accepts and stores data.
(ii) Magnetic disk is an output unit.
(iii) Accounting documents cannot be prepared through computer.
(iv) The full form of OLTP is Online Transaction Processing.
(v) Computer is an electronic device that can perform only limited operations.
(vi) The computerised accounting is one of the data based oriented applications.
ÁŸêŸ ◊¥ ‚ Á∑§ã„Ë¥ øÊ⁄U flÊÄÿÊ¥ ∑§Ê ‚àÿ •ÕflÊ •‚àÿ ’ÃÊß∞–
(i) ∑§êåÿÍ≈U⁄U ∞∑§ ©¬∑§⁄UáÊ „Ò ¡Ê •Ê°∑§«∏ SflË∑§Ê⁄U ÃÕÊ ‚¥ª˝Á„à ∑§⁄UÃÊ „Ò–
(ii) øÈ¥’∑§Ëÿ øÁ∑˝§∑§Ê ∞∑§ ÁŸª¸Ã ß∑§Ê߸ „Ò–
(iii) ∑§êåÿÍ≈U⁄U ∑§Ë ‚„ÊÿÃÊ ‚ ‹πÊ¥∑§Ÿ ¬˝‹π Ÿ„Ë¥ ’ŸÊÿ ¡Ê ‚∑§Ã–
(iv) OLTP ∑§Ê ¬Íáʸ M§¬ •ÊÚŸ‹Êߟ ≈˛UÊ¥¡Òćʟ ¬˝Ê‚Á‚¥ª „Ò–
(v) ∑§êåÿÍ≈U⁄U ∞∑§ ß‹ÒÄ≈˛UÊÚÁŸ∑§ ©¬∑§⁄UáÊ „Ò ¡Ê ∑§fl‹ ‚ËÁ◊à ¬˝øÊ‹Ÿ ÁŸc¬ÊÁŒÃ ∑§⁄U ‚∑§ÃÊ „Ò–
(vi) ∑§êåÿÍ≈U⁄UË∑Χà ‹πÊ¥∑§Ÿ, «UÊ≈UÊ •ÊœÊÁ⁄Uà •Á÷ÁflãÿSà •ŸÈ¬˝ÿʪʥ ◊¥ ‚ ∞∑§ „Ò–
SECTION - C / πá«U - ª
30. What is meant by a “Bank Column cash Book” ? Draw the format of it. 2
““’Ò¥∑§ SÃ¥÷Ëÿ ⁄UÊ∑§«∏ ’„Ë”” ‚ ÄÿÊ •Á÷¬˝Êÿ „Ò? ß‚∑§Ê ¬˝ÊM§¬ πË¥Áø∞–
Write the accounting technique of :
(a) Cash paid into the bank
(b) Dishonour of a cheque
ÁŸêŸÁ‹Áπà ∑§Ë ‹πÊ¥∑§Ÿ Ã∑§ŸË∑§ Á‹Áπ∞ —
(a) ’Ò¥∑§ ◊¥ ⁄UÊ∑§«∏ ÷ȪÃÊŸ
(b) øÒ∑§ ∑§Ê •ŸÊŒ⁄UáÊ
31. State the advantages of double entry system. 2
Ám-•¥∑§Ÿ ¬˝áÊÊ‹Ë ∑§ ‹Ê÷ ’ÃÊß∞–
67/S/A-224-A ] 15 [ Contd...
Page 16
ˬ≈U ¬⁄U ¬Íáʸ ‹Ê¬ ∑§ ¬˝÷ÊflÊ¥ ∑§Ê fláʸŸ ∑§ËÁ¡∞–
Write any two limitations of a trial balance.
ˬ≈U ∑§Ë ∑§Ê߸ ŒÊ ‚Ë◊Ê∞° Á‹Áπ∞–
33. What are the factors affecting the depreciation ? 2
OÊ‚ ∑§Ê ¬˝÷ÊÁflà ∑§⁄UŸ flÊ‹ ∑§Ê⁄U∑§ ∑§ÊÒŸ-∑§ÊÒŸ ‚ „Ò¥?
34. Write a short note on “Income statement”. 2
“•Êÿ Áflfl⁄UáÊ” ¬⁄U ∞∑§ ‚¥ÁˇÊåà Á≈Uå¬áÊË Á‹Áπ∞–
35. Explain the treatment of outstanding expenses in the financial statements with a suitable 2
example.
∞∑§ ©¬ÿÈÄà ©ŒÊ„⁄UáÊ ∑§ ‚ÊÕ ÁflûÊËÿ Áflfl⁄UáÊÊ¥ ◊¥ •ŒûÊ √ÿÿÊ¥ ∑§Ê √ÿfl„Ê⁄U ‚◊¤ÊÊß∞–
From the following information, prepare Balance sheet of M/s Nigam Traders as on
31.03.2023.
Capital - ` 1,00,000
Building - ` 75,000
Creditors - ` 15,000
Debtors - ` 12,000
Cash in hand - ` 8,000
Cash at Bank - ` 7,000
Net Profit - ` 20,000
Investments - ` 33,000
ÁŸêŸÁ‹Áπà ‚ÍøŸÊ•Ê¥ ‚ ◊Ò‚‚¸ ÁŸª◊ ≈˛U«U‚¸ ∑§Ê 31.03.2023 ∑§Ê ÃÈ‹Ÿ ¬òÊ ’ŸÊß∞–
¬Í°¡Ë - ` 1,00,000
÷flŸ - ` 75,000
‹ŸŒÊ⁄U - ` 15,000
ŒŸŒÊ⁄U - ` 12,000
„SÃSÕ ⁄UÊ∑§«∏ - ` 8,000
’Ò¥∑§SÕ ⁄UÊ∑§«∏ - ` 7,000
‡ÊÈh ‹Ê÷ - ` 20,000
ÁŸfl‡Ê - ` 33,000
67/S/A-224-A ] 16 [ Contd...
Page 17
‚ÊœÊ⁄UáÊ ⁄UÊ∑§«∏ ’„Ë ’ŸÊŸ „ÃÈ ∑§ÊÒŸ-∑§ÊÒŸ ‚ ø⁄UáÊ •¬ŸÊ∞ ¡Êà „Ò¥?
37. What is depreciation ? Write the various objectives of providing depreciation. 3
OÊ‚ ÄÿÊ „Ò? OÊ‚ ‹ªÊŸ ∑§ ÁflÁ÷ÛÊ ©g‡ÿ Á‹Áπ∞–
What is diminishing balance method ? Explain its merits and demerits.
OÊÁ‚à ‡Ê· ÁflÁœ ÄÿÊ „Ò? ß‚∑§ ªÈáÊ ∞fl¥ ŒÊ· ‚◊¤ÊÊß∞–
38. A plant is purchased for ` 1,00,000 on 1st April 2021. It is estimated that the residual value 3
of the plant at the end of the working life of 10 years will be ` 20,000. Calculate the depreciation
to be provided per year on Straight Line Method. You are also to show the plant account for
2 years.
1 •¬˝Ò‹ 2021∑§Ê ` 1,00,000 ∑§Ê ‚¥ÿ¥òÊ π⁄Uˌʖÿ„ •ŸÈ◊ÊÁŸÃ „È•Ê Á∑§ 10 fl·ÊZ ∑§ ∑§Êÿ¸ ¡ËflŸ ∑§ ©¬⁄Uʥà ߂∑§Ê
•flÁ‡Êc≈U ◊ÍÀÿ ` 20,000 „ʪʖ ‚⁄U‹ ⁄UπÊ ÁflÁœ ‚ ¬˝ÁÃfl·¸ ‹ªÊ߸ ¡ÊŸ flÊ‹Ë OÊ‚ ∑§Ë ⁄UÊÁ‡Ê ¬Á⁄U∑§Á‹Ã ∑§ËÁ¡∞– ŒÊ
fl·ÊZ „ÃÈ •Ê¬ ‚¥ÿ¥òÊ πÊÃÊ ÷Ë Œ‡Êʸß∞–
39. Discuss the errors not disclosed by the trial balance. 3
ˬ≈U mÊ⁄UÊ ¬˝∑§≈U Ÿ „ÊŸ flÊ‹Ë òÊÈÁ≈UÿÊ¥ ∑§Ë øøʸ ∑§ËÁ¡∞–
40. Distinguish between ‘Trading account’ and ‘Profit & Loss account’. 3
“√ÿʬÊ⁄U πÊÃÊ” ∞fl¥ “‹Ê÷-„ÊÁŸ πÊÃÊ” ∑§ ’Ëø •¥Ã÷¸Œ ∑§ËÁ¡∞–
41. What do you mean by financial statements ? State the objectives of preparing financial 3
statements.
ÁflÁûÊÿ Áflfl⁄UáÊÊ¥ ‚ •Ê¬∑§Ê ÄÿÊ •Á÷¬˝Êÿ „Ò? ÁflûÊËÿ Áflfl⁄UáÊ ÃÒÿÊ⁄U ∑§⁄UŸ ∑§ ©g‡ÿ ’ÃÊß∞–
From the following balances of M/s National Traders prepare a Profit and Loss Account for
the year ended 31st March 2023.
Credit balance of Trading A/c - ` 1,25,000
Printing & Stationery - ` 5,000
Freight outward - ` 7,000
Salaries - ` 21,000
Interest received - ` 5,000
Discount allowed - ` 7,000
General expenses - ` 18,000
Salary outstanding as on 31.03.2023 - ` 5,000
67/S/A-224-A ] 17 [ Contd...
Page 18
√ÿʬÊ⁄U πÊà ∑§Ê ¡◊Ê ‡Ê· - ` 1,25,000
◊ÈŒ˝áÊ ∞fl¥ S≈U‡ÊŸ⁄UË - ` 5,000
÷Ê«∏Ê ¡Êfl∑§ - ` 7,000
flß - ` 21,000
éÿÊ¡ ¬˝Êåà - ` 5,000
’≈˜U≈UÊ ¬˝ŒÊŸ Á∑§ÿÊ - ` 7,000
‚Ê◊Êãÿ √ÿÿ - ` 18,000
31 ◊Êø¸ 2023 ∑§Ê •ŒûÊ flß - ` 5,000
42. What is meant by Journal ? What are the purposes of preparing journal ? Draw a format of 5
it.
⁄UÊ¡ŸÊ◊øÊ ‚ ÄÿÊ ÃÊà¬ÿ¸ „Ò? ⁄UÊ¡ŸÊ◊øÊ ’ŸÊŸ ∑§ ©g‡ÿ ∑§ÊÒŸ-∑§ÊÒŸ ‚ „Ò? ß‚∑§Ê ¬˝ÊM§¬ πË¥Áø∞–
Explain the modern classification of Accounts and their fundamental rules of debit & Credit.
πÊÃÊ¥ ∑§Ê •ÊœÈÁŸ∑§ flªË¸∑§⁄UáÊ ÃÕÊ ©Ÿ∑§ ŸÊ◊ ∞fl¥ ¡◊Ê ∑§ ◊Í‹÷Íà ÁŸÿ◊ ‚◊¤ÊÊß∞–
43. What is trial balance ? Discuss the objectives of preparing a trial balance. 5
ˬ≈U ÄÿÊ „Ò? ˬ≈U ’ŸÊŸ ∑§ ©g‡ÿÊ¥ ∑§Ë øøʸ ∑§ËÁ¡∞–
If the trial balance does not tally, it means there are some errors in books of accounts. State
the procedure of locating errors.
ÿÁŒ ˬ≈U ∑§Ê Á◊‹ÊŸ Ÿ „Ê, ÃÊ ß‚∑§Ê •Õ¸ „Ò Á∑§ ‹πÊ-¬ÈSÃ∑§Ê¥ ◊¥ ∑ȧ¿U òÊÈÁ≈UÿÊ° „Ò¥– òÊÈÁ≈UÿÊ¥ ∑§Ê ¬ÃÊ ‹ªÊŸ ∑§Ë ∑§Êÿ¸
ÁflÁœ ’ÃÊß∞–
44. What do you mean by Position statement or Balance Sheet ? What are the objectives of 5
preparing balance sheet ? Draw a proforma of Balance sheet.
ÁSÕÁà Áflfl⁄UáÊ •ÕflÊ ÃÈ‹Ÿ ¬òÊ ‚ •Ê¬∑§Ê ÄÿÊ •Á÷¬˝Êÿ „Ò? ÁSÕÁà Áflfl⁄UáÊ ’ŸÊŸ ∑§ ©g‡ÿ ∑§ÊÒŸ-∑§ÊÒŸ ‚ „Ò? ÁSÕÁÃ
Áflfl⁄UáÊ ∑§Ê ¬˝ÊM§¬ πË¥Áø∞–
67/S/A-224-A ] 18 [ Contd...
Page 19
the year ended on 31.03.2023 and Balance sheet as on 31.03.2023.
Debit Balances ` Credit Balances `
Purchases 17,000 Sales 17,500
Opening stock 1,250 Discount 1,275
Cash 1,500 Bills Payable 900
Building 10,600 Creditors 4,000
Salaries 1,650 Capital 13,000
Bills Receivable 800 Commission 800
Debtors 1,900 Dividend 525
Carriage and freight 500
Rent & Taxes 600
Wages 750
General Expenses 1,000
Insurance 450
38,000 38,000
Adjustments :
(i) Value of stock as on 31.03.2023 was ` 4,500
(ii) Wages outstanding ` 250
(iii) Insurance prepaid ` 50
(iv) Provide depreciation on Building @ 10%
67/S/A-224-A ] 19 [ Contd...
Page 20
31 ◊Êø¸ 2023 ∑§Ê ÁSÕÁà Áflfl⁄UáÊ ’ŸÊß∞ —
Zm_ eof ` O_m eof `
H«$` 17,000 {dH«$` 17,500
àma§{^H$ ñH§$Y 1,250 ~Q²>Q>m 1,275
amoH$‹S> 1,500 Xo` {dnÌ 900
^dZ 10,600 boZXma 4,000
doVZ 1,650 ny±Or 13,000
àmß` {dnÌ 800 H$_reZ 800
XoZXma 1,900 bm^m§e 525
^m‹S>m Ed§ Tw>bmB© 500
{H$am`m Ed§ H$a 600
_µOXÿar 750
gm_mÝ` ì`` 1,000
~r_m 450
38,000 38,000
‚◊ÊÿÊ¡ŸÊ∞° —
(i) 31.03.2023 ∑§Ê S∑¥§œ ∑§Ê ◊ÍÀÿ ` 4,500 ÕÊ–
(ii) •ŒûÊ ◊$¡ŒÍ⁄UË ` 250
(iii) ¬Ífl¸ŒûÊ ’Ë◊Ê ` 50
(iv) ÷flŸ ¬⁄U 10% ∑§Ë Œ⁄U ‚ OÊ‚ ‹ªÊß∞–
-oOo-
67/S/A-224-A ] 20 [ Contd...
Document Details
| Board / Org | NIOS |
| Exam | National Institute of Open Schooling Class 10 |
| Type | Question Paper |
| Pages | 20 |
| Language | english |
| Updated | 24 Sep 2026 |