HBSE Class 11 Sample Paper 2027 Accountancy
Finished viewing? Save it for later —
Download HBSE Class 11 Sample Paper 2027 Accountancy (PDF · 17 pages)About HBSE Class 11 Sample Paper 2027 Accountancy
HBSE Class 11 Sample Paper 2027 Accountancy is available here for free download. Published by Haryana Board for Class 11, this sample paper can be viewed online or downloaded as a PDF (17 pages). Candidates preparing for Class 11 can use HBSE Class 11 Sample Paper 2027 Accountancy to understand the exam pattern, the type of questions asked, and the overall difficulty level.
Frequently Asked Questions
How can I download HBSE Class 11 Sample Paper 2027 Accountancy?
Open this page and click the Download button to save HBSE Class 11 Sample Paper 2027 Accountancy as a PDF. It is completely free on AglaSem Docs.
Is HBSE Class 11 Sample Paper 2027 Accountancy free to download?
Yes. HBSE Class 11 Sample Paper 2027 Accountancy can be viewed online and downloaded as a PDF free of cost on AglaSem Docs.
How many pages does HBSE Class 11 Sample Paper 2027 Accountancy have?
HBSE Class 11 Sample Paper 2027 Accountancy contains 17 pages, which you can read online or download together as a single PDF.
Where can I find more Class 11 study material?
You can find more Class 11 question papers, sample papers, syllabus, and answer keys on AglaSem Docs.
HBSE Class 11 Sample Paper 2027 Accountancy – Text
Read the full text of this sample paper below — useful to quickly search, copy and reference the content online without downloading the PDF.
📄 View text version (18 pages)
Page 1
HBSE Class 11 Sample
Paper 2027
Accountancy
EXAM YEAR TYPE SUBJECT
Haryana Class 11 2027 Sample Paper Accountancy
Notes · Sample Papers · Previous Year Papers · Mock Tests
Page 2
. s e
em l a
as a g
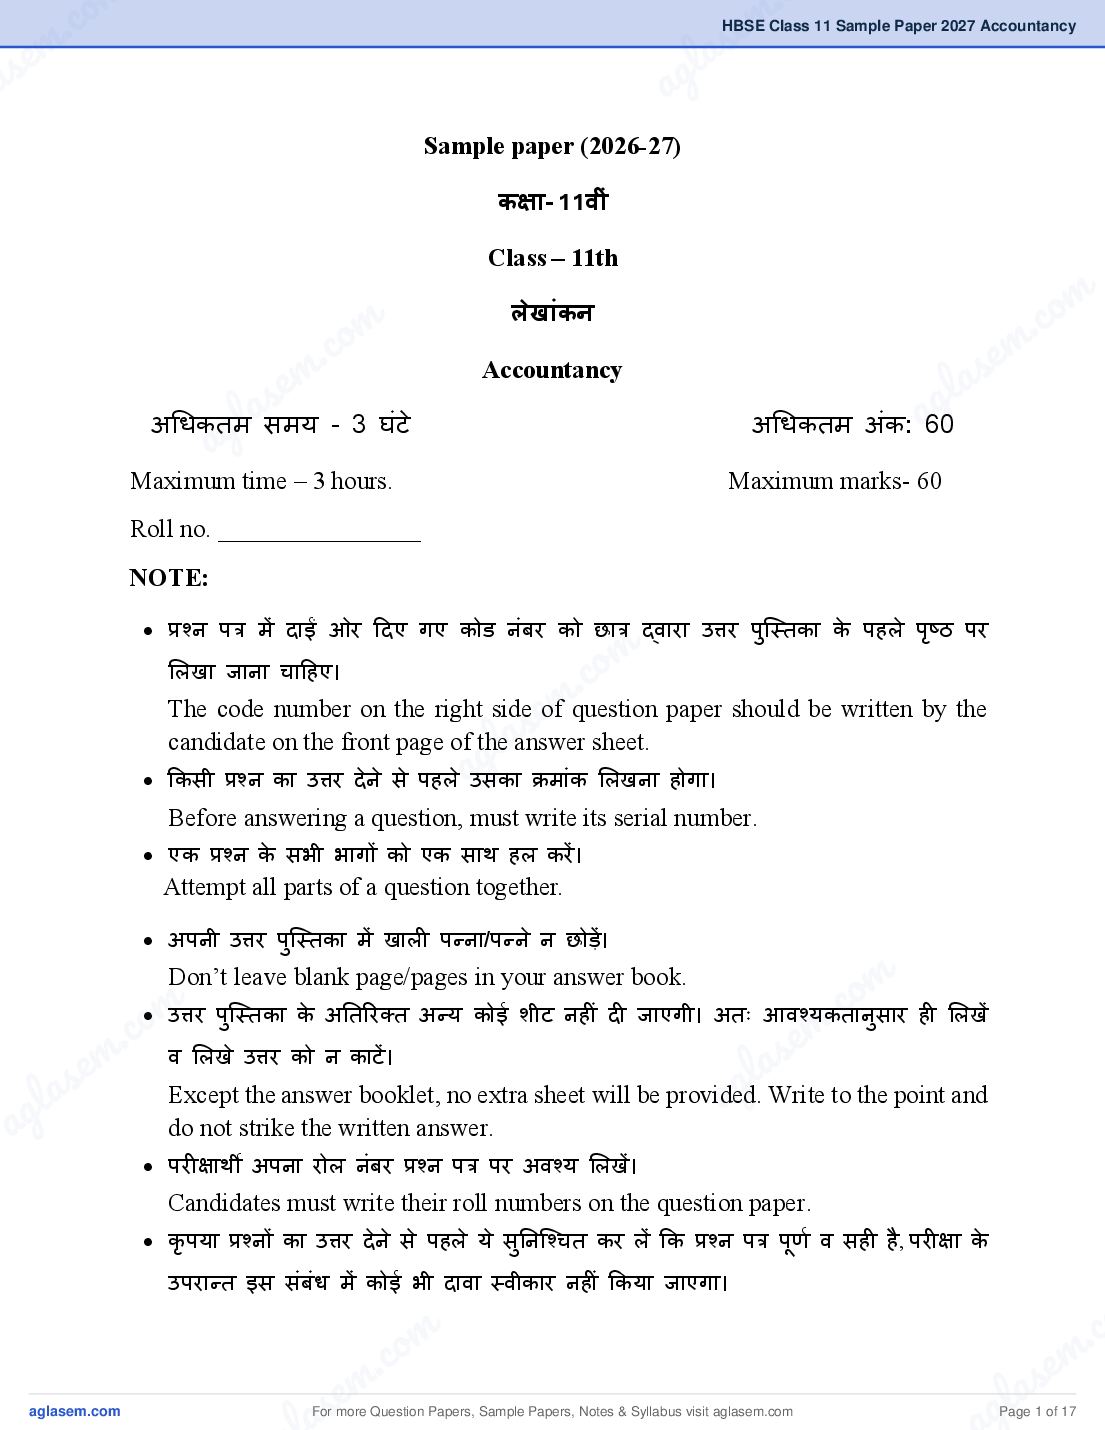
Sample paper (2026-27)
कक्षा- 11व ीं
Class – 11th
m
om
लेखाींकन
. co
.c e m
e m l a s
s
Accountancy
a
l समय - 3 घंटे a g
ag
अधिकतम अधिकतम अंक: 60
Maximum time – 3 hours. Maximum marks- 60
Roll no. ________________
NOTE:
• प्रश्न पत्र में दाईं ओर ददए गए कोड नंबर को छात्र द्वारा उत्तर पुस्ततका के पहले पष्ृ ठ पर
m
ललखा जाना चादहए। c. o
The code number on the right side eofmquestion paper should be written by the
s
candidate on the front page of thelaanswer sheet.
• ककसी प्रश्न का उत्तर देने से पहले a
g
उसका क्रमांक ललखना होगा।
Before answering a question, must write its serial number.
• एक प्रश्न के सभी भागों को एक साथ हल करें ।
Attempt all parts of a question together.
• अपनी उत्तर पुस्ततका में खाली पन्ना/पन्ने न छोड़ें।
o m
c
Don’t leave blank page/pages in your answer book.
•m . ुसार ही ललखें
c. o व ललखेु उत्तर को न काटें । m
उत्तर पस्ततका के अततररक्त अन्य कोई शीट नहीं दी जाएगी। अतः आवश्यकतान
m s e
s e g l a
gla Except the answer booklet, no extra sheet will be a Write to the point and
provided.
a do not strike the written answer.
• परीक्षाथी अपना रोल नंबर प्रश्न पत्र पर अवश्य ललखें।
Candidates must write their roll numbers on the question paper .
• कृपया प्रश्नों का उत्तर देने से पहले ये सतु नस्श्चत कर लें कक प्रश्न पत्र पर्
ू ण व सही है , परीक्षा के
उपरान्त इस संबंि में कोई भी दावा तवीकार नहीं ककया जाएगा।
m . c
c. o s e m
m a
se
For more Question Papers, Sample Papers, Notes & Syllabus visit
g l Page 1 of 17
Page 3
and the complete question paper. No complaint in this regard, will be entertained
after examination.
सामान्य ननर्दे श:
1. इस प्रश्न पत्र में कुल 30 प्रश्न शालमल हैं। सभी प्रश्न अतनवायण हैं।
2. प्रश्न संख्या 1 से 15 तक बहुववकल्पीय प्रश्न हैं स्जनमें से प्रत्येक के ललए
1 अंक तनिाणररत है ।
3. प्रश्न संख्या 16-21 तक अतत लघु उत्तरीय प्रश्न है , प्रत्येक 2 अंकों के प्रश्न
हैं।
4. प्रश्न संख्या 22-27 तक लघु उत्तरीय प्रश्न है , प्रत्येक 3 अंकों के प्रश्न हैं।
5. प्रश्न संख्या 28, 29 और 30 दीघण उत्तरीय प्रश्न है , प्रत्येक 5 अंकों के प्रश्न
हैं।
6. समग्र रूप से कोई ववकल्प नहीं है । हालााँकक, दो अंकों के 2 प्रश्नों में,
तीन अंकों के 2 प्रश्नों में और पााँच अंकों के सभी प्रश्नों में एक आ
ववकल्प प्रदान ककया गया है ।
General Instructions:
1. This question paper comprises of 30 questions in the question paper. All
For more Question Papers, Sample Papers, Notes & Syllabus visit Page 2 of 17
Page 4
. s e
em l a
as a g
questions are compulsory.
2. Question nos. 1 to 15 are very short answer type questions carrying 1
mark each.
3. Question nos. 16-21 are questions carrying 2 marks each.
m
om
4. Question nos. 22-27 are questions carrying 3 marks each.
. co
.c e m
e m
5. Question nos. 28, 29 and 30 are questions carrying 5 marks each.
l a s
l a s ag
ag
6. There is no overall choice. However, an internal choice has been provided
in
2 questions of two marks, 2 questions of three marks and questions of
Five
marks.
m
. co
em
1. Accounting starts
(a) Where Bok-keeping begins
l a s
(b) Where book- Keeping end, a g
(c) where books are not maintained at all
(d) After Preparing final Accounts.
लेखांकन का कायण आरं भ होता है.
m
(a) जहााँ, पुततपालन का कायण आरं भ होता है।
m c. o
c. o m
(b) जहााँ पुतत्पालन का कायण समाप्त होता है |
s e
s em (c) जहााँ पुततके रखी ही नहीं जाती है | la
gla (d) अंततम खाते बनने के बाद से ag
a
2. A person who owes money to the firm is Called.
(A) Debtor
(B) Creditor
m . c
c. o s e m
m a
se
For more Question Papers, Sample Papers, Notes & Syllabus visit
g l Page 3 of 17
Page 5
(c) None of these
वह व्यस्क्त स्जससे फमण ने रूपया लेना है_________ कहलाता है |
(A) दे नदार
(B) लेनदार
(c) पूततणकताण
(D) इनमें से से कोई नहीं
3. Accounting period concept means.
(A) A period of 12 months
(B) A period of 6 months
(c) Indefinite period
(d) Period fixed by Management
लेखा अवधि की अविारर्ा से आशय है
(A) 12 माह का समय
(B) 6 माह का समय
(c) अतनस्श्चत काल
(D) प्रबंिको द्वारा तनस्श्चत की गई अवधि
4. Depreciation for Business is
(A) Loss
(B) Income
(C) Gain
(D) Liability
For more Question Papers, Sample Papers, Notes & Syllabus visit Page 4 of 17
Page 6
. s e
em l a
as a g
ह्रास व्यवसाय के ललए है
(क) हातन
(B) आय
m
om . co
(C) लाभ
.c e m
m s
(D) दातयत्व
s e g l a
g l a a
5. Cost ofaGoods sold ₹ 1,50,000, closing stock ₹ 40,000, Opening stock ₹ 60,000. Amount
of Purchase will be:
(A) ₹ 130,000
(B) ₹ 170,000
(C) ₹ 50,000
(D) None of these
m
co
ववक्रय ककये गए माल की लागत ₹ 1,50,000, अंततम रहततया ₹ 40,000, प्रारं लभक रहततया ₹ 60,000, क्रय
.
em
ककये गए माल की कीमत होगी:
(A) ₹ 1,30,000
l a s
(B) ₹ 1,70,000
(C) ₹ 50,000 a g
(D) कोई भी नहीं
6. Outstanding Salary is:
(A) Real Account
(B) Personal Account
m
c. o
(C) Nominal Account
omवेतन है:
(D) None of them
c.अदत्त e m
em (A) वाततववक खाता la s
s
la (B) व्यस्क्तगत खाता ag
ag
(C) नाममात्र खाता
(D) इनमें से कोई नहीं
m . c
c. o s e m
m a
se
For more Question Papers, Sample Papers, Notes & Syllabus visit
g l Page 5 of 17
Page 7
(A) Principal Book
(B) Subsidiary Book
(C) Cash Book
(D) Purchase Book
खाताबही होती है:
(A) प्रिान बही
(B) सहायक बही
(C) रोकड़ बही
(D) क्रय बही
8. Assets sold on credit will be recorded in:
(A) Sales Book
(B) Journal Proper
(C) Sales Return Book
(D) Petty Cash Book
उिार बेची गई सम्पवत्त का लेखा होगा:
(A) ववक्रय बही
(B) रोजनामचा ववशेष
(C) ववक्रय वापसी बही
(D) लघु रोकड़ बही
9.Prepaid Rent is a ____________ Account.
पूवणदत्त ककराया ____________ खाता है।
10. सम्पवत्तयााँ - दातयत्व = ____________
Assets - Liabilities = ____________
11. Why are the rules of debit and credit same for both liability and capital?
दातयत्व और पूाँजी के ललए डेबबट और क्रेडडट के तनयम एक जैसे क्यों होते हैं?
12. what are contra Entries?
प्रतत-प्रववस्ष्टयााँ ककसे कहते हैं?
For more Question Papers, Sample Papers, Notes & Syllabus visit Page 6 of 17
Page 8
. s e
em l a
as a g
13. Assertion (A) : Bank reconciliation statement is not an account
Reason (R) : Bank reconciliation statement is prepared on a certain date.
(a) Both (A) and (R) are true and (R) is the correct explanation of (A)
m
(b) Both (A) and (R) are true but (R) is not the correct explanation of (A)
om . co
(c) (A) is true, but (R) is false
.c
(d) (A) is false, but (R) is true
e m
em वववरर् (Bank reconciliation statement) कोई खाता नहीं है। l a s
s g
कथन (A) : बैंक समािान
g a
कl समािान वववरर् एक तनस्श्चत ततधथ पर तैयार ककया जाता है।
a
a
कारर् (R) : बैं
(a) (A) और (R) दोनों सही हैं और (R), (A) की सही व्याख्या है।
(b) (A) और (R) दोनों सही हैं लेककन (R), (A) की सही व्याख्या नहीं है।
(c) (A) सही है, लेककन (R) गलत है।
m
(A) गलत है, लेककन (R) सही है।
o
(d)
c
14. Assertion(A): Trial balance is a part of double .entry system.
e m
l a s accounts.
agis the correct explanation of (A)
Reason (R): It helps in preparation of final
(a) Both (A) and (R) are true and (R)
(b) Both (A) and (R) are true but (R) is not the correct explanation of (A)
(c) (A) is true, but (R) is false
(d) (A) is false, but (R) is true
. कथन (A): तलपट दोहरी लेखा प्रर्ाली का एक दहतसा है।
m
c. o
कारर् (R): यह अंततम खाते तैयार करने में मदद करता है।
m
c. o (A) और (R) दोनों सही हैं और (R), (A) की सही व्याख्या है।
(a)
s e m
s em (b) (A) और (R) दोनों सही हैं लेककन (R), (A) की सही व्याख्या नहीं है। gla
gla (c) (A) सही है, लेककन (R) गलत है। a
a
(d) (A) गलत है, लेककन (R) सही है।
15. Assertion(A): Creation of provision is necessary and not voluntary
Reason(R): It is created even if there are no profits. Thus, it is a charge against profit.
m . c
c. o s e m
m a
se
For more Question Papers, Sample Papers, Notes & Syllabus visit
g l Page 7 of 17
Page 9
(b) Both (A) and (R) are true but (R) is not the correct explanation of (A)
(c) (A) is true, but (R) is false
(d) (A) is false, but (R) is true
कथन (A): प्राविान बनाना ज़रूरी है, यह तवैस्छछक नहीं है।
कारर् (R): इसे तब भी बनाया जाता है जब कोई लाभ न हो। इसललए, यह लाभ पर एक चाजण (अतनवायण
व्यय) है।
(a) (A) और (R) दोनों सही हैं और (R), (A) की सही व्याख्या है।
(b) (A) और (R) दोनों सही हैं लेककन (R), (A) की सही व्याख्या नहीं है।
(c) (A) सही है, लेककन (R) गलत है।
(d) (A) गलत है, लेककन (R) सही है।
16.Name any two external users of Accounting Information.
लेखांकन सूचना के ककन्हीं दो बाह्य उपयोगकताणओं के नाम ललखखए।
17. Distinguish between expenses and losses.
व्यय एवं हातन में अंतर कीस्जए।
18. What is Cash Basis of Accounting?
लेखांकन का नकद आिार ककसे कहते हैं?
19. State any 2 Advantages of Double Entry System.
दोहरा लेखा प्रर्ाली के कोई 2 लाभ ललखखए।
20.Explain Debit Voucher
डेबबट प्रमार्क के बारे में ललखखए
OR अथवा
What is Credit Voucher.
क्रेडडट प्रमार्क क्या है ?
For more Question Papers, Sample Papers, Notes & Syllabus visit Page 8 of 17
Page 10
. s e
em l a
as a g
21. What is the purpose of preparing Trading ?
व्यापाररक बनाने का क्या उद्दे श्य है ?
OR अथवा
m
m . co
What is the purpose of Profit & Loss Account?
c. oश्य है ?
लाभ हातन खाते का क्या उद्दे
se m
22. Explain thes em concept. g l a
la a
Matching
g
लमलान कीaअविारर्ा को समझाइए |
OR अथवा
Explain the Money Measurement concept.
मुद्रा मापन की अविारर्ा को समझाइए |-
m
co
23. मोदहत के तनम्न लेन-दे नों को लेखांकन समीकरर् में ददखाइए :
.
em
Mohit has the following transactions, prepare accounting equation :
l a s
g
₹
a
(a) Business started with cash ( नकद से व्यवसाय आरं भ ककया ) 1,75,000
(b) Purchased goods from Rohit ( रोदहत से माल खरीदा ) 50,000
Sold goods on credit to Manish (costing ₹ 17,500) ( मनीष को उिार बबक्री )
(c) 20,000
( लागत मूल्य 17,500 ₹ )
m
m c. o
c. (e)o Cash paid to Rohit in full settlement ( रोदहत को पूर्ण भुगतान में नकद रालश
(d) Purchased furniture for office use ( कायाणलय में प्रयोग के ललए फनीचर खरीदा ) 10,000
e m
em l a s
s
दी ) 48,500
l a a g
ag
(f) Cash received from Manish ( मनीष से नकद रालश प्राप्त की ) 20,000
(g) Rent paid ( ककराया ददया ) 1,000
(h) Cash withdrew for personal use ( तनजी प्रयोग के ललए रोकड़ तनकाली ) 3,000
m . c
c. o s e m
m a
se
For more Question Papers, Sample Papers, Notes & Syllabus visit
g l Page 9 of 17
Page 11
entered within the state of West Bengal, charging CGST and SGST @ 6% each :
2025
April 1 Purchased goods for ₹1,50,000 from S. Banerjee.
6 Sold goods for ₹2,50,000 to Aditya Sangma.
8 Returned goods to S. Banerjee for ₹10,000.
15 Aditya Sangma returned goods for ₹8,000.
18 Printing & stationery expenses of ₹5,000 paid in cash.
24 Goods withdrawn by Proprietor for personal use ₹20,000.
27 Goods destroyed by fire ₹15,000.
30 Payment made of balance amount of GST.
मक
ु ु ल रॉय एंड संस की बक्
ु स में एंट्रीज़ करें , यह मानते हुए कक सभी ट्रांज़ैक्शन पस्श्चम बंगाल राज्य के भीतर
हुए हैं और CGST व SGST दोनों 6% की दर से लगाए गए हैं:
2025
1 अप्रैल एस बेनजी से ₹1,50,000 का माल खरीदा।
6 आददत्य संगमा को ₹2,50,000 का माल बेचा।
8 एस बेनजी को ₹10,000 का माल वापस ककया।
15 आददत्य संगमा ने ₹8,000 का माल वापस ककया।
18 वप्रंदटंग और तटे शनरी का ₹5,000 का खचण नकद में चुकाया।
24 माललक ने तनजी इततेमाल के ललए ₹20,000 का माल तनकाला।
27 आग से ₹15,000 का माल नष्ट हो गया।
30 GST की बकाया रकम का भुगतान ककया।
For more Question Papers, Sample Papers, Notes & Syllabus visit Page 10 of 17
Page 12
. s e
em l a
as a g
25. तनम्नललखखत लेन-दे नों को गोववन्द ट्रे डसण नई ददल्ली की क्रय-वापसी बही में ललखखए यह मानते हुए कक
CGST 6% एवं SGST 6% है :
2025
m
जून 15: रािाकृष्र् एण्ड सन्स नई ददल्ली को ₹ 20,000 का माल वावपस ककया, व्यापाररक छूट 10%
co
•
om .
(डेबबट नोट नं. 140)
.c e m
e m
20: गोपाल सन्स, नई ददल्ली को, नमूने के अनुसार न होने के कारर्, ₹ 50,000 का माल वावपस
l a s
s
•
l a a g
g
ककया। (डेबबट नोट नं. 141)
a बीजक में त्रुदट होने के कारर् रघुबीर प्रसाद, नई ददल्ली से 10,000 ₹ छूट लमली। (डेबबट नोट नं.
• 25:
145)
Enter the following transactions in the Purchases Return Book of Govind Traders, New
Delhi, assuming CGST @ 6% and SGST @ 6% :—
2025
m
. co
• June 15: Returned goods to Radha Krishan & Sons, New Delhi for ₹ 20,000. Trade
em
Discount 10%. (Debit Note No. 140)
l a s
g
• 20: Returned goods to Gopalsons, New Delhi for ₹ 50,000, as the goods were not
a
according to sample. (Debit Note No. 141)
• 25: Allowance claimed from Raghubir Parshad, New Delhi, on account of mistake in
the invoice ₹ 10,000. (Debit Note No. 145)
26. 31 ददसम्बर 2025 को बैंक समािान वववरर् बनाइए। इस ततधथ को श्री दहमांशु की पास बुक 7,000 ₹
का शेष दशाण रही है।
m
c. o
(a) 1,000 ₹ का चेक एक ग्राहक द्वारा सीिे बैंक में जमा कराया गया।
m
c.(c)oददसम्बर माह में 3,000 ₹ के चेक तनगणलमत ककए थे स्जनमें से 2,000 ₹ के चेक sददसम्बर
m माह में भुगतान
(b) बैंक ने श्री दहमांशु को 700 ₹ का ब्याज क्रेडडट ककया।
e
s em के ललए प्रततुत नहीं हुए। g l a
gla a
a Prepare bank reconciliation statement as on December 31st, 20 25. On this day the pass
book of Mr. Himanshu showed a balance of ₹ 7,000.
(a) Cheque of ₹ 1,000 was directly deposited by a customer.
(b) The bank has credited Mr. Himanshu for ₹ 700 as interest.
m . c
c. o s e m
m a
se
For more Question Papers, Sample Papers, Notes & Syllabus visit
g l
Page 11 of 17
Page 13
for ₹ 2,000 were not presented during the month of December.
OR अथवा
रोकड़ बही के अनस
ु ार शेष की गर्ना करने के ललए तनम्न वववरर् की सहायता से 31 ददसंबर, 2025 को बैंक
समािान वववरर् बनाइये :
(a) 2,000 ₹ व 5,000 ₹ के दो चेक अक्टूबर में जमा करवाए गए थे लेककन बैंक द्वारा उन्हें ददसम्बर माह
तक जमा नहीं ककया गया।
(b) ददसम्बर में एक ग्राहक से प्राप्त 800 ₹ का चेक रोकड़ बही के बैंक ततंभ में तो उसी समय अलभललखखत
कर ददया लेककन उसे ददसम्बर माह में बैंक में जमा कराना भूल गए।
(c) नवम्बर में 10,000 ₹ के चेक तनगणलमत ककए गए लेककन ददसंबर तक भुगतान के ललए प्रततुत नहीं हुए।
(d) बैंक द्वारा तनवेश पर 1,000 ₹ के ब्याज का संग्रहर् केवल पास बुक में ही प्रववष्ट ककया गया।
पास बुक के अनुसार शेष 50,000 ₹ है।
From the following particulars prepare a bank reconciliation statement showing the
balance as per cash book on December 31st, 20 25 :
(a) Two cheques of ₹2,000 and ₹5,000 were paid into bank in October, but were not
credited by the bank up to the month of December.
(b) A cheque of ₹800 which was received from a customer was entered in the bank column
of the cash book in December but was omitted to be banked in December.
(c) Cheques for ₹10,000 were issued in November but not presented for payment upto
December 31st.
(d) Interest on investment ₹1,000 collected by bank appeared in the pass book.
Balance as per Pass book was ₹50,000.
27. कोहली का तलपट शेष नहीं लमल रहा था और उसमें ₹16,300 का डेबबट बैलेंस ज़्यादा आ रहा था। उसने
इस अंतर को सतपेंस अकाउं ट में डाल ददया और नीचे दी गई गलततयााँ पाईं:
(a) रजत से लमले ₹5,000 को कमल के डेबबट में ₹6,000 के तौर पर दजण ककया गया।
(b) एक कमणचारी को दी गई ₹2,000 के वेतन को उसके पसणनल अकाउं ट में ₹1,200 के तौर पर डेबबट ककया
गया।
(c) माललक द्वारा तवयं के इततेमाल के ललए तनकाले गए ₹1,000 के सामान को ववक्रय खाते में ₹1,600 के
तौर पर क्रेडडट ककया गया।
For more Question Papers, Sample Papers, Notes & Syllabus visit Page 12 of 17
Page 14
. s e
em l a
as a g
(d) मशीनरी पर लगाए गए ₹3,000 के मूल्य ह्रास को मशीनरी अकाउं ट में ₹300 के तौर पर दजण ककया
गया।
(e) ₹10,000 में बेची गई पुरानी कार को ववक्रय खाते में ₹6,000 के तौर पर क्रेडडट ककया गया।
गलततयों को ठीक करें और उचंत खाता बनाए।
o m
m . c
.co Account and discovered the following errors:
Trial balance of Kohli did not agree and showed an excess debit of ₹16,300. He put the
s e m
e m
difference to a Suspense
l a
la s a g
g
(a) Cash received from Rajat ₹5,000 was posted to the debit of Kamal as ₹6,000.
a paid to an employee ₹2,000 were debited to his personal account as ₹1,200.
(b) Salaries
(c) Goods withdrawn by proprietor for personal use ₹1,000 were credited to Sales Account
as ₹1,600.
(d) Depreciation provided on Machinery ₹3,000 was posted to Machinery Account as ₹300.
(e) Sale of old car for ₹10,000 was credited to Sales Account as ₹6,000.
Rectify the errors and prepare Suspense Account.
m
c. o
28. जुलाई, 2025 के ललए M/s अनालमका की डबल e m कैश बुक में तनम्नललखखत लेन-देन दजण करें:
l a s कॉलम
ag ₹
1 जुलाई नकद से व्यापार शुरू ककया 50,000
3 जुलाई ICICI में बैंक खाता खोला 30,000
5 जुलाई नकद में माल खरीदा 10,000
10 जल
ु ाई नकद में ऑकफस का सामान खरीदा 5,000
o m
m 7,000 . c
c. o 15 जल
ु ाई रुहान को उिार पर माल बेचा और चेक प्राप्त ककया
s em
s em 18 जुलाई la8,000
la 20 जुलाई ag
नकद बबक्री
ag रोहन का चेक बैंक में जमा ककया
22 जुलाई चेक द्वारा ढुलाई का भुगतान ककया 500
25 जुलाई व्यस्क्तगत उपयोग के ललए नकद तनकाला 2,000
30 जुलाई चेक द्वारा ककराया चुकाया 1,000
m . c
c. o s e m
m a
se
For more Question Papers, Sample Papers, Notes & Syllabus visit
g l
Page 13 of 17
Page 15
Date Particulars ₹
July 1 Commenced Business with cash 50,000
July 3 Opened Bank Account with ICICI 30,000
July 5 Purchased goods for cash 10,000
July 10 Purchased office equipment for cash 5,000
July 15 Sold goods on credit to Ruhan and received a cheque 7,000
July 18 Cash sales 8,000
July 20 Rohan's cheque deposited into Bank
July 22 Paid cartage by cheque 500
July 25 Cash withdrawn for personal use 2,000
July 30 Paid rent by cheque 1,000
OR अथवा
लघु रोकड़ बही के पांच लाभ ललखखए |
Write the five advantages of petty cash book.
29. M/s लोकेश फैबिक्स ने 1 अप्रैल, 2015 को ₹1,00,000 में एक टे क्सटाइल मशीन खरीदी। 1 जल
ु ाई, 2016
को ₹2,50,000 की कीमत वाली एक और मशीन खरीदी गई। 1 अप्रैल, 2015 को खरीदी गई मशीन को 1
अक्टूबर, 2019 को ₹25,000 में बेच ददया गया। कंपनी सीिी रे खा पद्ितत से 15% वावषणक की दर से
मूल्यह्रास लगाती है। 31 माचण, 2020 को समाप्त होने वाले वषण के ललए मशीनरी खाता और मशीनरी तनपटान
खाता तैयार करें ।
For more Question Papers, Sample Papers, Notes & Syllabus visit Page 14 of 17
Page 16
. s e
em l a
as a g
M/s Lokesh Fabrics purchased a Textile Machine on April 1st, 2015 for ₹1,00,000. On July
1st, 2016 another machine costing ₹2,50,000 was purchased. The machine purchased on
April 01, 2015 was sold for ₹25,000 on October 1st 2019. The company charges
depreciation @ 15% p.a. on straight line method. Prepare machinery account and
machinery disposal account for the year ended March 31st, 2020.
m
om
OR अथवा
. co
.c e m
e m
मूल्यह्रास क्या होता है ? इसके ववलभन्न कारर् क्या है ?
l a s
l a s ag
ag
What is depreciation? What are its various causes?
30. लाभ और हातन खाता क्या है? इसके महत्त्व के कोई चार बबन्दु बताइए। 5
What is a Profit and Loss Account? State any 4 Points of its importance.
OR अथवा
m
co
तनम्नललखखत शेषों से 31 माचण, 2025 को व्यापाररक खाता और लाभ और हातन खाता और तुलन पत्र तैयार
.
em
करें ।
l a s
g
From the following balances, prepare the trading and profit and loss account and balance sheet as
on March 31, 2025. a
डेबिट शेष मूल्य Amount क्रेडडट शेष मूल्य Amount
Debit balance रुपये Rs. Credit balance रुपये Rs.
आहरर् Drawing पूाँजी capital 150000
m
6300
m
बैंक में नकद cash at 13870
c. o
छूट Discount 2980
c. o bank
s e m
em la
प्राप्य बबल bill 1860 ऋर् Loan 15000
las ag1450
g
receivable
a भूलम और भावन 42580 क्रय वापसी
Land and building Purchase Return
फनीचर 5130 डूबत ऋर्ों के ललए 4650
Furniture संचय Reserve for
bad debts
छूट Discount 3960 लेनदार creditor 18670
m . c
c. o s e m
m a
se
For more Question Papers, Sample Papers, Notes & Syllabus visit
g l
Page 15 of 17
Page 17
ु क Bank 100 ववक्रय 2,81,500
charges sales
वेतन salary 6420
क्रय purchased 199080
तटॉक (प्रारस्म्भक) 60220
stock (opening)
ववक्रय वापसी sales 1870
return
माल भाड़ा carriage 5170
ककराया और कर 7680
Rent and Taxes
सामान्य व्यय 3630
general expenses
प्लांट और मशीन 31640
Plant and machinery
पुततक ऋर् book 82740
debts
डूबत ऋर् bad debts 1250
बीमा insurance 750
474250 474250
समायोजन
1. अंततम तटॉक रु.70,000
2. अशोध्य और संददग्ि ऋर्ों के ललए 10% की दर से एक ररजवण बनाएं
3. बीमा पव
ू द
ण त्त रु.50
Adjustments
1. Closing Stock Rs.70,000
2. Create a reserve for bad and doubtful debts @ 10% on book debts
3. Insurance Prepaid Rs.50
For more Question Papers, Sample Papers, Notes & Syllabus visit Page 16 of 17
Page 18
. s e
em l a
as a g
m
om . co
.c e m
e m l a s
l a s ag
ag
m
. co
s em
g l a
a
m
m c. o
c. o s e m
s em la
gla ag
a
m . c
c. o s e m
m a
se
For more Question Papers, Sample Papers, Notes & Syllabus visit
g l
Page 17 of 17
Document Details
| Board / Org | Haryana Board |
| Exam | Class 11 |
| Type | Sample Paper |
| Pages | 17 |
| Updated | 03 Nov 2026 |