CBSE Class 10 Question Paper 2025 Solution Elements of Book Keeping and Accountancy
Finished viewing? Save it for later —
Download CBSE Class 10 Question Paper 2025 Solution Elements of Book Keeping and Accountancy (PDF · 11 pages)About CBSE Class 10 Question Paper 2025 Solution Elements of Book Keeping and Accountancy
CBSE Class 10 Question Paper 2025 Solution Elements of Book Keeping and Accountancy is available here for free download. Published by CBSE for Class 10, this solution can be viewed online or downloaded as a PDF (11 pages). Candidates preparing for Class 10 can use CBSE Class 10 Question Paper 2025 Solution Elements of Book Keeping and Accountancy to understand the exam pattern, the type of questions asked, and the overall difficulty level.
Frequently Asked Questions
How can I download CBSE Class 10 Question Paper 2025 Solution Elements of Book Keeping and Accountancy?
Open this page and click the Download button to save CBSE Class 10 Question Paper 2025 Solution Elements of Book Keeping and Accountancy as a PDF. It is completely free on AglaSem Docs.
Is CBSE Class 10 Question Paper 2025 Solution Elements of Book Keeping and Accountancy free to download?
Yes. CBSE Class 10 Question Paper 2025 Solution Elements of Book Keeping and Accountancy can be viewed online and downloaded as a PDF free of cost on AglaSem Docs.
How many pages does CBSE Class 10 Question Paper 2025 Solution Elements of Book Keeping and Accountancy have?
CBSE Class 10 Question Paper 2025 Solution Elements of Book Keeping and Accountancy contains 11 pages, which you can read online or download together as a single PDF.
Where can I find more Class 10 study material?
You can find more Class 10 question papers, sample papers, syllabus, and answer keys on AglaSem Docs.
CBSE Class 10 Question Paper 2025 Solution Elements of Book Keeping and Accountancy – Text
Read the full text of this solution below — useful to quickly search, copy and reference the content online without downloading the PDF.
📄 View text version (11 pages)
Page 1
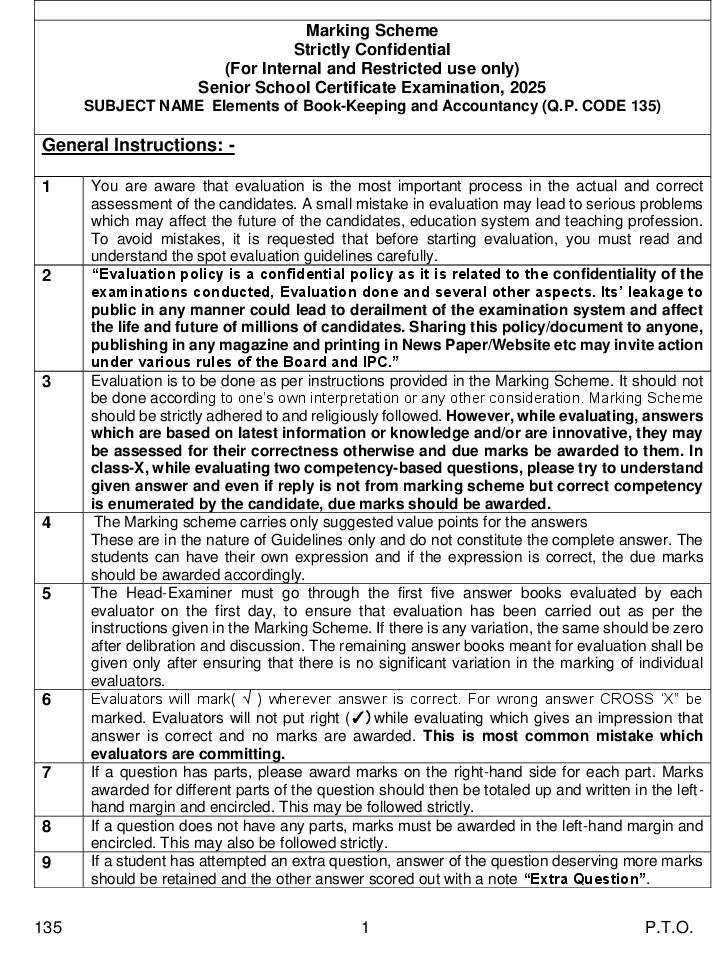
Strictly Confidential
(For Internal and Restricted use only)
Senior School Certificate Examination, 2025
SUBJECT NAME Elements of Book-Keeping and Accountancy (Q.P. CODE 135)
General Instructions: -
1 You are aware that evaluation is the most important process in the actual and correct
assessment of the candidates. A small mistake in evaluation may lead to serious problems
which may affect the future of the candidates, education system and teaching profession.
To avoid mistakes, it is requested that before starting evaluation, you must read and
understand the spot evaluation guidelines carefully.
2 “Evaluation policy is a confidential policy as it is related to the confidentiality of the
examinations conducted, Evaluation done and several other aspects. Its’ leakage to
public in any manner could lead to derailment of the examination system and affect
the life and future of millions of candidates. Sharing this policy/document to anyone,
publishing in any magazine and printing in News Paper/Website etc may invite action
under various rules of the Board and IPC.”
3 Evaluation is to be done as per instructions provided in the Marking Scheme. It should not
be done according to one’s own interpretation or any other consideration. Marking Scheme
should be strictly adhered to and religiously followed. However, while evaluating, answers
which are based on latest information or knowledge and/or are innovative, they may
be assessed for their correctness otherwise and due marks be awarded to them. In
class-X, while evaluating two competency-based questions, please try to understand
given answer and even if reply is not from marking scheme but correct competency
is enumerated by the candidate, due marks should be awarded.
4 The Marking scheme carries only suggested value points for the answers
These are in the nature of Guidelines only and do not constitute the complete answer. The
students can have their own expression and if the expression is correct, the due marks
should be awarded accordingly.
5 The Head-Examiner must go through the first five answer books evaluated by each
evaluator on the first day, to ensure that evaluation has been carried out as per the
instructions given in the Marking Scheme. If there is any variation, the same should be zero
after delibration and discussion. The remaining answer books meant for evaluation shall be
given only after ensuring that there is no significant variation in the marking of individual
evaluators.
6 Evaluators will mark( √ ) wherever answer is correct. For wrong answer CROSS ‘X” be
marked. Evaluators will not put right (✓)while evaluating which gives an impression that
answer is correct and no marks are awarded. This is most common mistake which
evaluators are committing.
7 If a question has parts, please award marks on the right-hand side for each part. Marks
awarded for different parts of the question should then be totaled up and written in the left-
hand margin and encircled. This may be followed strictly.
8 If a question does not have any parts, marks must be awarded in the left-hand margin and
encircled. This may also be followed strictly.
9 If a student has attempted an extra question, answer of the question deserving more marks
should be retained and the other answer scored out with a note “Extra Question”.
135 1 P.T.O.
Page 2
once.
11 A full scale of marks __________(example 0 to 80/70/60/50/40/30 marks as given in
Question Paper) has to be used. Please do not hesitate to award full marks if the answer
deserves it.
12 Every examiner has to necessarily do evaluation work for full working hours i.e., 8 hours
every day and evaluate 20 answer books per day in main subjects and 25 answer books
per day in other subjects (Details are given in Spot Guidelines).This is in view of the reduced
syllabus and number of questions in question paper.
13 Ensure that you do not make the following common types of errors committed by the
Examiner in the past:-
● Leaving answer or part thereof unassessed in an answer book.
● Giving more marks for an answer than assigned to it.
● Wrong totaling of marks awarded on an answer.
● Wrong transfer of marks from the inside pages of the answer book to the title page.
● Wrong question wise totaling on the title page.
● Wrong totaling of marks of the two columns on the title page.
● Wrong grand total.
● Marks in words and figures not tallying/not same.
● Wrong transfer of marks from the answer book to online award list.
● Answers marked as correct, but marks not awarded. (Ensure that the right tick mark is
correctly and clearly indicated. It should merely be a line. Same is with the X for
incorrect answer.)
● Half or a part of answer marked correct and the rest as wrong, but no marks awarded.
14 While evaluating the answer books if the answer is found to be totally incorrect, it should be
marked as cross (X) and awarded zero (0)Marks.
15 Any unassessed portion, non-carrying over of marks to the title page, or totaling error
detected by the candidate shall damage the prestige of all the personnel engaged in the
evaluation work as also of the Board. Hence, in order to uphold the prestige of all concerned,
it is again reiterated that the instructions be followed meticulously and judiciously.
16 The Examiners should acquaint themselves with the guidelines given in the “Guidelines for
Spot Evaluation” before starting the actual evaluation.
17 Every Examiner shall also ensure that all the answers are evaluated, marks carried over to
the title page, correctly totaled and written in figures and words.
18 The candidates are entitled to obtain photocopy of the Answer Book on request on payment
of the prescribed processing fee. All Examiners/Additional Head Examiners/Head
Examiners are once again reminded that they must ensure that evaluation is carried out
strictly as per value points for each answer as given in the Marking Scheme.
135 2
Page 3
MARKING SCHEME
Elements of Book-Keeping and Accountancy
SECTION A
(Objective Type Questions) (30 Marks)
1. (B) It is intended to benefit the current period. 1
OR
(A) Revenue Expenditure 1
2. (D) Inflation 1
OR
(B) Assets a/c 1
3. (C) Assertion (A) is true, but Reason (R) is false. 1
4. (C) ₹ 8,400 1
OR
(B) ₹ 22,500 1
5. (D) Both Assertion (A) and Reason (R) are true and Reason (R) is the correct explanation
of preparing Bank Reconciliation Statement. 1
OR
(D) Dr balance in cash book 1
6. (A) Statement-I is correct, but statement-II is incorrect. 1
OR
(A) on the purchase price of the assets 1
SECTION B
135 3 P.T.O.
Page 4
7. (D) 16th August, 2024. 1
8. (D) Both the statements are false. 1
9. (B) No account 1
10. (B) Direct expenses 1
OR
(C) Intangible Asset 1
11. (A) B/R 1
OR
(B) 2nd November 1
12. (B)Balance sheet is prepared for a particular date 1
13. (A) Both the statements are true. 1
14. (B) Profit and Loss a/c 1
OR
(D) Accurate. 1
15. (C) three 1
16. (C) Small sized sole trader business 1
17. (A) Statement-I is true and statement-II is false 1
18. (A) Personal 1
19. Deferred revenue expenditure refers to those expenses which will be incurred in
the current accounting period but the benefits of the expenses will be applicable
over several accounting periods. Example :
135 4
Page 5
2. Advertising exp.
3. Research and development cost
4. Pre opening exp for a new business 3
20. (a) Deferred Revenue Expenditure
(b) Capital Expenditure
(c) Revenue Expenditure 3
21. No, Depreciation is not a result of fluctuations in the value of fixed assets. Since
the fluctuation is concerned with the market price of a fixed asset whereas the
depreciation is concerned with the historical cost (Cost of acquiring fixed
asset.) 3
22. Books of Ajay 3
Date Particulars L.F Dr. Cr.
Amount Amount
(₹) (₹)
30/8/24
Kusum’s A/c Dr. 50,000
To Sale A/c 50,000
(Being goods sold)
30/8/24
Bills Receivable A/c Dr. 50,000
To Kusum’s A/c 50,000
(Being bill accepted)
4/11/24 Cash A/c Dr. 50,000
To Bills receivable A/c 50,000
(Being bill amt received)
OR
Books of Golu 3
Date Particulars L.F Dr. Cr.
Amount Amount
(₹) (₹)
135 5 P.T.O.
Page 6
To Shyam’s A/c 60,000
(Being goods purchased)
14/3/24 Shyam’s A/c Dr. 60,000
To Bills Payable A/c 60,000
(Being bills accepted)
19/10/24 Bills Payable A/c Dr. 60,000
To Cash A/c 60,000
(Being bill amt paid)
23. Books of Vishal 4
Date Particulars L.F Dr. Cr.
Amount Amount
(₹) (₹)
5/1/24 Bills Receivable A/c Dr. 7,000
To Manju’s A/c 7,000
(Being bill accepted)
5/1/24 Bank A/c Dr. 6,790
Discount A/c Dr. 210
To Bills receivable A/c
( Being bill discounted @ 12% p.a.) 7,000
Note : 7000 × 12/100 ×3/12 = 210
OR
Books of Manju 4
Date Particulars L.F Dr. Cr.
Amount Amount
(₹) (₹)
5/1/24 Vishal’s A/c Dr. 7,000
To Bills Payable A/c 7,000
(Being bill accepted)
10/4/24 Bills Payable A/c Dr. 7,000
To Cash A/c 7,000
(Being bill amt. paid)
24. Bank Reconciliation statement as on 31/3/24 4
Particulars Dr. Cr.
Amt. Amt.
135 6
Page 7
Overdraft Balance as per Pass Book Dr. 16,500
Add Cheques issued but not presented 8,750 8,750
25,250
Less Cheque deposited but not collected 30,500
Bank charges 200 30,700
Balance as Per Cash Book (cr.) 5,450
OR
Bank Reconciliation statement as on 31/3/24 3
Particulars Plus Minus
item item
(₹) (₹)
Balance as per Pass Book (cr) 10,000
Cheque recorded twice 350
Excess credit for cash deposit 9
Under casting of withdrawal column 100
Balance as per Cash Book (Dr.) 10,241
10,350 10,350
25. Statement of Profit and loss for the year ended 31/3/2024. 4
Particulars ₹
Closing Capital 33,800
(+) Drawings 9,600
(–) Additional Capital (4,000)
(–) Opening Capital (30,400)
Profit during the year 9,000
26. Assets listed in order of liquidity in a Balance Sheet : 4
(i) Cash in hand
(ii) Sundry debtors
(iii) Machinery
(iv) Land and Building
27. Need for Charging Depreciation & Examples
135 7 P.T.O.
Page 8
1. Matching Principle: Ensures expenses are matched with revenue generated.
2. Accurate Financial Position: Reflects true value of assets.
3. Asset Replacement: Helps in planning for future asset replacement.
4. Tax Benefits: Depreciation reduces taxable income.
Examples of Fixed Assets
1. Building
2. Machinery
Statement of affairs as on 31/3/23 6
Amount Amount
Liabilities (₹) Assets (₹)
Sundry Creditors 15,000 Cash 1,000
Capital (Balance fig.) 1,19,000 Sundry debtors 39,000
Stock 34,000
Plant and Machinery 60,000
1,34,000 1,34,000
Statement of affairs as on 31/03/24
Amount Amount
Liabilities (₹) Assets (₹)
Sundry Creditors 19,900 Cash 900
Capital (Balance fig.) 1,38,000 Sundry debtors 45,000
Stock 32,000
Plant and Machinery 80,000
1,57,900 1,57,900
135 8
Page 9
Particulars ₹
Closing Capital 1,38,000
(+) Drawings 36,000
(–) Additional Capital (10,000)
(–) Opening Capital (1,19,000)
Net Profit 45,000
28. Bank Reconciliation statement as on 31/3/24 6
Particulars Dr. Cr.
Amount Amount
(₹) (₹)
Balance as per Pass Book Dr. 7,700
Add Cheques issued but not presented 3,500
Directly deposited by customer 4,800 8,300
16,000
Less Cheque deposited but not collected 2,600
Int on bank loan debited by bank 554
Payment side of Cash Book -
Totalled short 1,000 4,154
Overdraft balance as per Cash Book cr.) 11,846
29. Dr. Washing Machine A/C Cr. 6
Date Particulars Amt Date Particulars Amt
(₹) (₹)
2022 2023 By Dep. A/c
To Bank A/c 75,000 7,500
1/4/22 31/3/23 By Bal c/d
(5 × 15,000) 67,500
75,000 75,000
2023 2024 By Dep A/c
To bal b/d 67,500 7,500
1/4 31/3 By Bal c/d
60,000
135 9 P.T.O.
Page 10
1/4 31/3 By Bal c/d 52,500
2025
To bal b/d 52,500
1/4
30. Dr. Trading and Profit &Loss A/C as on 31/3/24 Cr.
6 4
Particular Amount Particular Amount
(₹) (₹)
To opening stock 2,00,000 By Sales 14,50,000
To purchase 9,50,000 By Closing stock 60,000
To wages 5,00,000 By Gross Loss 1,55,000
To carriage 15,000
16,65,000 16,65,000
To Net loss 1,55,000 By Commission 10,000
To Bad debts 10,000 By Net Loss 2,20,000
To Rent 45,000
To Sundry Exp. 20,000
2,30,000 2,30,000
Balance Sheet as on 31/03/2024
Amount Amount
Liabilities (₹) Assets (₹)
Capital 12,00,000 Machinery 4,00,000
135 10
Page 11
(–) Net loss 2,20,000 8,90,000 Debtors 2,70,000
Creditors 1,40,000 Cash 1,40,000
Closing Stock 70,000
10,30,000 10,30,000
135 11 P.T.O.
Document Details
| Board / Org | CBSE |
| Exam | Class 10 |
| Type | Solution |
| Pages | 11 |
| Updated | 24 Sep 2026 |