HBSE Class 11 Sample Paper 2026 Accountancy
Finished viewing? Save it for later —
Download HBSE Class 11 Sample Paper 2026 Accountancy (PDF · 12 pages)About HBSE Class 11 Sample Paper 2026 Accountancy
HBSE Class 11 Sample Paper 2026 Accountancy is available here for free download. Published by Haryana Board for Class 11, this sample paper can be viewed online or downloaded as a PDF (12 pages). Candidates preparing for Class 11 can use HBSE Class 11 Sample Paper 2026 Accountancy to understand the exam pattern, the type of questions asked, and the overall difficulty level.
Frequently Asked Questions
How can I download HBSE Class 11 Sample Paper 2026 Accountancy?
Open this page and click the Download button to save HBSE Class 11 Sample Paper 2026 Accountancy as a PDF. It is completely free on AglaSem Docs.
Is HBSE Class 11 Sample Paper 2026 Accountancy free to download?
Yes. HBSE Class 11 Sample Paper 2026 Accountancy can be viewed online and downloaded as a PDF free of cost on AglaSem Docs.
How many pages does HBSE Class 11 Sample Paper 2026 Accountancy have?
HBSE Class 11 Sample Paper 2026 Accountancy contains 12 pages, which you can read online or download together as a single PDF.
Where can I find more Class 11 study material?
You can find more Class 11 question papers, sample papers, syllabus, and answer keys on AglaSem Docs.
HBSE Class 11 Sample Paper 2026 Accountancy – Text
Read the full text of this sample paper below — useful to quickly search, copy and reference the content online without downloading the PDF.
📄 View text version (12 pages)
Page 1
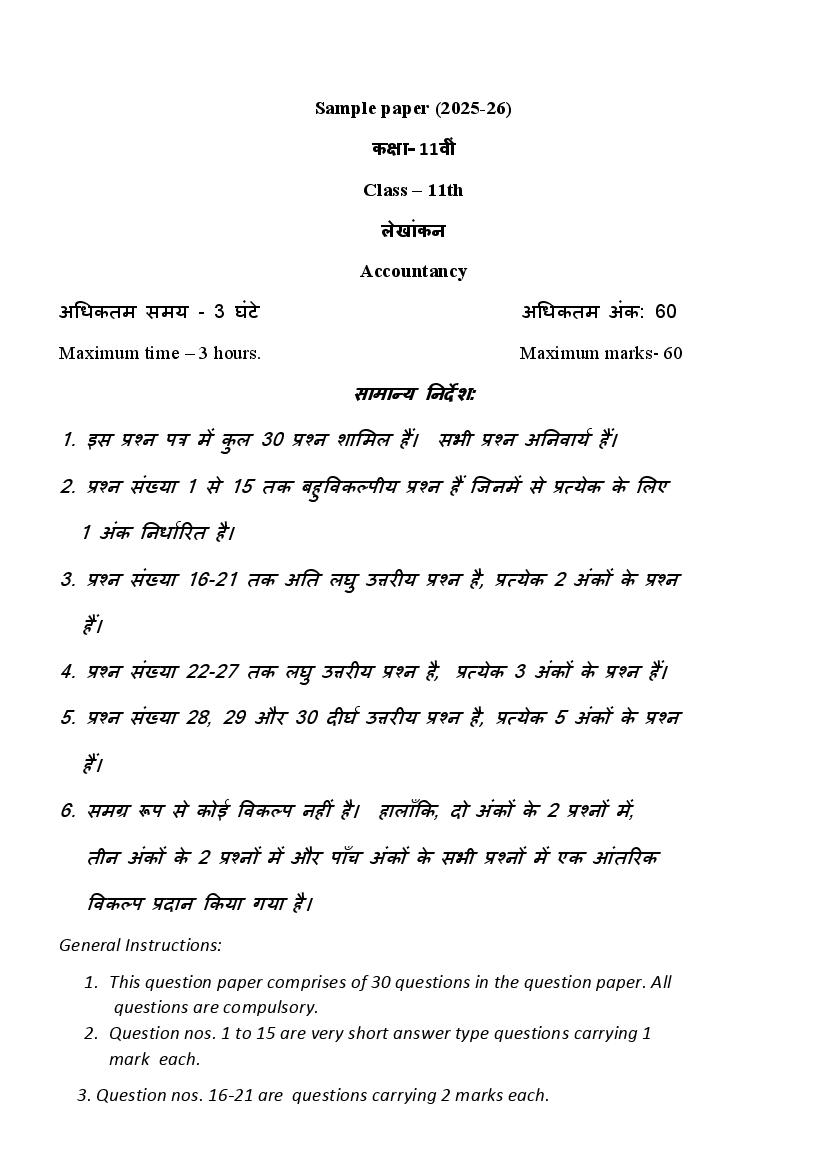
कक्षा- 11व ीं
Class – 11th
लेखाींकन
Accountancy
अधिकतम समय - 3 घंटे अधिकतम अंक: 60
Maximum time – 3 hours. Maximum marks- 60
सामान्य ननर्दे श:
1. इस प्रश्न पत्र में कुल 30 प्रश्न शाममल हैं। सभी प्रश्न अननवायय हैं।
2. प्रश्न संख्या 1 से 15 तक बहुववकल्पीय प्रश्न हैं जिनमें से प्रत्येक के मलए
1 अंक ननिायरित है।
3. प्रश्न संख्या 16-21 तक अनत लघु उत्तिीय प्रश्न है, प्रत्येक 2 अंकों के प्रश्न
हैं।
4. प्रश्न संख्या 22-27 तक लघु उत्तिीय प्रश्न है, प्रत्येक 3 अंकों के प्रश्न हैं।
5. प्रश्न संख्या 28, 29 औि 30 दीघय उत्तिीय प्रश्न है, प्रत्येक 5 अंकों के प्रश्न
हैं।
6. समग्र रूप से कोई ववकल्प नहीं है। हालााँकक, दो अंकों के 2 प्रश्नों में,
तीन अंकों के 2 प्रश्नों में औि पााँच अंकों के सभी प्रश्नों में एक आंतरिक
ववकल्प प्रदान ककया गया है।
General Instructions:
1. This question paper comprises of 30 questions in the question paper. All
questions are compulsory.
2. Question nos. 1 to 15 are very short answer type questions carrying 1
mark each.
3. Question nos. 16-21 are questions carrying 2 marks each.
Page 2
5. Question nos. 28, 29 and 30 are questions carrying 5 marks each.
6. There is no overall choice. However, an internal choice has been provided in
2 questions of two marks, 2 questions of three marks and questions of Five
marks.
1. Tangible Assets do not include 1
(A) Goodwill (B) furniture (C)stock (D) cash
मूतय सम्पवत्त नहीं है
(A) ख्यानत (B) फनीचि (C) स्टॉक (D) िोकड़
2. Voucher is prepared for 1
(A) Cash received and paid (B) Cash/credit Sales
(C) Cash/credit Purchase (D) All of the above
वाउचि ननम्न के मलए तैयाि ककया िाता है
(A) िोकड़ प्राप्त औि भुगतान (B) िोकड़/क्रेडिट बबक्री
(C) िोकड़/क्रेडिट खिीद (D) उपिोक्त सभी
3. Rohan has returned goods worth ₹5000 to Radheyshyam as he found it defective,
which document will be prepared by Radheyshyam? 1
(A) Invoice/Bill (B) Debit Note (C) credit voucher (D) Credit Note
िोहन ने त्रुटटपूर्य होने के कािर् ₹5000 का माल िािेश्याम को वावपस ककया है।
िािेश्याम, द्वािा कौन सा प्रपत्र तैयाि ककया िाएगा?
(A) बीिक/बबल (B) नामे पत्र (C) क्रेडिट प्रमार्क (D) िमा पत्र
4. A Ledger is a 1
(A) Principal Book (B) Subsidiary Book (C) Cash Book (D) Purchase book
लेिि है एक
Page 3
5. Salary due for the month of March will appears in _______ side of Cash Book 1
(A) Receipt (B) Payment (C) Contra (D) None of the these
माचय के माह का दे य वेतन िोकड़ पुस्तक के_______पक्ष में मलखा िाएगा।
(A) प्राजप्त (B) भग
ु तान (C) ववपिीत (D) इनमे में कोई नहीं
6. Asset sold on credit will be recorded in 1
(A) sales book (B) Journal Proper (C) Sales Return Busk (D) Petty Cash Book
उिाि बेचीं गई सम्पवत्त का लेखा होगा
(A) ववक्रय बही (B) िोिनामचा ववशेष (C) ववक्रय वापसी बही (D) लघु िोकड़ बही
7. Assets - Liabilities = 1
सम्पनतयााँ - दानयत्व =
8. Premium paid on the life Insurance policy of the propriter will be debited to____ 1
स्वामी के िीवन बीमा पॉमलसी के मलए चुकाए गए प्रीममयम को िेबबट ककया िाएगा
_____________खाते में।
9. Cashbook maintained to record small expenses is called_______ 1
छोटे खचो के लेखांकन के मलए बनाई गई िोकड़ बही को______ कहा िाता है|
10. What are artificial personal accounts? give one example. 1
कृबत्रम व्यजक्तगत खाते ककसे कहते हैं ? एक उदाहिर् दीजिए|
11. What do we come to know by preparing trading account? 1
व्यापारिक खाता बनाने से हमें क्या ज्ञात होता है?
12. Give the formula to calculate cost of goods sold. 1
ववक्रय ककये गए माल की लागत को ज्ञात किने का सूत्र दीजिए |
13. अमभकथन (A) : िनयल को मूल प्रववजटट की पुस्तकें कहा िाता है। 1
कािर् (R) : लेिि को अंनतम प्रववजटट की पस्
ु तकें कहा िाता है।
Page 4
(अ) अमभकथन (A) औि कािर् (R) सही हैं लेककन कािर् (R) अमभकथन (A)
का सही स्पटटीकिर् नहीं है ।
(ब) कािर् (R) औि अमभकथन (A) दोनों सही हैं औि कािर् (R) अमभकथन (A)
की सही व्याख्या है ।
(स) केवल अमभकथन (A) सही है ।
(द) अमभकथन (A) औि कािर् (R) दोनों सही नहीं हैं।
Assertion(A): Journal is called the books of original entry.
Reason (R): Ledger is called the books of final entry.
Choose the Correct Option
(a) Assertion (A) and Reason (R ) are correct but Reason (R ) is not the correct
explanation of Assertion(A ).
(b) Both Reason (R ) and Assertion (A ) are correct and Reason (R ) is the correct
explanation of Assertion (A ).
(c) Only Assertion (A ) is correct.
(d)Both Assertion (A ) and Reason (R ) are not correct.
14. अमभकथन (A) : व्यवसाय के स्वाममयों के व्यजक्तगत लेन-दे न को पुस्तकों में दिय नहीं
ककया िाता है। 1
कािर् (R): व्यापाि इकाई अविािर्ा के अनुसाि, प्रत्येक व्यावसानयक उद्यम को
मामलकों से अलग लेखा इकाई के रूप में माना िाता है ।
सही ववकल्प चुनें
(अ) अमभकथन (A) औि कािर् (R) सही हैं लेककन कािर् (R) अमभकथन (A) का सही
स्पटटीकिर् नहीं है।
Page 5
व्याख्या है।
(सी) केवल अमभकथन (A) सही है।
(द) अमभकथन (A) औि कािर् (R) दोनों सही नहीं हैं।
Assertion(A): Personal transactions of the owners of the business are not
recorded in the books.
Reason (R): According to the business entity concept, each business enterprise
is considered as an accounting unit separate from Owners.
Choose the Correct Option
(a) Assertion (A) and Reason (R ) are correct but Reason (R ) is not the correct
explanation of Assertion(A ).
(b) Both Reason (R ) and Assertion (A ) are correct and Reason (R ) is the
correct explanation of Assertion (A ).
(c) Only Assertion (A ) is correct.
(d) Both Assertion (A ) and Reason (R ) are not correct.
15. अमभकथन (A): उपयोग, समय बीतने औि दघ
ु ट
य ना आटद के कािर् मूल्यह्रास एक मूतय
संपवत्त के मल्
ू य में धगिावट है। 1
कािर् (R): मूल्यह्रास सभी अचल संपवत्तयों पि लगाया िा सकता है चाहे वे मूतय या अमूतय
हों।
सही ववकल्प चन
ु ें
(अ) अमभकथन (A) औि कािर् (R) सही हैं लेककन कािर् (R) अमभकथन (अ) का सही
स्पटटीकिर् नहीं है।
(ब) कािर् (R) औि अमभकथन (A) दोनों सही हैं औि कािर् (R) अमभकथन (A) की सही
व्याख्या है।
Page 6
(द) अमभकथन (A) सही नहीं है लेककन कािर् (R) सही है ।
Assertion(A ): Depreciation is fall in the value of a Tangible Asset because of
Usage, Passage of time and Accident etc.
Reason (R ): Depreciation can be charged on all fixed assets whether they are
Tangible or Intangible. Choose the correct option
(a) Assertion (A) and Reason (R ) are correct but Reason (R ) is not the correct
explanation of Assertion(A ).
(b) Both Reason (R ) and Assertion (A ) are correct and Reason (R ) is the
correct explanation of Assertion (A ).
(c) Only Assertion (A ) is correct.
(d) Assertion (A ) is not correct but the Reason (R ) is correct.
16. Explain any two objectives of accounting. 2
लेखांकन के कोई दो उद्दे श्य बताइए है |
17. Define with example 2
(i) Fictitious Assets (ii) Expenses
OR
(i) Drawing (ii) Gain
ननम्नमलखखत शब्दों को उदाहिर् सटहत समझाइए |
(i) नाममात्र सम्पनतयााँ (ii) व्यय
अथवा
(i) आहिर् (ii) लाभ
18. What is accounting period Concept ? 2
लेखा अवधि की अविािर्ा क्या है ?
Page 7
What is dual aspect concept ?
द्ववपहलू अविािर्ा क्या है ?
19. Give two point of distinction between purchase books and purchase account. 2
क्रय पस्
ु तक औि क्रय खाते में दो अंति मलखखए |
20. Give any two reasons for Popularity of Double entry system. 2
दोहिी लेखा प्रर्ाली की लोकवप्रयता के मलए कोई दो कािर् बताए।
21. Explain any two advantages of accrual basis of accounting. 2
लेखांकन के उपाियन आिाि के कोई दो लाभ मलखखए।
22. From the following particulars prepare bank reconciliation statement. 3
(a) balance as per pass book on 31st march overdrawn ₹15,000.
(b) cheque drawn on 31st march 2025 ₹2,000, ₹6,000, ₹2,400 and ₹3,600 But out of these
the last two cheques were not presented for payment up to 5th April 2025.
(c) interest on bank overdraft not entered in a cashbook ₹845.
(d) Out station cheque for ₹20,000 lodged in the bank on 25 th march, 2025nBut out of
these cheques worth ₹18,000 were credited in April, 2025.
(e) ₹200 being chamber of Commerce subscriptions paid by the bank under a standing
order on 31st March. 2025 was not entered in the cashbook.
ननम्नमलखखत ववविर्ों से बैंक समािान ववविर् तैयाि किें ।
(क) 31 माचय को पास बुक के अनुसाि शेष िामश ₹15,000 ओविड्राफ्ट।
(ख) 31 माचय 2025 को ननकाले गए चेक ₹2,000, ₹6,000, ₹2,400 औि ₹3,600 लेककन
इनमें से अंनतम दो चेक 5 अप्रैल 2025 तक भुगतान के मलए प्रस्तुत नहीं ककए गए।
(ग) बैंक ओविड्राफ्ट पि ब्याि कैशबुक में दिय नहीं ककया गया ₹845।
(घ) 25 माचय, 2025 को बैंक में िमा ककए गए ₹20,000 के आउट स्टे शन चेक। लेककन इनमें
से ₹18,000 के चेक अप्रैल, 2025 में िमा ककए गए। (ङ) 31 माचय, 2025 को बैंक द्वािा
Page 8
कैशबुक में दिय नहीं ककया गया।
23. Prepare Accounting equation on the basis of the following transactions: 3
₹
1. Start business with Cash 1,20,000
2. Purchase Goods for cash 10,000
3. Rent received 5,000
4. Salary outstanding 2,000
5. Received interest 700
ननम्नमलखखत लेन-दे न के आिाि पि लेखांकन समीकिर् तैयाि किें :
₹
1. नकदी से व्यवसाय शुरू किें 1,20,000
2. नकदी के मलए सामान खिीदें 10,000
3. ककिाया प्राप्त किें 5,000
4. बकाया वेतन 2,000
5. ब्याि प्राप्त ककया 700
24. Pass Journal Entries from the following: 3
1. Received ₹ 20,000 from Subhash, which were written off as bad debts in the
previous year.
2. Salaries due to cleeks ₹ 50,000.
3. Out of rent paid this year, ₹10,000 related to next year.
OR
1. Provide 10%. Depreciation on furniture Costing ₹ 50,000.
2. Provide 12%. Interest on Capital amounting to ₹ 10,00,000.
3. Charge interest on Drawings ₹ 8000
ननम्नमलखखत की िनयल प्रववजटटयााँ कीजिए:
Page 9
2. क्लकों को दे य वेतन ₹ 50,000
3. इस वषय भुगतान ककए गए ककिाए में से, ₹ 10,000 अगले वषय से संबंधित।
अथवा
1. ₹ 50,000 की लागत वाले फनीचि पि 10% मूल्यह्रास प्रदान किें ।
2. ₹ 10,00,000 की पूंिी पि 12% ब्याि प्रदान किें ।
3. आहिर् पि ब्याि लगाएं ₹ 8000
25. Prepare Trial Balance from the following information. 3
ननम्नमलखखत शेषो से तलपट तैयाि कीजिए ।
Prepaid expenses ₹ 5,000
Outstanding Rent ₹ 2,000
Bad Debts Recovered ₹ 4,000
Interest on Investment ₹ 1,000
Bank overdraft ₹ 2,000
Discount Allowed ₹ 800
26. Pass the rectification entries from the following particulars. 3
1. ₹710, the total of sales return Book has been posted to the credit of the Purchase
return A/c.
2. An item of ₹626 written off as a Bad Debt from Chanderkanta has not been debited
to Bad Debts A/C.
3. Goods sold to X and Y for ₹ 1600 and 1200 respectively, but were recorded in the
Sales Book as to X ₹1200 and Y ₹ 1600.
OR
1. Goods of ₹850 were returned to Bhardwaj It was recorded in the Purchase Book as
₹ 580.
2. A sum of ₹375 owned by Ravi has been Included in the list of Sundry creditors.
Page 10
Repair A/C.
ननम्नमलखखत ववविर्ों में सि
ु ाि प्रववजटटयााँ किें |
1. ववक्रय वापसी पुस्तक की कुल िामश ₹710 क्रय वापसी खाते में िमा की गई है।
2. चंद्रकांत से अशोध्य ऋर् के रूप में मलखे गए ₹626 की िामश को अशोध्य ऋर् खाते
में िेबबट नहीं ककया गया है।
3. एक्स औि वाई को क्रमशः ₹1600 औि 1200 में माल बेचा गया, लेककन ववक्रय पुस्तक
में एक्स के मलए ₹1200 औि वाई के मलए ₹1600 के रूप में दिय ककया गया।
या
1. भािद्वाि को ₹850 का माल वापस ककया गया, इसे क्रय पुस्तक में ₹580 के रूप में
दिय ककया गया।
2. िवव के स्वाममत्व वाली ₹375 की िामश को ववववि लेनदािों की सूची में शाममल ककया
गया है।
3. एक पिु ानी मशीनिी की मिम्मत में खचय की गई ₹ 750 की िामश को मिम्मत खाते में
िेबबट कि टदया गया है।
27. Net Sales during the year ended 31st March 2025, is ₹ 6,00,000 Gross Profit is 25% on
Cost. find out Gross Profit and cost of goods sold. 3
31 माचय 2025 को समाप्त वषय के दौिान शुद्ि बबक्री ₹ 6,00,000 है। सकल लाभ लागत
पि 25% है। सकल लाभ औि बेची गई वस्तुओं की लागत ज्ञात कीजिए।
28. Birla Cotton Mills purchased a machinery on 1st August, 2009 for ₹90,000. On 1st
October, 2010 it purchased another machine for ₹40,000.
On 30th June, 2011 it sold off the first machine purchased in 2009 for ₹58,000 and on the
same date purchased a new machinery for ₹1,00,000. Depreciation is provided at 20%
p.a. on the original cost each year. Accounts are closed each year on 31st March.
Show the Machinery Account for three years. 5
Page 11
2010 को इसने ₹40,000 में एक औि मशीन खिीदी। 30 िून, 2011 को इसने 2009 में खिीदी
गई पहली मशीन को ₹58,000 में बेच टदया औि उसी तािीख को ₹1,00,000 में एक नई
मशीनिी खिीदी। प्रत्येक वषय मूल लागत पि 20% प्रनत वषय की दि से मूल्यह्रास प्रदान
ककया िाता है। खाते प्रत्येक वषय 31 माचय को बंद ककए िाते हैं। तीन वषों के मलए
मशीनिी खाता टदखाएाँ।
OR
Write any five causes of depreciation.
मूल्य ह्रास के कोई पााँच कािर् मलखखए।
29. Prepare two column cash book from the following information: 5
ननम्नमलखखत िानकािी से दो कॉलम वाली िोकड़ बही तैयाि किें :
date Particulars Amount (₹)
June 1 Cash in hand 2,800
June 1 Cash at Bank 7,000
June 10 Discounted a bill of exchange at 1% through bank 5,000
June 15 Cash sales 6,000
June 18 Paid into bank 3,000
June 20 Paid rent 700
June 25 Bank charges 100
June 30 Withdrawn from bank for personal use 1,500
June 30 Purchase goods on credit from Vinay 4,000
OR
Write the advantages of special purpose subsidiary book.
ववशेष उद्दे श्य वाली सहायक पुस्तक के लाभ मलखखए।
30. Prepare the Trading Account, Profit & Loss Account, and Balance Sheet by looking at
the Trial Balance and adjustments given below: 5
नीचे दिया गया ट्रायल बैलेंस और समायोजन िे खकर ट्रे ड ग
िं खाता, लाभ-हानन खाता, और बैलेंस
शीट तैयार कीजजए:
Trial balance
As on 31st march 2024
Page 12
िे निार debtors 15,000
नकि cash 5,000
फनीचर furniture 20,000
ककराया rent 6,000
वेतन salary 8,000
खरीि purchase 25,000
प्रारिं भभक स्टॉक opening stock 10,000
बबक्री sales 40,000
पिंजी capital 49,000
कुल total 89,000 89,000
Adjustments समायोिन :
1. Closing stock is ₹15,000.
2. Unknown expenses of ₹1,000 are payable.
3. Furniture is to be depreciated at 10% per annum.
4. Bad debts of ₹1,000 are to be written off.
1. अंनतम स्टॉक ₹15,000 है।
2. अज्ञात खचच ₹1,000 िे य है।
3. फनीचर पर 10% वार्षचक मल्यह्रास िे ना है।
4. ₹1,000 की बत ऋण (Bad Debts) को भलखना है।
OR
Write five differences between trial balance and balance sheet.
तलपट औि तुलनपत्र के बीच पााँच अंति मलखें।
Document Details
| Board / Org | Haryana Board |
| Exam | Class 11 |
| Type | Sample Paper |
| Pages | 12 |
| Updated | 24 Sep 2026 |