Karnataka 2nd PUC Question Paper 2026 Answer Key Accountancy
Finished viewing? Save it for later —
Download Karnataka 2nd PUC Question Paper 2026 Answer Key Accountancy (PDF · 8 pages)About Karnataka 2nd PUC Question Paper 2026 Answer Key Accountancy
Karnataka 2nd PUC Question Paper 2026 Answer Key Accountancy is available here for free download. Published by Karnataka Board for Class 12, this question paper can be viewed online or downloaded as a PDF (8 pages). Candidates preparing for Class 12 can use Karnataka 2nd PUC Question Paper 2026 Answer Key Accountancy to understand the exam pattern, the type of questions asked, and the overall difficulty level.
Frequently Asked Questions
How can I download Karnataka 2nd PUC Question Paper 2026 Answer Key Accountancy?
Open this page and click the Download button to save Karnataka 2nd PUC Question Paper 2026 Answer Key Accountancy as a PDF. It is completely free on AglaSem Docs.
Is Karnataka 2nd PUC Question Paper 2026 Answer Key Accountancy free to download?
Yes. Karnataka 2nd PUC Question Paper 2026 Answer Key Accountancy can be viewed online and downloaded as a PDF free of cost on AglaSem Docs.
How many pages does Karnataka 2nd PUC Question Paper 2026 Answer Key Accountancy have?
Karnataka 2nd PUC Question Paper 2026 Answer Key Accountancy contains 8 pages, which you can read online or download together as a single PDF.
Where can I find more Class 12 study material?
You can find more Class 12 question papers, sample papers, syllabus, and answer keys on AglaSem Docs.
Karnataka 2nd PUC Question Paper 2026 Answer Key Accountancy – Text
Read the full text of this question paper below — useful to quickly search, copy and reference the content online without downloading the PDF.
📄 View text version (8 pages)
Page 1
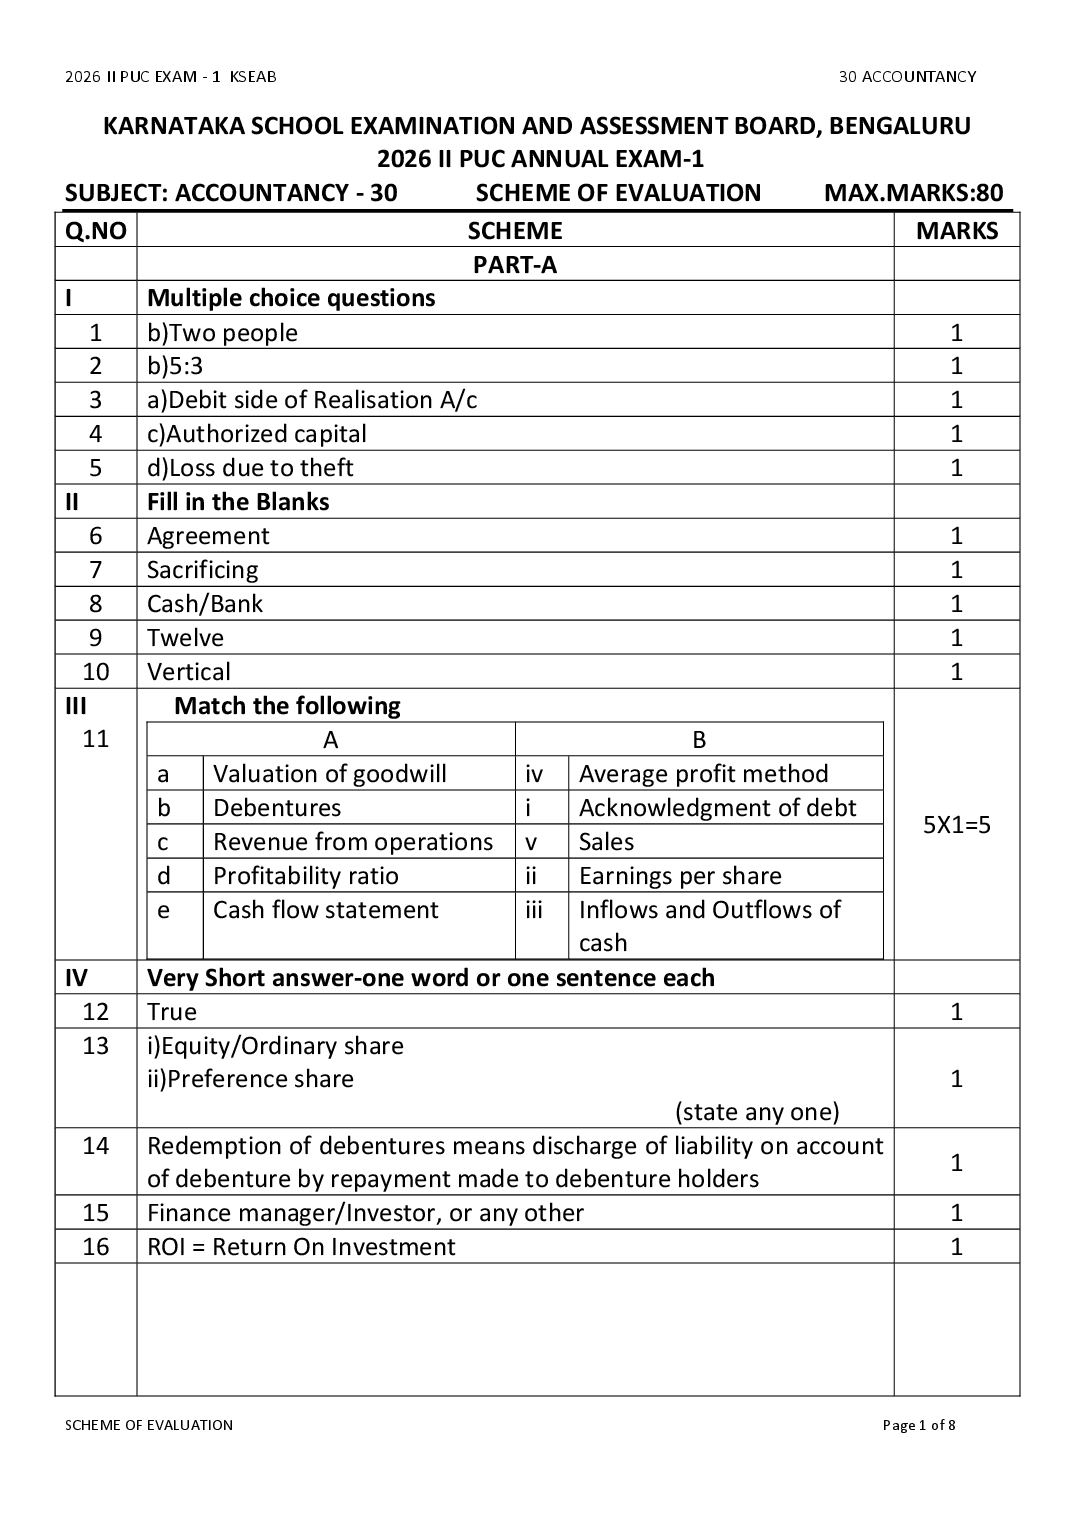
KARNATAKA SCHOOL EXAMINATION AND ASSESSMENT BOARD, BENGALURU
2026 II PUC ANNUAL EXAM-1
SUBJECT: ACCOUNTANCY - 30 SCHEME OF EVALUATION MAX.MARKS:80
Q.NO SCHEME MARKS
PART-A
I Multiple choice questions
1 b)Two people 1
2 b)5:3 1
3 a)Debit side of Realisation A/c 1
4 c)Authorized capital 1
5 d)Loss due to theft 1
II Fill in the Blanks
6 Agreement 1
7 Sacrificing 1
8 Cash/Bank 1
9 Twelve 1
10 Vertical 1
III Match the following
11 A B
a Valuation of goodwill iv Average profit method
b Debentures i Acknowledgment of debt
5X1=5
c Revenue from operations v Sales
d Profitability ratio ii Earnings per share
e Cash flow statement iii Inflows and Outflows of
cash
IV Very Short answer-one word or one sentence each
12 True 1
13 i)Equity/Ordinary share
ii)Preference share 1
(state any one)
14 Redemption of debentures means discharge of liability on account
1
of debenture by repayment made to debenture holders
15 Finance manager/Investor, or any other 1
16 ROI = Return On Investment 1
SCHEME OF EVALUATION Page 1 of 8
Page 2
PART-B
17 Differences between fixed capital method and fluctuating capital
method
Sl.No Fixed capital method Fluctuating capital method
i Capital A/c balance Capital A/c balance fluctuates 1+1
remains fixed from year to year
ii Adjustments are made Adjustments are made in Capital
in Current account account
(Or any other two differences)
18 i)Immediate full payment
ii)Transfer to retired partner’s loan A/c 1+1
iii)Partly paid in cash and balance transferred to retired partner’s
loan A/c
iv)Paid in installments along with interest
(any two)
19 When the company receives applications for more number of
shares than the number of shares offered to the public for 2
subscription, it is called over subscription.
20 i)Statement of profit and loss/ Income statement
ii)Balance sheet/ Position statement 1+1
21 i)Cash proceeds from issue of equity shares
ii)Cash proceeds from issue of debentures 1+1
(or any other two)
PART - C
22. Dr. Profit and Loss Appropriation A/c for the year ending 31-3-2025 Cr.
Particulars ₹ ₹ Particulars ₹ ₹
To Interest on Capital By P & L A/c(Net profit) 50,000
Ravi 15,000
Kiran 10,000 25,000 By Interest on drawings
To Commission to Ravi 3,000 Ravi 4,000
To Salary to Kiran 8,000 Kiran 2,000 6,000
To Partners Capital A/c
(Profit transferred)
A 12,000
B 8,000 20,000
Total 56,000 Total 56,000
[MARKS ALLOTMENT: each item 1 mark:6X1=6]
SCHEME OF EVALUATION Page 2 of 8
Page 3
23. Gained share = New share – Old share
𝟑 𝟓
Geetha’s gain = 𝟓 − 𝟏𝟎
𝟔 𝟓
= 𝟏𝟎 − 𝟏𝟎
𝟏
= 𝟏𝟎
𝟐 𝟐
Sangeetha’s gain = 𝟓 − 𝟏𝟎
𝟒 𝟐
= 𝟏𝟎 − 𝟏𝟎
𝟐
= 𝟏𝟎
𝟏 𝟐
Therefore, GR = 𝟏𝟎 : 𝟏𝟎 or 1:2 [MARKS ALLOTMENT:1+2+2+1=6]
24. Dr. Vishal’s executors A/c Cr.
Particulars ₹ Particulars ₹
To, Balance c/d 1,27,300 By Vishal’s capital 80,000
By Interest on capital
9 7,200
80,000X12%X12
By Salary
18,000
2,000 X 9
By Anil’s capital
4 8,000
14,000 X
7
By Sunil’s capital
3 6,000
14,000 X 7
By P & L Suspense
9 3 8,100
36,000 X 12 X 10
Total 1,27,300 Total 1,27,300
[MARKS ALLOTMENT: each item 1 mark: 6X1=6]
25. Statement of Profit and Loss for the year ended 31st March, 2025
Particulars Note No. ₹
I. Revenue from operations 8,00,000
II. Other income ---
III. Total Revenue(I+II) 8,00,000
IV. Expenses:
Purchase of stock in trade 4,00,000
Employee benefits expense 1,00,000
Finance cost 30,000
Depreciation and amortisation 20,000
Other expenses 1 50,000
Total Expenses 6,00,000
V. Profit before tax (III-IV) 2,00,000
VI.Less: Income Tax [60,000]
Profit for the year (V-VI) 1,40,000
Notes to accounts:
Particulars ₹
1. Other expenses:
Rent 15,000
Administrative expenses 35,000
Total 50,000
[MARKS ALLOTMENT: (1+3+1)+1=5+1=6]
SCHEME OF EVALUATION Page 3 of 28
Page 4
26. Cash flow from Operating Activities - (Under Indirect Method)
Particulars ₹
Net profit 7,00,000
Adjustments for non-cash and non-operating items:
Add: Depreciation 1,50,000
Less: Profit on sale of asset (60,000)
Operating profit before working capital changes 7,90,000
Add: Decrease in trade receivable 55,000
Less: Decrease in trade payable (45,000)
Net Cash flow from operating activities 8,00,000
[MARKS ALLOTMENT: each item 1 mark:6x1=6]
PART-D
27. Dr. i) Revaluation A/c Cr.
Particulars ₹ Particulars ₹
To Furniture(20,000x5%) 1,000 By Buildings 8,000
To Machinery (30,000-27,000) 3,000 (80,000X10%)
To Partners Capital A/c(Profit)
Govind - 3,000
Sudeep - 1,000 4,000
Total 8,000 Total 8,000
Dr. ii) Partners Capital A/c Cr.
Particulars Govind Sudeep Tarun Particulars Govind Sudeep Tarun
To Govind’s Cap - - 7,500 By Balance b/d 90,000 40,000 -
To Sudeep’s Cap - - 2,500 By General Reserve 15,000 5,000 -
To Cash 7,500 2,500 - By Cash - - 40,000
To Balance c/d 1,08,000 46,000 30,000 (30,000+10,000)
By Tarun’s Capital 7,500 2,500 -
By Revaluation 3,000 1,000 -
Total 1,15,500 48,500 40,000 Total 1,15,500 48,500 40,000
By Balance b/d 1,08,000 46,000 30,000
iii) New Balance Sheet as on 01-04-2025
Liabilities ₹ Assets ₹
Creditors 45,000 Cash (16000 + 40000 -10000) 46,000
Bills payable 25,000 Debtors 40,000
Stock 34,000
Capital accounts: Furniture 20,000
Govind 1,08,000 Less:Depreciation 1,000 19,000
Sudeep 46,000 Machinery 30,000
Tarun 30,000 Less:Depreciation 3,000 27,000
Buildings 80,000
Add: Appreciation 8,000 88,000
Total 2,54,000 Total 2,54,000
[MARKS ALLOTMENT: 2+5+5=12]
SCHEME OF EVALUATION Page 4 of 18
Page 5
28.
Dr. i) Realisation A/c Cr.
Particulars ₹ Particulars ₹
To Debtors 35,000 By Creditors 40,000
To Bills Receivable 15,000 By Bills payable 20,000
To Computers 30,000 By Vanitha’s loan 25,000
To Machinery 50,000
To Land 70,000 By Bank A/c (Assets realized)
Debtors 30,000
To Bank A/c (Liabilities paid) Bills Receivable 12,000
Creditors 40,000 Computers 25,000
Bills payable 20,000 Machinery 45,000
Vanitha’s loan 25,000 Land 85,000
85,000 U/R Investment 3,000 2,00,000
To Bank A/c
(Dissolution cost) 6,000 By Partners Capital A/c (loss)
Anitha 3,000
Sunitha 3,000 6,000
Total 2,91,000 Total 2,91,000
Dr. ii) Partners Capital A/c Cr.
Particulars Anitha Sunitha Particulars Anitha Sunitha
To Realisation(loss) 3,000 3,000 By Balance b/d 60,000 70,000
By Profit and Loss A/c 15,000 15,000
To Bank 72,000 82,000
(Final settlement)
Total 75,000 85,000 Total 75,000 85,000
Dr. iii) Bank A/c Cr.
Particulars ₹ Particulars ₹
To Balance b/d 45,000 By Realisation (Liabilities paid) 85,000
To Realisation A/c 2,00,000 By Realisation (Dissolution cost) 6,000
(Assets realized) By Anitha’s Capital 72,000
By Sunitha’s Capital 82,000
Total 2,45,000 Total 2,45,000
[MARKS ALLOTMENT: 6+3+3=12]
SCHEME OF EVALUATION Page 5 of 18
Page 6
29. Journal Entries in the books of Supreme Company Ltd.,
Date Particulars L.F Debit (₹ ) Credit (₹ )
1 Bank A/c (10,000x20) Dr. 2,00,000 ----
To, Equity Share application A/c ----- 2,00,000
(Being equity share application money received)
2 Equity Share application A/c Dr. 2,00,000 ----
To, Equity Share Capital A/c ----- 2,00,000
(Being equity share application money
transferred to equity share capital)
3 Equity Share allotment A/c(10,000x50) Dr. 5,00,000 ----
To, Equity Share Capital A/c (10,000x40) ---- 4,00,000
To, Securities Premium Reserve A/c(10000x10) ---- 1,00,000
(Being equity share allotment money due)
4 Bank A/c Dr. 5,00,000 ----
To, Equity Share Allotment A/c ----- 5,00,000
(Being equity share allotment money received)
5 Equity Share First and Final call A/c(10,000x40) Dr. 4,00,000 ----
To, Equity Share Capital A/c ----- 4,00,000
(Being equity share First and Final call money
due)
6 Bank A/c (9,500x40) Dr. 3,80,000 ----
To, Equity Share First / Final call A/c ----- 3,80,000
(Being equity share first/final call money
received except on 500 shares)
7 Equity Share capital A/c (500x100) Dr. 50,000 ----
To, Forfeited shares A/c (500x60) --- 30,000
To, Equity Share First / Final call A/c(500x40) --- 20,000
(Being 500 equity shares are forfeited due to
non-payment of first & final call money)
8 Bank A/c (500x80) Dr. 40,000 ----
Forfeited shares A/c (500x20) Dr. 10,000 ----
To, Equity Share Capital A/c (500x100) ----- 50,000
(Being forfeited shares are reissued at discount)
9 Forfeited shares A/c [30,000-10,000] Dr. 20,000 ----
To, Capital reserve A/c ----- 20,000
(Being profit on forfeited shares transferred to
capital reserve)
[MARKS ALLOTMENT: Simple Entry:6X1=6 Compound Entry:3X2=6 TOTAL:6+6=12]
30. Journal Entries in the books of Atridatta Co. Ltd.,
Date Particulars L.F Debit(₹ ) Credit(₹ )
01-04-2024 Bank A/c 10000x90 Dr. 9,00,000 -----
To, 10%Debenture Application & Allotment A/c ------ 9,00,000
(Being Receipt of application money)
01-04-2024 10%Debenture Application & Allotment A/c Dr. 9,00,000 ------
Loss on issue of Debentures A/c (100000+100000) Dr. 2,00,000 ------
To, 10% Debentures A/c ------- 10,00,000
To, Premium on redemption of debentures ------ 1,00,000
(Being Allotment of debentures at discount and
redeemable at premium)
30-09-2024 Debenture interest A/c Dr. 50,000 -------
To, Income tax payable A/c ------ 5,000
To, Debenture holders A/c ----- 45,000
(Being interest due on debentures and TDS at 10%)
SCHEME OF EVALUATION Page 6 of 18
Page 7
30-09-2024 Income tax payable A/c Dr. 5,000 -------
To, Bank ------ 5,000
(Being Payment of TDS amount)
30-09-2024 Debenture holders A/c Dr. 45,000 --------
To, Bank A/c -------- 45,000
(Being Interest paid to debenture holders)
31-03-2025 Debenture interest A/c Dr. 50,000 --------
To, Income tax payable A/c -------- 5,000
To, Debenture holders A/c -------- 45,000
( Being interest due on debentures and TDS at 10%)
31-03-2025 Income tax payable A/c Dr. 5,000 --------
To, Bank ------- 5,000
(Being Payment of TDS amount)
31-03-2025 Debenture holders A/c Dr. 45,000 ---------
To, Bank A/c -------- 45,000
(Being Interest paid to debenture holders)
31-03-2025 Statement of Profit and Loss Dr. 1,00,000 -----------
To Debenture Interest A/c ---------- 1,00,000
(Being Debenture interest transferred to SPL)
[MARKS ALLOTMENT: SIMPLE ENTRIES:6X1=6 COMPOUND ENTRIES:3X2=6 TOTAL:6+6=12]
31. Comparative Balance Sheet of Sunstar Co. Ltd as at 31-03-2024 & 31-03-2025
31-3-2024 31-3-2025 Absolute Percentage
increase or of increase
Particulars
decrease or decrease
(₹) (₹) (₹) (%)
(1) (2) (3) (4) (5)
I.EQUITY AND LIABILITIES
1. Shareholders fund:
a) Share Capital 5,00,000 7,50,000 2,50,000 50.00
b) Reserves & surplus 1,00,000 1,20,000 20,000 20.00
2. Non-current liabilities:
a) Long term borrowings 3,00,000 4,00,000 1,00,000 33.33
3. Current Liabilities:
a) Trade payable 1,50,000 1,80,000 30,000 20.00
Total 10,50,000 14,50,000 4,00,000 38.10
II. ASSETS
1. Non-current assets:
a) Fixed assets
i)Tangible assets 4,00,000 7,00,000 3,00,000 75.00
ii) Intangible assets 2,00,000 2,50,000 50,000 25.00
b) Long term investments 1,50,000 1,20,000 (30,000) (20.00)
2. Current assets:
a) Inventories 80,000 1,00,000 20,000 25.00
b) Trade receivables 1,20,000 2,00,000 80,000 66.67
c) Cash and cash equivalents 1,00,000 80,000 (20,000) (20.00)
Total 10,50,000 14,50,000 4,00,000 38.10
[MARKS ALLOTMENT: ROW-WISE: 12X1=12]
SCHEME OF EVALUATION Page 7 of 18
Page 8
𝐶𝑢𝑟𝑟𝑒𝑛𝑡 𝑎𝑠𝑠𝑒𝑡𝑠
32. a) Current ratio = 𝐶𝑢𝑟𝑟𝑒𝑛𝑡 𝑙𝑖𝑎𝑏𝑖𝑙𝑖𝑡𝑖𝑒𝑠
1,50,000
= 1,25,000
=1.2 :1
Current Assets = Inventory + Trade Receivable
= 75,000 + 75,000
= 1,50,000
Current Liabilities = Trade Payables = 1,25,000
𝐿𝑜𝑛𝑔 𝑡𝑒𝑟𝑚 𝑑𝑒𝑏𝑡
b) Debt to Capital Employed ratio =
𝐶𝑎𝑝𝑖𝑡𝑎𝑙 𝑒𝑚𝑝𝑙𝑜𝑦𝑒𝑑
1,00,000
= 3,50,000
= 0.29 : 1
Long term debt = Debentures = 1,00,000
Capital employed = Shareholders fund +Long term debt
= 2,50,000 + 1,00,000
= 3,50,000
Shareholders fund = Share capital + Net profit
= 2,00,000 + 50,000
= 2,50,000
𝑁𝑒𝑡 𝑐𝑟𝑒𝑑𝑖𝑡 𝑅𝑒𝑣𝑒𝑛𝑢𝑒 𝐹𝑟𝑜𝑚 𝑂𝑝𝑒𝑟𝑎𝑡𝑖𝑜𝑛𝑠
c) Trade Receivable turnover ratio = 𝐴𝑣𝑒𝑟𝑎𝑔𝑒 𝑇𝑟𝑎𝑑𝑒 𝑅𝑒𝑐𝑒𝑖𝑣𝑎𝑏𝑙𝑒
3,00,000
=
75,000
= 4 times
𝑁𝑒𝑡 𝑐𝑟𝑒𝑑𝑖𝑡 𝑝𝑢𝑟𝑐ℎ𝑎𝑠𝑒𝑠
d) Trade Payable turnover ratio =
𝐴𝑣𝑒𝑟𝑎𝑔𝑒 𝑇𝑟𝑎𝑑𝑒 𝑃𝑎𝑦𝑎𝑏𝑙𝑒𝑠
2,50,000
= 1,25,000
= 2 times
𝑂𝑝𝑒𝑟𝑎𝑡𝑖𝑛𝑔 𝑐𝑜𝑠𝑡
e) Operating ratio = 𝑅𝑒𝑣𝑒𝑛𝑢𝑒 𝑓𝑟𝑜𝑚 𝑜𝑝𝑒𝑟𝑎𝑡𝑖𝑜𝑛𝑠 x100
4,50,000
= 5,00,000 x100
= 90%
Operating cost = Cost of RFO + Operating expenses
= 4,00,000 + 50,000
= 4,50,000
Cost of RFO = Revenue from operations - Gross profit
= 5,00,000 - 1,00,000
= 4,00,000
𝑁𝑒𝑡 𝑝𝑟𝑜𝑓𝑖𝑡
f) Net profit ratio = 𝑅𝑒𝑣𝑒𝑛𝑢𝑒 𝑓𝑟𝑜𝑚 𝑜𝑝𝑒𝑟𝑎𝑡𝑖𝑜𝑛𝑠 X100
50,000
= 5,00,000 𝑋 100
= 10%
[MARKS ALLOTMENT: 6 RATIOS X2 EACH=12(Formula 1 mark and calculation 1 mark)]
SCHEME OF EVALUATION Page 8 of 18
Document Details
| Board / Org | Karnataka Board |
| Exam | Class 12 |
| Type | Question Paper |
| Pages | 8 |
| Language | english |
| Updated | 24 Sep 2026 |