MBOSE Class 12 Sample Question Paper 2027 Accountancy
Finished viewing? Save it for later —
Download MBOSE Class 12 Sample Question Paper 2027 Accountancy (PDF · 14 pages)About MBOSE Class 12 Sample Question Paper 2027 Accountancy
MBOSE Class 12 Sample Question Paper 2027 Accountancy is available here for free download. Published by Meghalaya Board for Class 12, this sample paper can be viewed online or downloaded as a PDF (14 pages). Candidates preparing for Class 12 can use MBOSE Class 12 Sample Question Paper 2027 Accountancy to understand the exam pattern, the type of questions asked, and the overall difficulty level.
Frequently Asked Questions
How can I download MBOSE Class 12 Sample Question Paper 2027 Accountancy?
Open this page and click the Download button to save MBOSE Class 12 Sample Question Paper 2027 Accountancy as a PDF. It is completely free on AglaSem Docs.
Is MBOSE Class 12 Sample Question Paper 2027 Accountancy free to download?
Yes. MBOSE Class 12 Sample Question Paper 2027 Accountancy can be viewed online and downloaded as a PDF free of cost on AglaSem Docs.
How many pages does MBOSE Class 12 Sample Question Paper 2027 Accountancy have?
MBOSE Class 12 Sample Question Paper 2027 Accountancy contains 14 pages, which you can read online or download together as a single PDF.
Where can I find more Class 12 study material?
You can find more Class 12 question papers, sample papers, syllabus, and answer keys on AglaSem Docs.
MBOSE Class 12 Sample Question Paper 2027 Accountancy – Text
Read the full text of this sample paper below — useful to quickly search, copy and reference the content online without downloading the PDF.
📄 View text version (15 pages)
Page 1
MBOSE Class 12
Sample Question Paper
2027 Accountancy
EXAM YEAR TYPE SUBJECT
Meghalaya Class 12 2027 Sample Paper Accountancy
Notes · Sample Papers · Previous Year Papers · Mock Tests
Page 2
.co s e m
s em l a
a ag
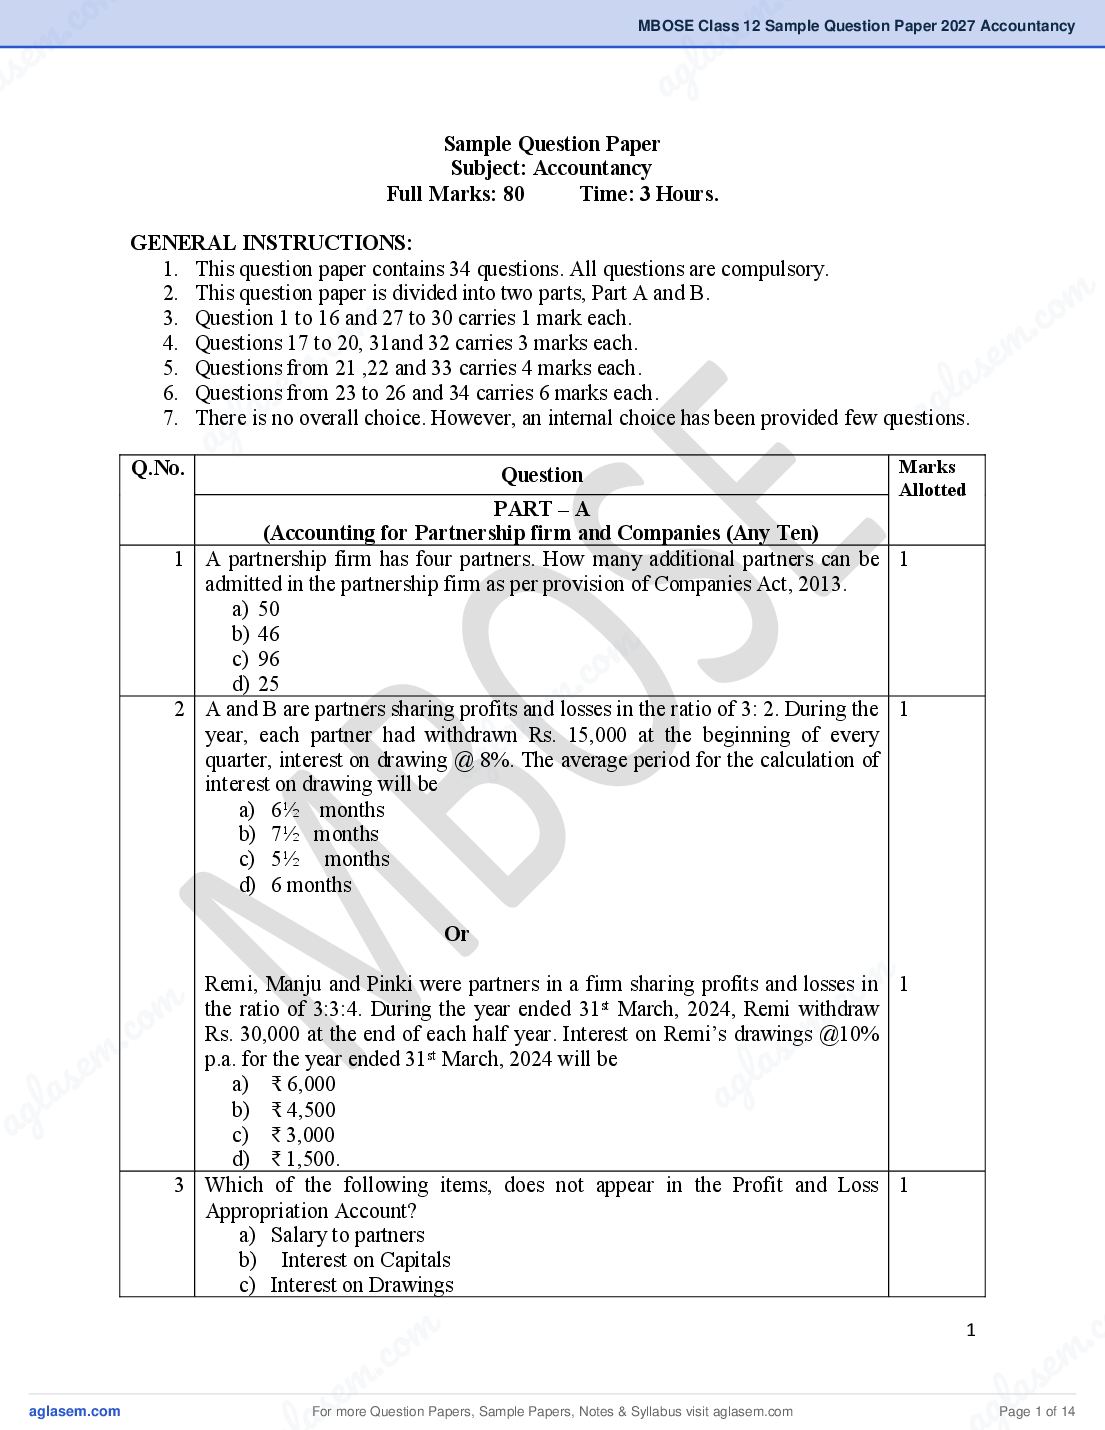
Sample Question Paper
Subject: Accountancy
Full Marks: 80 Time: 3 Hours.
GENERAL INSTRUCTIONS:
1. This question paper contains 34 questions. All questions are compulsory.
m
co
2. This question paper is divided into two parts, Part A and B.
om .
3. Question 1 to 16 and 27 to 30 carries 1 mark each.
. c
4. Questions 17 to 20, 31and 32 carries 3 marks each.
e m
e m
5. Questions from 21 ,22 and 33 carries 4 marks each.
l as
as
6. Questions from 23 to 26 and 34 carries 6 marks each.
l ag
g
7. There is no overall choice. However, an internal choice has been provided few questions.
a
Q.No. Question Marks
Allotted
PART – A
(Accounting for Partnership firm and Companies (Any Ten)
1 A partnership firm has four partners. How many additional partners can be 1
admitted in the partnership firm as per provision of Companies Act, 2013.
a) 50
m
b) 46
.co
c) 96
m
d) 25
s e
2 A and B are partners sharing profits and losses in the ratio of 3: 2. During the 1
l a
year, each partner had withdrawn Rs. 15,000 at the beginning of every
ag
quarter, interest on drawing @ 8%. The average period for the calculation of
interest on drawing will be
a) 6½ months
b) 7½ months
c) 5½ months
d) 6 months
Or
m
.co
Remi, Manju and Pinki were partners in a firm sharing profits and losses in 1
m
.co
the ratio of 3:3:4. During the year ended 31st March, 2024, Remi withdraw
Rs. 30,000 at the end of each half year. Interest on Remi’s drawings @10%
e m
e m p.a. for the year ended 31st March, 2024 will be
las
las a) ₹ 6,000
ag
ag b) ₹ 4,500
c) ₹ 3,000
d) ₹ 1,500.
3 Which of the following items, does not appear in the Profit and Loss 1
Appropriation Account?
a) Salary to partners
b) Interest on Capitals
c) Interest on Drawings
om
1
. c
. c e m
m as
se
For more Question Papers, Sample Papers, Notes & Syllabus visit
gl
Page 1 of 14
Page 3
4 Assertion (A): Partnership is the relation between persons who have 1
agreed to share the profits of the business carried on by all or
any of them acting for all
Reason (R): If a partner carries on any business of the same nature and
competing with that of the firm, he/she shall account for and
pay to the firm all profit made by him/her in that business.
In the context of above two statements, which of the following is
correct?
a) Both (A) and (R) are correct.
b) Both (A) and (R) are incorrect
c) Both (A) and (R) are correct and (R) is the correct explanation of
(A)
d) Both (A) and (R) are correct but (R) is not the correct explanation of
(A).
5 X and Y are partners in a firm sharing profits and losses in proportion of 2:1. 1
They admit a new partner Z for 1/6 th share in profit. What is the Sacrificing
Ratio of X and Y?
a) 3:1
b) 2:1
c) 2:3
d) 3:2
6 300 shares of ₹100 each issued at premium of 10% per share were forfeited 1
for the non-payment of ₹ 20 per share on final call. At the time of forfeiture,
Share Capital Account Will be debited with
a) ₹ 30,000
b) ₹ 60,000
c) ₹ 40,000
d) ₹ 45,000
OR
500 shares of ₹ 10 each were forfeited for the non-payment of first call of ₹2 1
per share (the final call of ₹3 per share was not made). Later, 300 shares were
re-issued @ of ₹ 6 per share ₹ 7 paid up. The Capital Reserve will be
a) ₹ 1,500
b) ₹ 300
c) ₹ 1,200
d) ₹ 2,500
7 Securities Premium Reserve can be used for 1
a) Paying interest on debentures
b) To issue fully paid bonus shares to the shareholders
c) Paying tax liability
d) Paying dividend on shares.
8 A, B and C are partners sharing profits and losses in the ratio of 3:2:1. A and 1
B have guaranteed that C’s share of profit will not be less than ₹ 15,000, any
2
For more Question Papers, Sample Papers, Notes & Syllabus visit Page 2 of 14
Page 4
.co s e m
s em l a
a ag
deficiency to be borne by A and B in the ratio of 2:3. If the profit for the year
is ₹ 60,000, then the deficiency to be shared by A and B will be
a) ₹ 3,000 and ₹ 2,000
b) ₹ 2,000 and ₹ 3,000
c) ₹ 4,000 and ₹ 6,000
d) ₹ 6,000 and ₹ 4,000
m
co
9 The loss on issue of debentures is written off from: 1
om .
a) Securities Premium Reserve
. c
b) Security Reserve
em
e m
c) Debentures Redemption Reserve
l as
l as
d) Reserve Capital
1 a
g
10
agThe part of authorized capital which is not offered to the public is called:
a) Unsubscribed Capital
b) Subscribed Capital
c) Issued Capital
d) Unissued Capital.
11 On dissolution of a firm, Reserve Fund is transferred to 1
a) Realisation A/C
b) Partners’ Capital A/Cs in their Profit-sharing ratio
c) Partners’ capital A/Cs in their Capital ratio
m
.co
d) iv) Cash Account
12 M, N and O were partners in a firm sharing profit and losses in the ratio 1
e m
3:2:1. O retired and his share was taken over by M and N in the ratio of 1:4.
as
The new profit-sharing ratio of M and N is
l
ag
a) 3:2
b) 8:7
c) 7:3
d) 2:3
OR
A, B and C are partners sharing profits in the ratio of 5:3:2. A retires and the 1
new ratio is 2:3. Then gaining ratio will be
a) 3:2
m
.co
b) 5:3
m c) 1:4
m .co d) None of these
s e m
e la
13 Assertion (A): Calls in arrears represent the amount that shareholders have 1
las failed to pay on the shares they hold:
ag
ag Reason (R): Calls in arrears are treated as a liability of the company.
In the context of above two statements, which of the following is correct?
a) Both (A) and (R) are true, and (R) is the correct explanation of (A)
b) Both (A) and (R) are true, but (R) is not the correct explanation of (A)
c) (A) is true, but (R) is false
d) (A) is false, but (R) is true.
om
3
. c
. c e m
m as
se
For more Question Papers, Sample Papers, Notes & Syllabus visit
gl
Page 3 of 14
Page 5
Phiba Ltd. issued 10,000 equity sharesof ₹ 10 each, payable as follows: 1
₹ 3 on Application
₹ 4 on Allotment
₹ 3 on First and Final Call
All the money due was received except, Iba, a share holder holding 2,000
shares, did not pay the first and Final Call. Calls in arrears Account will be
debited with
a) ₹ 6,000
b) ₹ 8,000
c) ₹ 6,500
d) ₹ 10,000
14 P, Q and R are partners sharing profits and losses in the ratio of 3:2:1. Q 1
died. At that time, goodwill of the firm was valued at ₹ 15,000. What
contribution has to be made by P and R in order to pay Q’s Executor?
a) ₹ 20,000 and ₹ 10,000
b) ₹ 15,000 and ₹ 15,000
c) ₹ 1250 and ₹ 3750
d) ₹ 3750 and ₹ 1250
OR
A, B and C were partners sharing profits and losses in the ratio of 5:3:2. B 1
died on 30th June, 2024. The sale and the profit for the year ended 31 st
March, 2024 was ₹ 15,00,00 and ₹ 5,00,000 respectively. The sale from
the beginning of the accounting year till the date of death was ₹ 5,00,000.
The amount of profit to be credited to B’s Capital Account will be
a) ₹ 33,333
b) ₹ 60,000
c) ₹ 55,000
d) ₹ 50,000
15 Debentures which do not carry any specific ratio of interest are known as 1
a) Registered Debentures
b) Zero Coupon Rate Debentures
c) Bearer Debentures
d) Secured Debentures
16 Which of the following is not correct for goodwill: 1
a) It is an intangible asset
b) It is a fictitious asset
c) It may have a realizable value
d) It is amortised
17 A company forfeited 500 shares of ₹10 each, ₹8 called up for non-payment 3
4
For more Question Papers, Sample Papers, Notes & Syllabus visit Page 4 of 14
Page 6
.co s e m
s em l a
a ag
of final call of ₹2 per share. Later 300 shares were re-issued at ₹7 per
share, ₹8 paid up. Pass journal entries to record the above transactions.
18 Damy Co. Ltd acquired assets worth ₹ 4,00,000 and took over liabilities 3
worth ₹ 50,000 from Kiran Ltd at an agreed purchase consideration of
₹3,60,000 to be satisfied by issue of 7% Debentures of ₹ 100 each at a
discount of 10%. Pass journal entries to record the above transactions.
m
co
19 A firm earned an average profit of ₹ 3,00,000 during the last few years. 3
. c om
The normal rate of return in this class of the business is 15%. The assets
of the business were ₹ 17,00,000 and its liabilities were ₹ 2,00,000.
em .
e m
Calculate the goodwill of the firm by capitalization of average profit.
l as
l as
20 A and B are partners sharing profit and losses in the ratio of 3:2. The capital 3
ag
ag
as on 1st April, 2024 was ₹5,00,000 and ₹3,00,000. During the year, A had
withdrawn ₹ 25,000 and B had withdrawn ₹ 15,000. On 1st October,
2024. B had advanced a loan of ₹1,00,000. The partnership deed
provides for interest on capital @ 5% p.a and interest on drawing @
10% p.a. A is entitled to receive a salary of ₹ 6,000 per quarter. Profit
made during the year ended 31st March, 2025 was ₹ 1,40,000. Prepare
Profit and Loss Appropriation Account.
m
m .co
s e
l a
ag
m
m .co
m .co s e m
s e g la
g la a
a
om
5
. c
. c e m
m as
se
For more Question Papers, Sample Papers, Notes & Syllabus visit
gl
Page 5 of 14
Page 7
losses in the ratio of 3:1:1. Their Balance sheet as at 31 st March, 2024
was as follows:
Balance sheet of Asha, Rishi and Pankaj as at 31st March, 2024
Liabilities ₹ Assets ₹
Creditors 90,000 Bank 20,000
General Reserve 60,000 Stock 1,10,000
Capitals Investment 70,000
Asha - 60,000 Building 1,35,000
Rishi – 1,00,000 Goodwill 15,000
Pankaj – 40,000 2,00,000
3,50,000 3,50,000
Pankaj died on 30th September, 2024. According to partnership deed, his
legal representative is entitled to the following:
i) Balance in his capital Account.
ii) Share of profit up to the date of death to be calculated on the basis
of last year’s profit.
iii) Share of goodwill calculated on the basis of 2 years purchase of
average profits of last four years.
iv) Interest on capital @ 12% p.a. The profit for the last four years
were: 2020 – 21 ₹ 30,000; 2021 – 22 ₹ 40,000; 2022-23
₹ 60,000; 2023 – 24 ₹ 70,000.
Prepare Pankaj’s Capital Account to be rendered to his legal
representative.
Or
B) Ankit, Rajesh and Vikram are partners in a firm sharing profits and
losses in the ratio of 2:1:1 respectively. Firm closes its accounts on 4
31st March every year. Rajesh died on 30th September, 2024. There
was a balance of ₹ 1,25,000 in Rajesh’s Capital Account in the
beginning of the year.
In the event of death of any of the partner, the partnership deed provide the
following:
i) Interest on capital is to be provided @ 6% p.a.
ii) The executor of deceased partner shall be paid ₹ 24,000 for his share of
goodwill.
iii) His share of reserve fund which is ₹ 12,000 shall be paid to his
executor.
iv) His share of profit till the date of death will be calculated on the basis of
sales. It is also specified that the sales during the year 2023 – 24 were ₹
4,00,000. The sales from 1st April, 2024 to 30th September, 2024 were ₹
1,20,000. The profit of the firm for the year ending 31 st March, 2024 was
₹ 2,00,000. Prepare Rajesh’s Capital Account.
6
For more Question Papers, Sample Papers, Notes & Syllabus visit Page 6 of 14
Page 8
.co s e m
s em l a
a ag
22 A) Blue and Green are partners in a firm sharing profits and losses in the 4
ratio of 5:3. They admit Purple into partnership for ¼ th share of profit
for which she brings ₹ 50,000 as capital and ₹ 16,000 as goodwill.
Half of the goodwill is withdrawn by Blue and Green. At the time of
admission, the Revaluation Profit was ₹ 4,000. There was a goodwill
already in the books at ₹ 8,000. Pass journal entries to record the
m
co
above transactions.
. c om Or
e m .
m
e admitted C into partnership and decided to share profits and 4 gl
B) A and B are partners sharing profits and losses in the ratio of 3:2.
as
asThey
l losses a
g Reserve
in the ratio of 2:1:1. At the time of admission the General
a respectively. C brought ₹ 30,000 as capital but was unable to
and Revaluation loss were ₹ 24,000 and ₹ 2,500
bring his share of goodwill. Goodwill was valued at ₹ 40,000 at
the time of admission.
Show journal entries to record the above transactions.
23 A) Sonu and Alex were partners in a firm sharing profits and losses in 6
the ratio 3:2. On 31st March, 2025. Their Balance Sheet was as
follows:
o
Balance Sheet as on 31st March, 2025
m
. c
Liabilities ₹
em
Assets
s Debtors
₹
Creditors 60,000
l a Cash 1,66,00
ag Stock
Reserve Fund 60,000 1,44,000
Capitals: 1,50,000
Sonu 5,00,000 Investments 2,60,000
Alex 4,00,000 9,00,000 Furniture 3,00,000
10,20,000 10,20,000
On 1st April, 2025, they admitted Nidhi as a new partner for ¼ th share in the
profits on the following terms:
i) Goodwill of the firm was valued at ₹ 4,00,000 and Nidhi brought the
m
.co
necessary amount in cash for her share of goodwill premium, half
m
.co
of which was withdrawn by the old partners.
ii) Stock was to be increased by 20% and furniture was to be reduced
e m
e m to 90%.
las
las iii) Investments were to be valued at ₹ 3,00,000. Alex took over
ag
ag investments at this value.
iv) Nidhi brought ₹ 3,00,000 as her capital and the capital’s of Sonu
and Alex were adjusted in the new profit – sharing ratio. For this
purpose, Current Accounts are to be opened.
Prepare Revaluation Account and Partner’s Capital Accounts.
Or
om
7
. c
. c e m
m as
se
For more Question Papers, Sample Papers, Notes & Syllabus visit
gl
Page 7 of 14
Page 9
ratio of ½, 1/3 and 1/6 respectively. Chandan retired on 1 st April,
2025. The Balance Sheet of the firm on the date of Chandan’s
retirement was as follows:
Balance Sheet as on 31st March, 2025.
Liabilities ₹ Assets ₹
Sundry Creditors 15,600 Bank 3100
General Reserve 9,000 Debtors 30,000
Capital A/cs: Stocks 25,000
Ajay – 40,000 Investments 10,000
Biraj - 36,500 Patents 5,000
Chandan-20,000 Machinery 48,000
96,500
1,21,100 1,21,100
It was agreed: -
i. Goodwill was to be valued at ₹27,000
ii. Depreciation of 10% was to be provided on Machinery.
iii. Patents were to be reduced by 20%.
iv. An old office equipment previously written off was now sold for
₹600.
v. Chandan took over Investments for ₹12,800.
Prepare Revaluation Account, Partners Capital Accounts, and
Balance Sheet.
24 A) Rayan and Doff were partners in a firm sharing profits in the ratio of 6
their capitals. On 31st March, 2025 their Balance Sheet was follows:
Balance Sheet as on 31st March, 2025.
Liabilities ₹ Assets ₹
Creditors 1,70,000 Bank 1,10,000
Workmen
Debtors
Compensation 2,10,000 2,40,000
Reserve
Stock 1,30,000
General Reserve 2,00,000 Furniture 2,00,000
Capital – A/cs: Machinery 9,00,000
Rayan 7,00,000
Doff 3,00,000 10,00,000
15,80,000 15,80,000
On the above date the firm was dissolved.
a) Rayan took 50% of stock at ₹10,000 less than book value.
b) Furniture was taken by Doff for ₹1,50,000 and machinery was sold
8
For more Question Papers, Sample Papers, Notes & Syllabus visit Page 8 of 14
Page 10
.co s e m
s em l a
a ag
for ₹7,50,000.
c) Creditors were paid in full.
d) There was an unrecorded bill for repairs for ₹1,60,000 which was
settled and paid at ₹1,40,000.
e) Dissolution expenses ₹10,000.
Prepare Realisation Account, Partners Capital Accounts and Bank
m
co
Account.
. c om Or
em .
e m
B) Archana, Vandana and Arti were partners in a firm sharing profits and 6
l as
l aslosses in the ratio of 5:3:2. Their Balance Sheet on 31 st March, 2025
ag
ag was as follows:
Balance Sheet as on 31 – 3 - 2025.
Liabilities ₹ Assets ₹
Capitals: Investments 80,000
Archana 80,000 Plant 1,00,000
Vandana 70,000 Stock 40,000
Arti 60,000 Debtors 50,000
m
.co
2,10,000 Cash at Bank 30,000
General Reserve 30,000
e m
s
Creditors 60,000
3,00,000
l a 3,00,000
ag
The firm was dissolved on the above date:
i) Assets realized as follows:
Debtors ₹40,000
Stock ₹50,000
Plant ₹60,000
ii) 25% of the Investments were taken over by Vandana at ₹18,000.
Remaining Investments were taken over by Archana at 10% less
than the Book value.
iii) Expenses of realization ₹20,000 were paid by Arti.
m
.co
Prepare Realisation Account, Partners Capital Accounts and Bank
m
.co m
Account.
m
25 A) Sakhi Ltd. issued 50,000 equity shares of ₹10 each, payable as follows:
s e 6
s e On Application ₹ 3 per share
g la
g la On Allotment ₹ 4 per share
a
a Balance on First and Final Call.
Applications were received for 61,000 equity shares, of which 1000
applications were rejected and remaining applications were allotted on
pro-rata basis. Mr. Sunil who had applied for 600 shares did not pay
allotment and call money. His shares were forfeited and later all the
shares were reissued at ₹8 per shares, fully paid up. Pass journal entries
in the books of Company.
om
9
. c
. c e m
m as
se
For more Question Papers, Sample Papers, Notes & Syllabus visit
gl
Page 9 of 14
Page 11
6
B) Sunshine Ltd issued 30,000 equity shares of ₹10 each, at a premium
of ₹ 2 per share, payable as follows:
₹ 3 on Application
₹ 5 on Allotment (including premium)
₹ 2 on First Call and Balance on Final Call.
Applications were received for 45,000 equity shares and allotment was
made on pro-rata basis in the ratio of 4:3, the remaining application
being rejected and the money refunded. Mr. Ajay who was holding 600
shares did not pay the allotment money and his shares were
immediately forfeited.
First Call was then made and all the money was received. The company
did not make the final call. Show the journal entries in the books of the
Company.
26 A) Pass journal entries relating to issue of debentures in the book of Bhalary 6
Ltd. in each of the following cases:
i) Issued 20,000 8% Debentures of ₹100 each at par, redeemable at
premium of 6%.
ii) Issued ₹4,00,000 10% Debentures of ₹100 each at a premium of
10%, redeemable at a premium of 8%.
iii) Issued 20,000 10% Debentures of ₹100 each at a discount of 10%
redeemable at par.
Or
B) On 1st April, 2024, Radhika Ltd issued 10,000, 12% Debentures of ₹100 6
each at a discount of 10%, redeemable at a premium of 10% after 4
years. Pass journal entries at the time of issue and show the Loss on
Issue of Debentures A/c for four years.
PART – B
(Analysis of Financial Statements)
27 In cash Flow Statement, Rent received by real estate company is classified 1
under:
a) Operating Activities.
b) Investing Activities.
c) Financing Activities.
d) None of the above.
28 The Ideal Liquid Ratio is 1
a) 1:2
b) 1:1
c) 2:1
d) 3:2
29 Comparative Statement is an example of 1
a) Vertical Analysis
b) Horizontal Analysis
10
For more Question Papers, Sample Papers, Notes & Syllabus visit Page 10 of 14
Page 12
.co s e m
s em l a
a ag
c) Ratio Analysis
d) Cash Flow Analysis
Or
Which of the following is not required to be prepared under the companies 1
Act?
m
co
a) Common size statement
om .
b) Balance Sheet
. c
c) Directors and Auditor’s Report
e m
em
d) Statement of Profit and Loss A/c.
l as
l as
30 Zet Ltd. purchased a building for ₹50,00,000 from Jerry Ltd. paying 40% 1
ag
ag
by the issue of 9% Debentures and the balance by cheque. The above
transaction will result in:
a) Decrease in cash and cash equivalents ₹20,00,000.
b) Cash used in investing activities ₹20,00,000.
c) Cash generated from financing activities ₹20,00,000
d) Cash used in investing activities ₹30,00,000
Or
m 1
c. o
Provision for tax for the year ended 31st March, 2025 and 31st March,
2024 were ₹2,80,000 and ₹2,20,000 respectively. During the year,
provision for tax made was ₹2,40,000.
e m
The amount of Tax paid during the year is
l as
ag
a) ₹2,80,000
b) ₹1,80,000
c) ₹3,00,000
d) ₹2,50,000
31 Prepare a Common Size Income Statement for the year ended 31st 3
March, 2025.
Particulars ₹
Revenue from Operations 5,00,000
m
.co
Cost of Revenue from operations 2,50,000
m
.co
Other expenses 1,50,000
Tax @ 40%
e m
e m las
las Or
ag
ag Complete the following Comparative Balance Sheet. 3
Absolute Percentage
Particulars 31-3-24 31-3-25
change change
Share holders
6,00,000 ?? 2,00,000 ??
Fund
om
11
. c
. c e m
m as
se
For more Question Papers, Sample Papers, Notes & Syllabus visit
gl
Page 11 of 14
Page 13
4,00,000 ?? Nil ??
liabilities
Current
?? 3,00,000 1,00,000 ??
Liabilities
Total ?? ?? ?? ??
Non current
8,00,000 ?? ?? 25%
Assets
Current Assets ?? ?? ?? ??
Total ?? ?? ?? ??
32 A) State any three objectives of Financial Statement Analysis. 3
Or
B) Under which major heads and sub heads will the following items 3
be placed in the Balance Sheet of the Company as per schedule III
Part – I of Companies Act, 2013.
i) Proposed Dividend
ii) Goodwill
ii) Prepaid Expenses.
33 A) The Inventory Turnover Ratio is 5 times. Revenue from 4
Operations is ₹5,00,000. Gross profit is 25% on cost. Calculate the
value of Opening Inventory and Closing Inventory if Closing
Inventory is ₹8000 more than Opening Inventory.
Or
B) The Revenue from Operation is ₹10,00,000. Gross Profit is 25%. 4
Operating Expenses is ₹50,000 and Non-Operating expenses is ₹
30,000. Calculate operating ratio and net profit ratio.
34 A) Following are the Balance Sheets of Shai Co Ltd. as on 31 st March, 6
2024 and 2025.
Particulars Note No. 2025 2024
I. Equity & Liabilities: (₹) (₹)
1. Shareholder’s Fund
(a) Share Capital 70,000 60,000
(b) Reserves & Surplus I 44,000 8000
2. Non Current Liabilities
(a) 10% Debentures 50,000 50,000
3. Current Liabilities
(a) Trade Payables 2 25,000 9000
189,000 1,27,000
II. Assets:
1. Non Current Assets
(a) Plant and Machinery 98,000 84,000
(b) Non current Investment 16,000 6000
2. Current Assets:
12
For more Question Papers, Sample Papers, Notes & Syllabus visit Page 12 of 14
Page 14
.co s e m
s em l a
a ag
(a) Current Investments 18,000 20,000
(b) Inventories 49,000 12,000
(c) Cash and Bank balances 8000 5000
1,89,000 1,27,000
Notes to Accounts: 31-3-25 31-3-24
(₹) (₹)
m
co
1. Reserve and Surplus:
. com
General Reserve 30,000 20,000
e m .
s
Surplus i.e. Balance in statement of
m
e
Profit and Loss 14,000 (12,000)
l a
l as 44,000 8,000
ag
g
a Trade Payable:
2.
Sundry Creditors 23,500 6,500
Bills Payable 1,500 2500
25,000 9,000
Additional Information:
i) Depreciation provided on Machinery during the year ₹ 8,000
ii) Interest paid on Debentures ₹ 5,000.
m
Prepare Cash Flow Statement.
m .co
s e
l a
ag Or
B) From the following Balance Sheets of Eastern Co. Ltd, prepare 6
Cash Flow Statement.
Note 31-3-2025 31-3-2024
Particulars
No. ₹ ₹
I. Equity and Liabilities:
1. Shareholders Funds
m
(a) Share Capital 7,00,000 5,00,000
.co
(b) Reserves and Surplus 1 2,50,000 2,00,000
m
.co m
2. Non Current Liabilities
m
(a) Long term borrowings 2 2,50,000 70,000
s e
s e 3. Current Liabilities:
g la
g la (a) Outstanding Expenses 10,000 15,000
a
a (b) Trade Payables
(c) Short Term Provisions 3
50,000
30,000
30,000
15,000
Total 12,90,000 8,30,000
om
13
. c
. c e m
m as
se
For more Question Papers, Sample Papers, Notes & Syllabus visit
gl
Page 13 of 14
Page 15
1. Non Current Assets:
a) Fixed Assets:
i) Tangible Assets 4 8,00,000 4,50,000
ii) Intangible Assets 5 70,000 1,00,000
2. Current Assets:
a) Inventories 1,25,000 1,00,000
b) Trade Receivables 2,50,000 1,50,000
c) Cash and Cash 45,000 30,000
equivalents
Total 12,90,000 8,30,000
Note to Accounts:
31-3-2025 31-3-2024
Particulars
₹ ₹
1. Reserve and Surplus:
General Reserve 1,70,000 1,50,000
Statement of Profit and Loss 80,000 50,000
2,50,000 2,00,000
2. Long Term Borrowings:
Debentures 2,50,000 70,000
3. Short Term Provisions:
Provision for Tax 10,000 5000
Propose Dividend 20,000 10,000
30,000 15,000
4. Tangible Assets:
Plant and Machinery
Less: Accumulated Depreciation 8,80,000 5,00,000
(80,000) (50,000)
8,00,000 4,50,000
5. Intangible Assets:
Goodwill 70,000 1,00,000
Additional Information:
i) Tax paid ₹9,000.
ii) A part of the machine costing ₹ 25,000, accumulated ₹10,000 was
sold for ₹9,000.
*****
14
For more Question Papers, Sample Papers, Notes & Syllabus visit Page 14 of 14
Document Details
| Board / Org | Meghalaya Board |
| Exam | Class 12 |
| Type | Sample Paper |
| Pages | 14 |
| Updated | 03 Nov 2026 |