Maharashtra 12th Std Model Question Paper 2027 Book-Keeping and Accountancy
Finished viewing? Save it for later —
Download Maharashtra 12th Std Model Question Paper 2027 Book-Keeping and Accountancy (PDF · 3 pages)About Maharashtra 12th Std Model Question Paper 2027 Book-Keeping and Accountancy
Maharashtra 12th Std Model Question Paper 2027 Book-Keeping and Accountancy is available here for free download. Published by Maharashtra Board for Class 12, this sample paper can be viewed online or downloaded as a PDF (3 pages). Candidates preparing for Class 12 can use Maharashtra 12th Std Model Question Paper 2027 Book-Keeping and Accountancy to understand the exam pattern, the type of questions asked, and the overall difficulty level.
Frequently Asked Questions
How can I download Maharashtra 12th Std Model Question Paper 2027 Book-Keeping and Accountancy?
Open this page and click the Download button to save Maharashtra 12th Std Model Question Paper 2027 Book-Keeping and Accountancy as a PDF. It is completely free on AglaSem Docs.
Is Maharashtra 12th Std Model Question Paper 2027 Book-Keeping and Accountancy free to download?
Yes. Maharashtra 12th Std Model Question Paper 2027 Book-Keeping and Accountancy can be viewed online and downloaded as a PDF free of cost on AglaSem Docs.
How many pages does Maharashtra 12th Std Model Question Paper 2027 Book-Keeping and Accountancy have?
Maharashtra 12th Std Model Question Paper 2027 Book-Keeping and Accountancy contains 3 pages, which you can read online or download together as a single PDF.
Where can I find more Class 12 study material?
You can find more Class 12 question papers, sample papers, syllabus, and answer keys on AglaSem Docs.
Maharashtra 12th Std Model Question Paper 2027 Book-Keeping and Accountancy – Text
Read the full text of this sample paper below — useful to quickly search, copy and reference the content online without downloading the PDF.
📄 View text version (3 pages)
Page 1
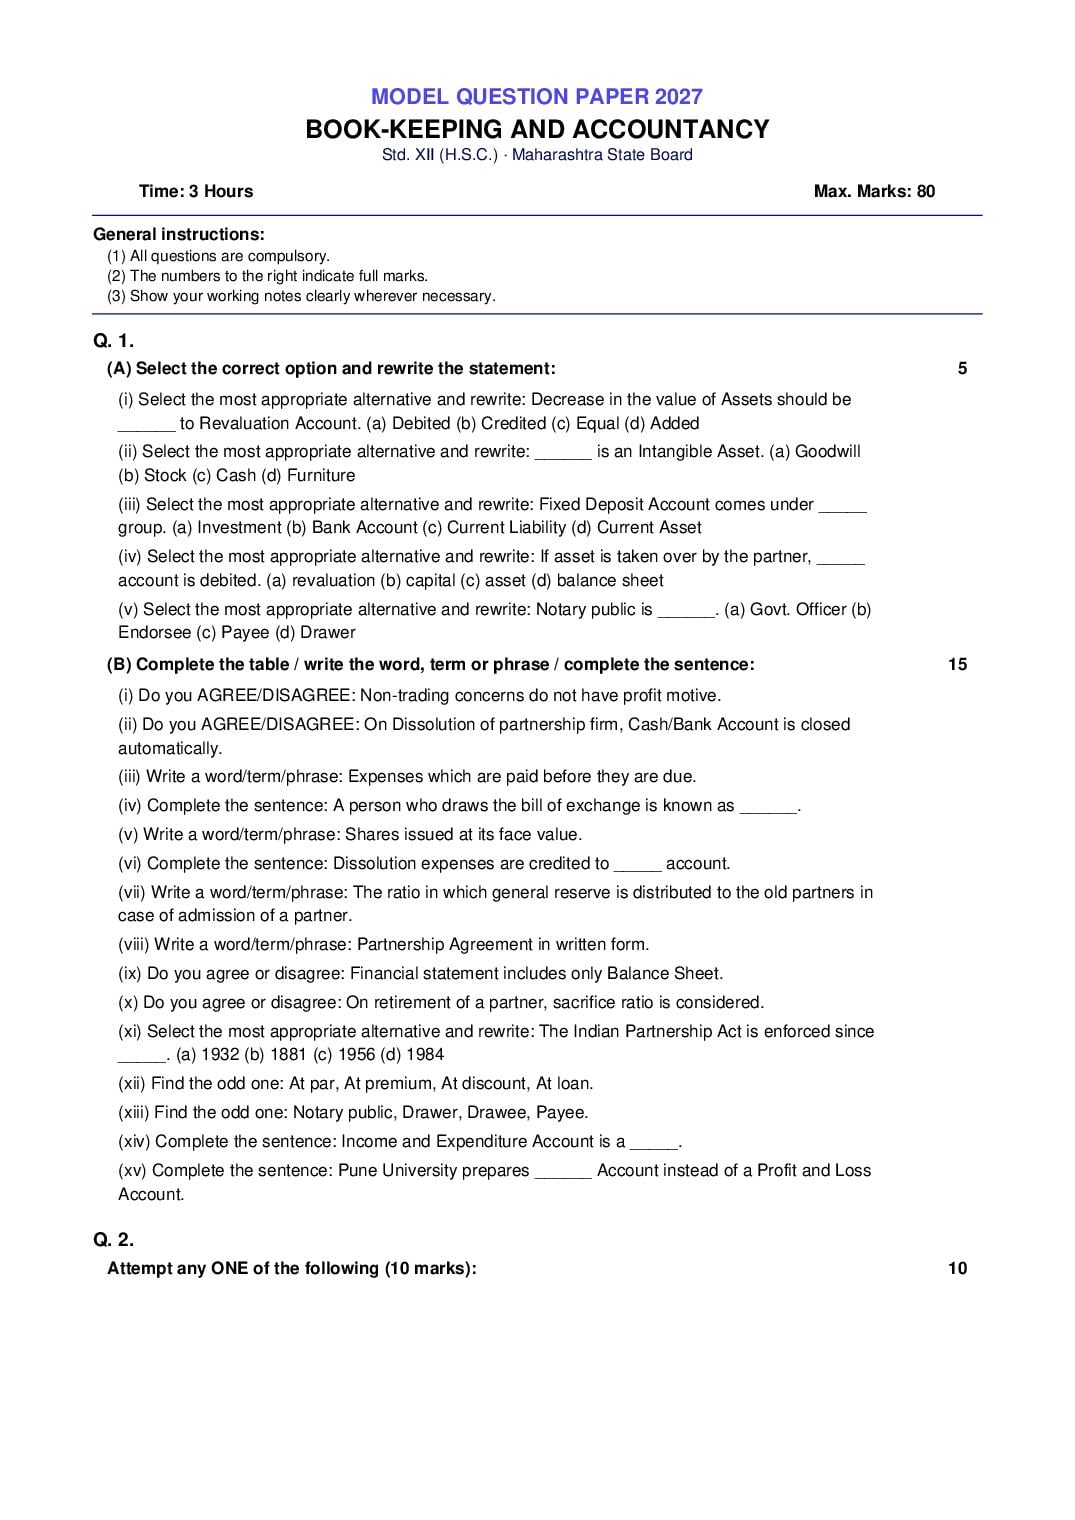
BOOK-KEEPING AND ACCOUNTANCY
Std. XII (H.S.C.) · Maharashtra State Board
Time: 3 Hours Max. Marks: 80
General instructions:
(1) All questions are compulsory.
(2) The numbers to the right indicate full marks.
(3) Show your working notes clearly wherever necessary.
Q. 1.
(A) Select the correct option and rewrite the statement: 5
(i) Select the most appropriate alternative and rewrite: Decrease in the value of Assets should be
______ to Revaluation Account. (a) Debited (b) Credited (c) Equal (d) Added
(ii) Select the most appropriate alternative and rewrite: ______ is an Intangible Asset. (a) Goodwill
(b) Stock (c) Cash (d) Furniture
(iii) Select the most appropriate alternative and rewrite: Fixed Deposit Account comes under _____
group. (a) Investment (b) Bank Account (c) Current Liability (d) Current Asset
(iv) Select the most appropriate alternative and rewrite: If asset is taken over by the partner, _____
account is debited. (a) revaluation (b) capital (c) asset (d) balance sheet
(v) Select the most appropriate alternative and rewrite: Notary public is ______. (a) Govt. Officer (b)
Endorsee (c) Payee (d) Drawer
(B) Complete the table / write the word, term or phrase / complete the sentence: 15
(i) Do you AGREE/DISAGREE: Non-trading concerns do not have profit motive.
(ii) Do you AGREE/DISAGREE: On Dissolution of partnership firm, Cash/Bank Account is closed
automatically.
(iii) Write a word/term/phrase: Expenses which are paid before they are due.
(iv) Complete the sentence: A person who draws the bill of exchange is known as ______.
(v) Write a word/term/phrase: Shares issued at its face value.
(vi) Complete the sentence: Dissolution expenses are credited to _____ account.
(vii) Write a word/term/phrase: The ratio in which general reserve is distributed to the old partners in
case of admission of a partner.
(viii) Write a word/term/phrase: Partnership Agreement in written form.
(ix) Do you agree or disagree: Financial statement includes only Balance Sheet.
(x) Do you agree or disagree: On retirement of a partner, sacrifice ratio is considered.
(xi) Select the most appropriate alternative and rewrite: The Indian Partnership Act is enforced since
_____. (a) 1932 (b) 1881 (c) 1956 (d) 1984
(xii) Find the odd one: At par, At premium, At discount, At loan.
(xiii) Find the odd one: Notary public, Drawer, Drawee, Payee.
(xiv) Complete the sentence: Income and Expenditure Account is a _____.
(xv) Complete the sentence: Pune University prepares ______ Account instead of a Profit and Loss
Account.
Q. 2.
Attempt any ONE of the following (10 marks): 10
Page 2
Liabilities - Capitals: Kaustubh 2,00,000, Ketan 2,80,000; Creditors 68,000; Bills Payable 52,000.
Assets - Building 1,20,000; Machinery 1,40,000; Investment 48,000; Debtors 52,000; Stock 80,000;
Cash 1,60,000. Total 6,00,000. On 1st April 2023 Pranav joins for 1/5th share: (i) Firm Goodwill
valued at Rs.4,00,000; Pranav brings his share of goodwill in cash. (ii) Pranav brings Rs.2,00,000
as share of capital. (iii) Provision for Bad and Doubtful Debts created at 10% on debtors. (iv)
Building valued at Rs.1,60,000. (v) Stock and Machinery reduced by 20%. Prepare (a) Revaluation
Account (b) Partners' Capital Account (c) Balance Sheet of the New Firm.
(ii) Sagar, Suraj and Sahil sharing profit/losses equally. Balance Sheet as on 31st March 2023:
Liabilities - Capitals: Sagar 87,200, Suraj 70,000, Sahil 64,000; Reserve fund 27,000; Creditors
61,800. Assets - Building 1,40,000; Machinery 20,000; Computer 35,000; Goodwill 24,000; Debtors
36,000 less R.D.D. 1,800 = 34,200; Bank 56,800. Total 3,10,000. On 1st April 2023 Sahil retired: (i)
Machinery revalued at Rs.18,800. (ii) Building appreciated by 10% and computer reduced by
Rs.3,800. (iii) Debtors all good and R.D.D. no longer required. (iv) Goodwill of firm valued at
Rs.36,000. (v) Amount payable to Sahil transferred to his Loan Account. Prepare (a) Profit and Loss
Adjustment Account (b) Partners' Capital Account (c) Balance Sheet of the New firm.
Q. 3.
Attempt any ONE of the following (10 marks): 10
(i) Surekha sold goods to Suman on credit for Rs.20,000 for which Suman accepted the bill for 3
months. Surekha discounted the bill with her bank at 10% p.a. on the same day. On due date,
Suman requested Surekha to accept Rs.8,000 with interest Rs.1,000 in cash and to draw a new bill
for the balance for 2 months. Surekha agrees. Before due date Suman retired her acceptance by
paying Rs.11,800. Pass necessary Journal Entries in the books of Surekha.
(ii) Rajeev, Sanjeev and Mahesh partners in Janki Traders sharing profit/losses 2:2:1. Balance
Sheet as on 31st March 2022: Liabilities - Capitals: Rajeev 2,40,000, Sanjeev 80,000, Mahesh
80,000; General Reserve 24,000; Creditors 1,60,000; Bills Payable 56,000. Assets - Machinery
2,00,000; Investment 96,000; Debtors 2,20,000 less R.D.D. 12,000 = 2,08,000; Stock 80,000; Bank
56,000. Total 6,40,000. Partners decided to dissolve the firm. (1) Assets realised: Machinery
1,80,000, Stock 72,000, Investment 84,000, Debtors 1,80,000. (2) Dissolution expenses Rs.12,000.
(3) Goodwill of the firm realised Rs.96,000. Prepare necessary ledger accounts to close the books
of the Partnership Firm.
Q. 4.
Attempt any ONE of the following (8 marks): 8
(i) Pravin, Prashant and Sushil partners sharing profits/losses 5:3:2. Balance Sheet as on 31st
March 2022: Liabilities - Capitals: Pravin 2,00,000, Prashant 1,50,000, Sushil 1,00,000; Reserve
fund 50,000; Creditors 2,50,000. Assets - Loose Tools 1,00,000; Debtors 3,00,000; Livestock
2,00,000; Cash 1,50,000. Total 7,50,000. Sushil died on 31st March 2022: (i) Creditors increased by
Rs.20,000. (ii) Goodwill calculated at 2 years' purchase of average profit of 3 years; profits 2019-20
Rs.1,80,000, 2020-21 Rs.1,20,000, 2021-22 Rs.1,20,000 (Loss); Sushil's share given to him. (iii)
Loose tools and livestock valued at Rs.1,60,000 and Rs.2,40,000 respectively. (iv) R.D.D.
maintained at Rs.20,000. Prepare (a) Revaluation Account (b) Sushil's Capital Account showing
amount payable to his executors (c) working of Sushil's share in goodwill.
(ii) Explain the importance of Computerized Accounting System.
Q. 5.
Attempt any ONE of the following (8 marks): 8
(i) Calculate Current Ratio, Gross Profit Ratio and Net Profit Ratio from the following information:
Debtors 2,50,000; Creditors 1,20,000; Stock 1,50,000; Bills payable 50,000; Cash in hand 2,00,000;
Bank overdraft 30,000; Net sales 16,00,000; Gross profit 8,00,000; Net profit 4,00,000.
(ii) Finolex Co. Ltd. invited applications for 50,000 equity shares of Rs.10 each payable: Rs.3 on
Application, Rs.5 on Allotment, Rs.2 on First and Final call. Applications received for 60,000 equity
shares and pro-rata allotment made to all. All money duly received except Mr. Rahul failed to pay
first and final call on 5,000 equity shares. Enter the above transactions in the books of the company.
Page 3
Solve the following (12 marks): 12
(i) Atharv Art Circle, Sindhudurg, a newly started concern on 1st April 2022. Receipts and Payments
Account as on 31st March 2023: Receipts - To Life Membership Fees 66,000; To Subscriptions
1,20,000; To Donations 54,000 (Total 2,40,000). Payments - By Furniture 36,000; By Postage
12,000; By Office rent 7,800; By Newspaper 900; By Electricity Charges 1,680; By Investment
9,000; By Stationery 12,000; By Laptop 18,000; By Machinery 20,000; By Salary 10,000; By
Balance C/d (Cash in hand 22,620; Cash at bank 90,000) (Total 2,40,000). Adjustments: (i)
Subscription outstanding for 2022-23 Rs.15,000. (ii) Depreciate furniture @10% p.a. (iii) Entire Life
Membership fees and 50% of Donations capitalised. Prepare Income and Expenditure Account for
the year ended 31st March 2023 and Balance Sheet as on that date.
Q. 7.
Solve the following (12 marks): 12
(i) Jayesh and Rupesh partners sharing profits/losses 3:2. Prepare Trading and Profit and Loss
Account for the year ended 31st March 2023 and Balance Sheet as on that date. Trial Balance as
on 31st March 2023: Debit - Purchases 1,63,000; Debtors 45,000; General Expenses 8,000; Stock
(on 1-4-22) 35,000; Premises 1,30,000; Rent (for 10 months) 20,000; Productive wages 5,000;
Furniture (Addition Rs.20,000 made on 01-10-2022) 40,000; Cash at Bank 24,000. Credit - Sales
2,20,000; Creditors 47,000; Return Outward 3,000; Capitals: Jayesh 1,20,000, Rupesh 80,000.
Total 4,70,000. Adjustments: (i) Closing stock valued at Rs.38,000. (ii) Depreciate furniture by 10%
p.a. (iii) Charge interest on capital at 5% p.a. (iv) Goods distributed as free sample Rs.2,000.
This is a model / practice paper built by AglaSem from an analysis of past MSBSHSE board papers. It follows the current board pattern for practice
purpose only.
Document Details
| Board / Org | Maharashtra Board |
| Exam | Class 12 |
| Type | Question Paper |
| Pages | 3 |
| Language | english |
| Updated | 24 Sep 2026 |